
3 British Undervalued Stocks For September 2026
UK government borrowing of £18.3b in August has pushed fiscal questions back to centre stage, and higher bond costs keep the spotlight on cash generation and balance sheet resilience. When public finances feel stretched, investors often look harder for businesses that generate strong cash flows yet trade below their estimated worth. This article highlights three such UK stocks that screen as potentially mispriced on their cash flow profiles.
The three stocks covered below are only a sample from this cash flow opportunity set, and the full screen surfaced 9 more businesses with equally compelling narratives that are not discussed here. If you want to identify and analyze those additional ideas in detail, head straight to the Undervalued Stocks Based On Cash Flows screener.
LSL Property Services (LSE:LSL)
Overview: LSL Property Services runs a capital light UK platform that provides mortgage valuations, financial advice support and franchised estate agency services. Its Surveying & Valuation arm offers the clearest recurring cash flow link to this undervalued cash-flow screener theme.
Operations: LSL Property Services generates about £110.7 million from Surveying and Valuation, £48.2 million from Financial Services and £26.7 million from Estate Agency, all in the United Kingdom.
Market Cap: £254 million
LSL Property Services matters for this cash-flow-focused screen because its valuation work produces recurring fees that can be modelled with unusual clarity in a discounted cash flow framework.
"Rising mortgage refinancing activity, with large volumes of two year and five year products maturing, should sustain higher new lending flows through LSL’s adviser network and underpin continued growth in Financial Services revenue and earnings."
Future cash generation will hinge on how one unseen pressure shapes the balance between those recurring fees and the cost base.
That pressure point is exactly what the full narrative for LSL Property Services unpacks, showing how cash generation, cost discipline and valuation could be decoupling in LSL Property Services’ favour.
AltynGold (LSE:ALTN)
Overview: AltynGold is a London headquartered miner that focuses on gold and silver production from its Sekisovskoye mine and nearby Teren Sai projects in Kazakhstan, giving it a direct link to cash flow based valuation work.
Operations: AltynGold generates about $175 million in revenue from exploration and development at the Sekisovskoye deposit in the Republic of Kazakhstan.
Market Cap: £290 million
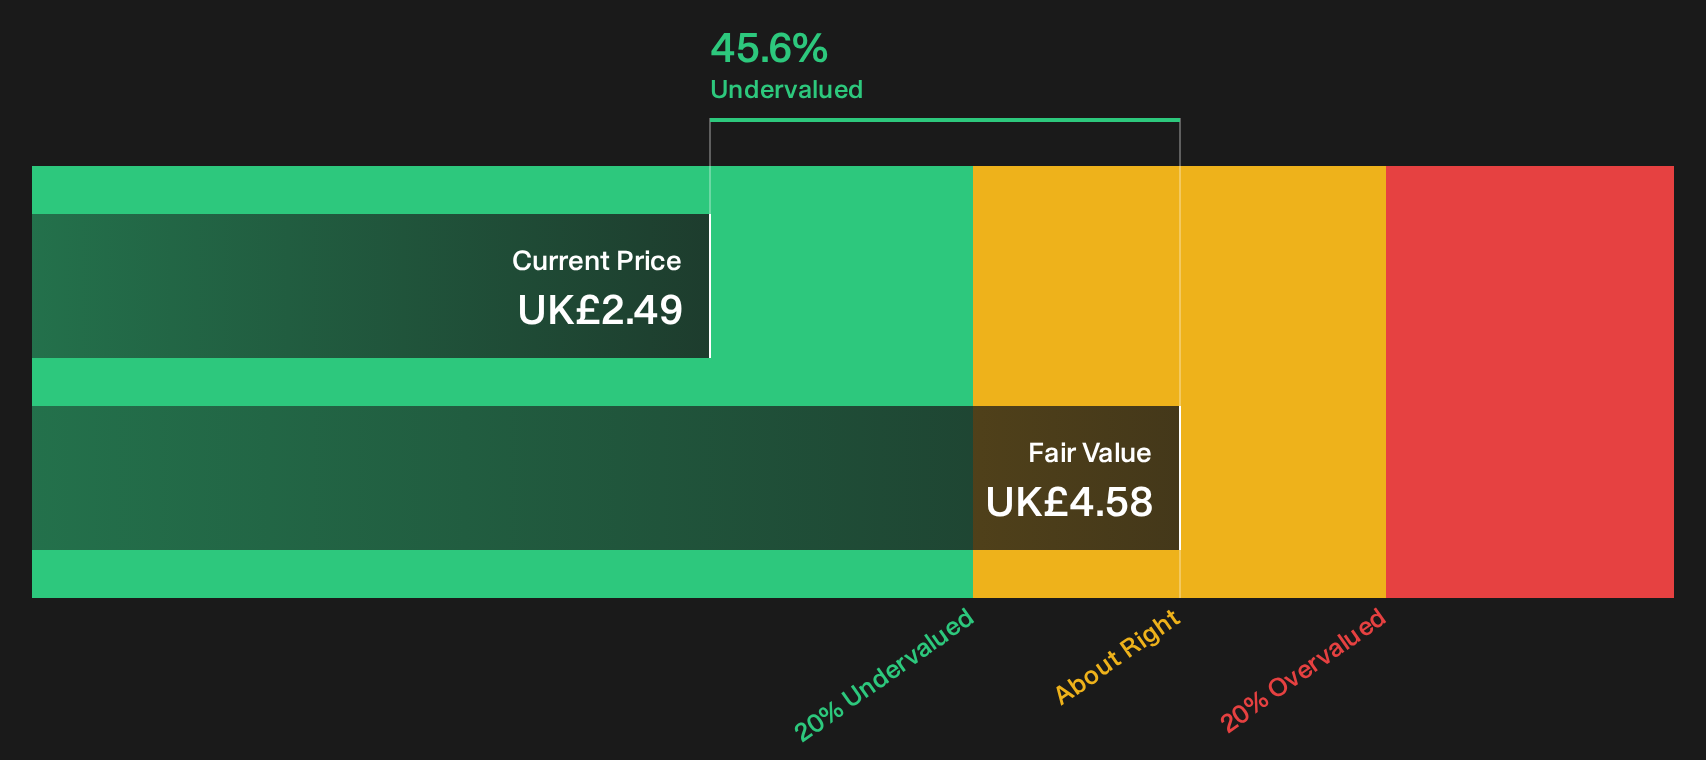
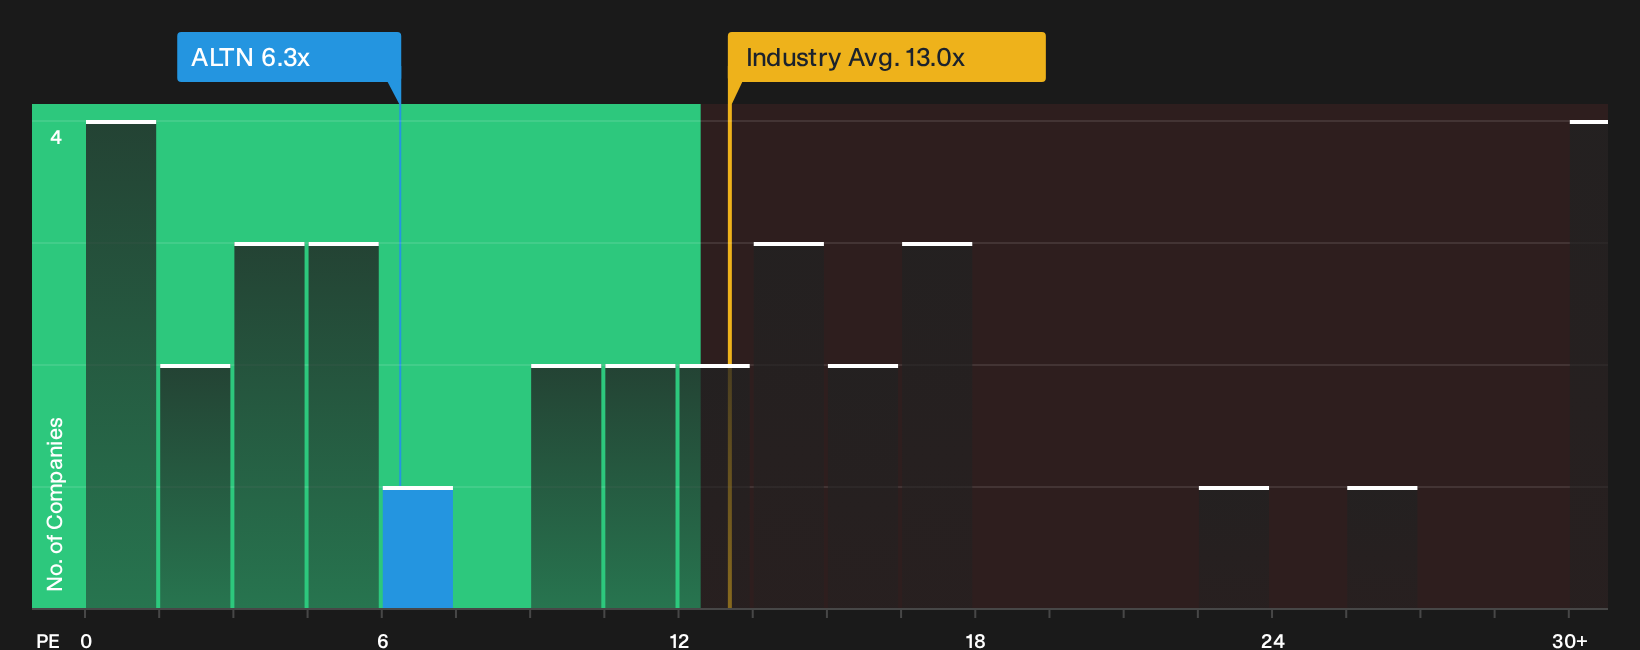
AltynGold screens as interesting for value focused investors because its Sekisovskoye and Teren Sai assets support cash rich mining operations. The shares trade at a low 6.3x P/E, with a 41.3% ROE and strong margins pointing to cash flow that does not fully appear in the current price, depending on how one unseen pressure plays out on those mines.
That hidden pressure makes the cash story for AltynGold especially interesting, so tap into the 4 key rewards and 1 important warning sign to see what the market might be missing.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings runs infrastructure and private equity funds focused on renewable energy and real assets. The business earns recurring management and performance fees.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, mainly across the UK and Australia.
Market Cap: £492 million
Foresight Group Holdings matters for this cash flow screen because its renewable infrastructure funds convert long-term energy projects into fee streams that are easier to model in a discounted cash flow framework.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
Future cash generation hangs on how one unresolved shift in fee mix and fundraising momentum shapes the balance between earnings strength and capital returns.
That shift is exactly what the full narrative for Foresight Group Holdings unpacks, showing how fee mix, fundraising momentum and capital returns could be accelerating in ways the market has not fully priced.

Seeking Alternatives Before The Crowd
Fresh opportunities can move from quiet to breakout quickly, and once momentum takes off, ideal entry points can pass by. Review these under the radar ideas now to consider acting early.
- Identify income-oriented ideas that may continue paying while prices are still declining by scanning the curated pool of 1 dividend fortresses before more yield-focused investors take notice.
- Follow infrastructure-related companies connected to AI buildout using the focused list of 86 AI infrastructure stocks during periods when capital allocation is in focus.
- Consider potential resource-related catalysts by reviewing the curated 36 elite gold producer stocks in case attention shifts toward hard assets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com