
Hammond Power Solutions (TSX:HPS.A) Could Be 30% Undervalued As Texas Expansion Comes Into View
New Texas facility puts Hammond Power Solutions expansion in focus
Hammond Power Solutions (TSX:HPS.A) has signed a long-term lease for a new manufacturing plant in Fort Worth, Texas, aiming to lift transformer output for data centre, electrification, and power infrastructure customers.
The Fort Worth facility is expected to start production in stages in Q4 2027 and is planned to add about CA$250 million of initial manufacturing capacity, targeting U.S.-based demand for Hammond Power Solutions products.
Recent trading has been volatile for Hammond Power Solutions. The CA$255.11 share price sits after a 3.38% 1-day share price gain and an 8.81% 7-day rise, yet the 90-day share price return is down 23.85%. Even with that pullback, momentum over a longer stretch has been strong, with a 56.99% year-to-date share price return and a 1-year total shareholder return of 115.48%. The 5-year total shareholder return is a very large multiple of the starting point, and the Texas expansion news adds another focal point for how investors weigh future capacity against execution risk.
Scan beyond Hammond Power Solutions and compare this expansion story with other power grid and electrification plays using our curated list of 40 power grid technology and infrastructure stocks.
Bulls point to Hammond Power Solutions’ long growth record and Texas capacity plan. Bears focus on execution risk and a sharp run-up in returns. Which side does the current valuation favor?
Most Popular Narrative: 29.7% Undervalued
On the most followed view, Hammond Power Solutions screens as undervalued, with a fair value of about CA$362.71 against the current CA$255.11 share price. This frames the Texas expansion as part of a broader capacity and backlog story rather than a one off headline.
Ongoing electrification efforts, widespread infrastructure investment, and grid modernization, especially in the U.S., are leading to broad-based increases in standard and custom product sales, indicating continued, secular, multi-year revenue expansion potential.
See why 38 investors see Hammond Power Solutions as 30% undervalued.
Result: Fair Value of CA$362.71 (UNDERVALUED)
Still, the bullish Hammond Power Solutions story can break if material costs stay stubbornly high or new plants suffer prolonged inefficiencies and margin drag.
Find out about the key risks to this Hammond Power Solutions narrative.
Another View on Hammond Power Solutions’ Valuation
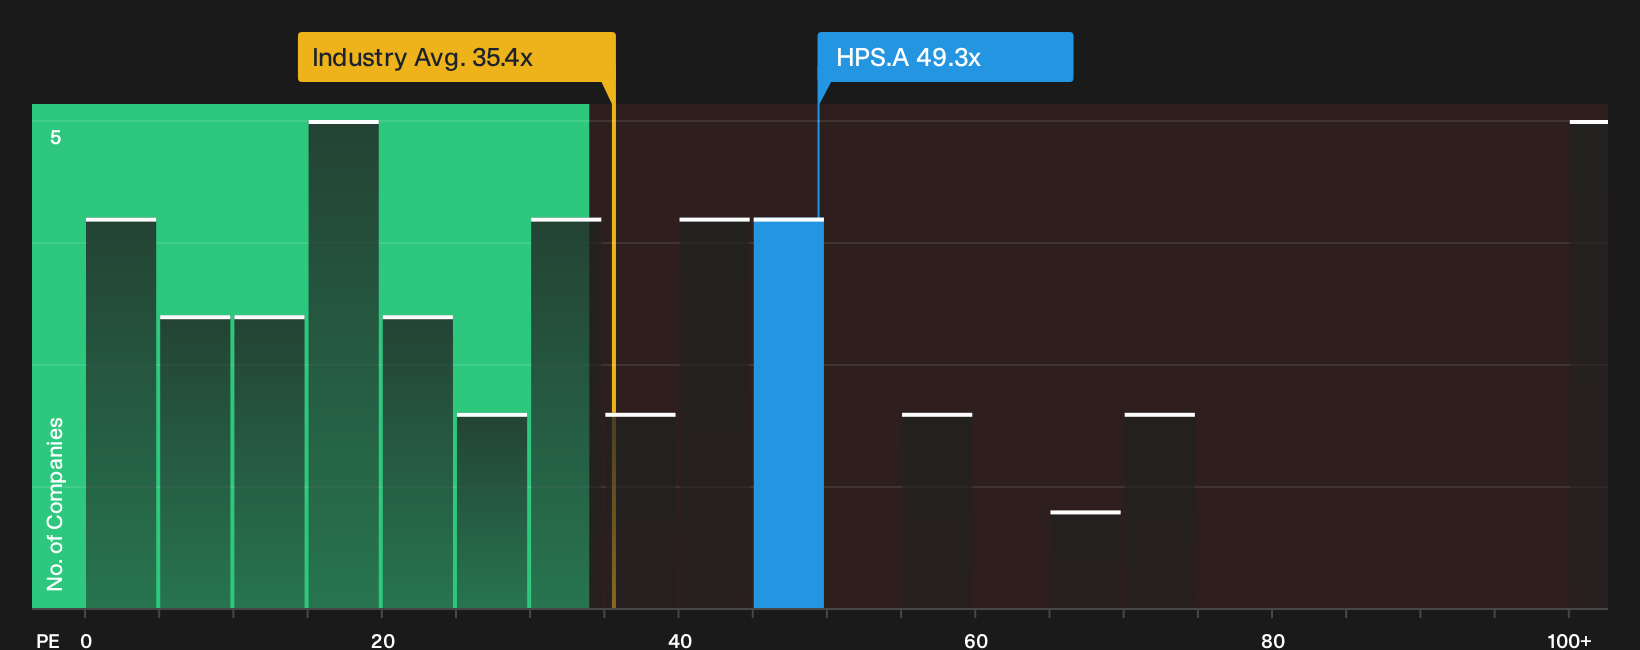
There is a twist. On simple earnings multiples, Hammond Power Solutions does not look cheap. The shares trade on a P/E of 49.3x, while the fair ratio sits at 44.2x and both the North American Electrical industry and peer group sit lower at 35.4x and 43x. That gap points to higher expectation risk if growth or margins fall short.
Before leaning too heavily on one number, it helps to step back and see what the rest of the valuation work suggests about Hammond Power Solutions. This includes how those earnings ratios compare to its cash flow profile and balance sheet strength, in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Hammond Power Solutions story feels finely balanced between optimism and caution, do not sit on the fence and let others frame it for you. Run the numbers, stress test your thesis, and weigh both risks and upside using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Hammond Power Solutions?
Do not let your research stop with Hammond Power Solutions. Fresh ideas often come from comparing different business models, risk levels, and income profiles side by side.
- Target potential mispricing by weighing quality, balance sheets, and cash generation using the 6 high quality undervalued stocks.
- Build a steadier income stream by scanning companies with strong payout profiles through the 1 dividend fortresses.
- Dial back risk while staying invested by filtering for resilient businesses using the 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com