
What NetScout Systems (NTCT)'s AI Data Access Upgrade Means For Shareholders
- NetScout Systems recently announced Model Context Protocol connectivity for its Omnis AI Insights platform, giving AI assistants on-demand access to its AI-ready Smart Data built from Adaptive Service Intelligence and integrated through Omnis Sensor and Omnis Streamer.
- The update pushes network intelligence closer to the data source and aims to cut telemetry processing costs while making existing NetScout deployments more useful across AIOps, observability, security, and analytics workflows.
- The next area of focus will be how this AI-ready Smart Data move could reshape NetScout Systems' broader investment narrative and risk profile.
NetScout Systems Investment Narrative Recap
To own NetScout Systems, you need to believe its service assurance and cybersecurity tools can stay relevant as customers adopt AI driven operations, 5G and cloud, and as IT teams consolidate vendor lists. The MCP enabled Omnis AI Insights update fits that story, but the near term thesis still leans on converting this AI ready Smart Data into repeatable use cases and larger deals.
The main short term swing factor is execution on AI centric deployments inside existing enterprise and federal accounts, while keeping service provider softness contained. The biggest risk is that cloud native tools and platform consolidation slow demand for legacy oriented offerings faster than Omnis AI Insights and newer capabilities gain traction. The MCP news does not change that risk in a material way yet.
The MCP connectivity launch is the key announcement here. It pushes NetScout Systems deeper into AI infrastructure by making its Adaptive Service Intelligence output easier for models and assistants to consume across security, observability and analytics stacks. That aligns directly with the current catalyst narrative around AI driven differentiation and higher value contracts.
Operationally, MCP support could make NetScout more visible inside ecosystems like Splunk, ELK Stack, Datadog, ServiceNow and Dynatrace, since Smart Data can flow into those tools with less integration effort. The execution watchpoints stay familiar. Prove that customers actually standardize workflows on Omnis AI Insights, keep token and infrastructure cost savings tangible, and avoid letting slower growing segments dilute the contribution from higher growth cybersecurity offerings.
NetScout Systems' narrative projects US$954.2 million revenue and US$122.2 million earnings by 2029. This implies 3.5% yearly revenue growth and an earnings increase of about US$26.7 million from current earnings of US$95.5 million.
Discover how NetScout Systems' fair value indicates a 7% potential upside to its current price that could close sooner than many investors expect.
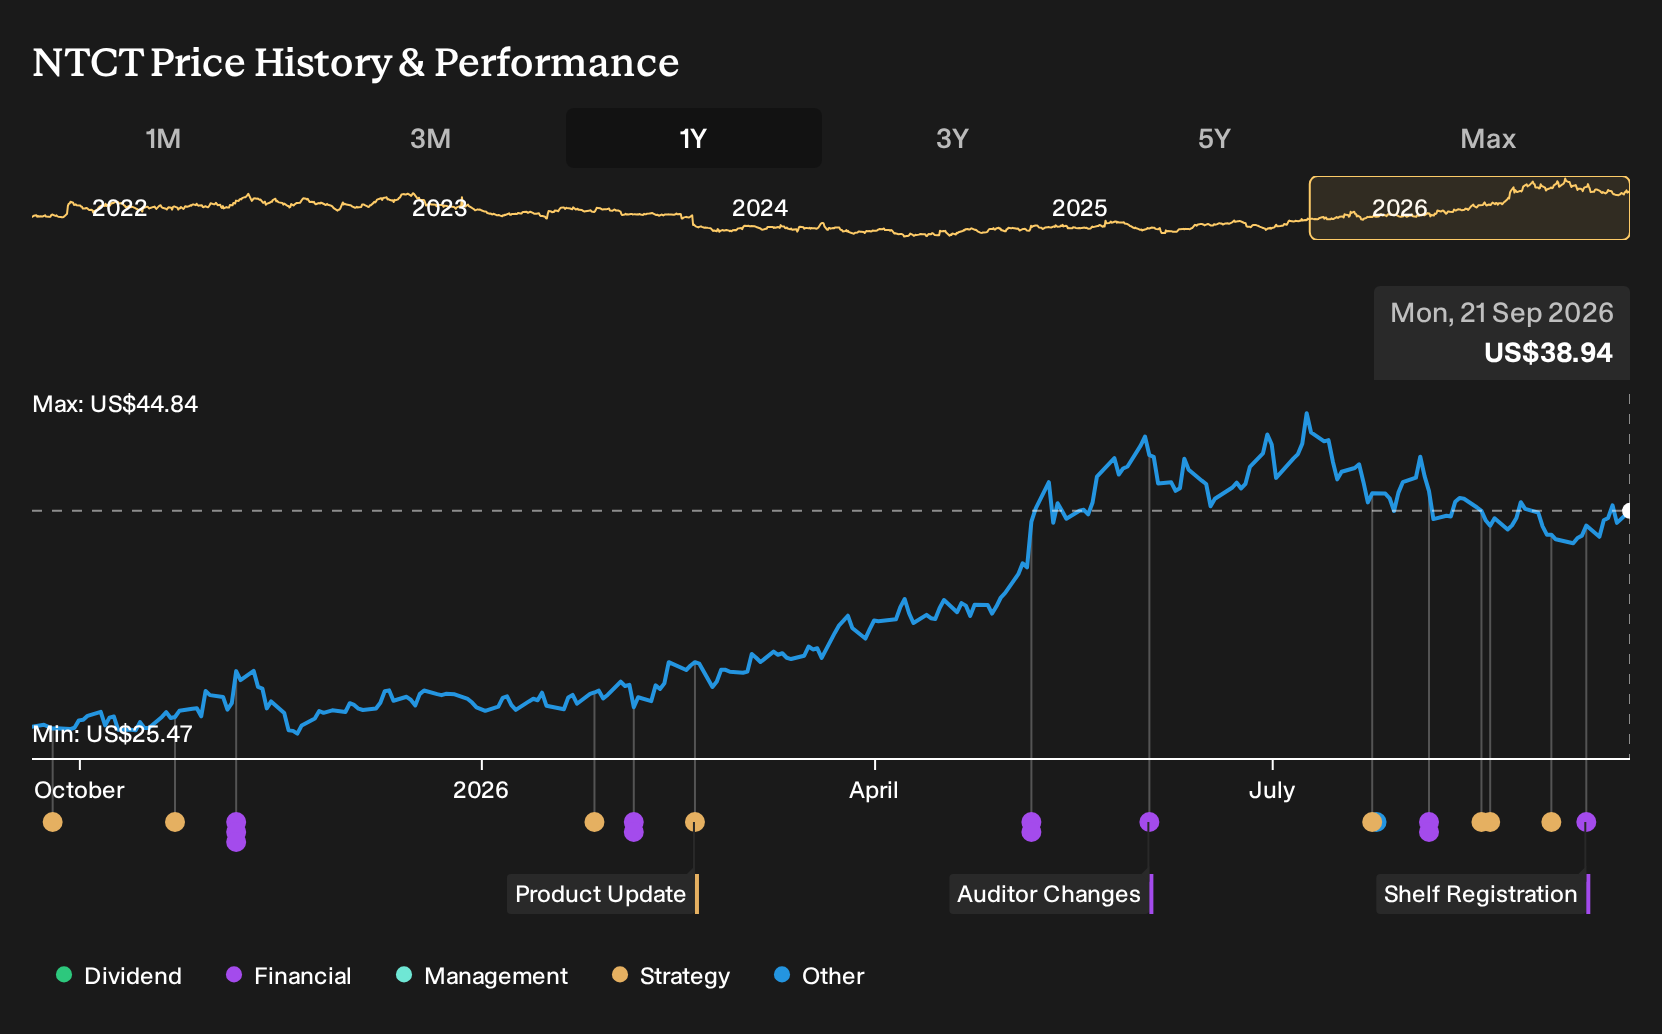
Exploring Other Perspectives
For NetScout Systems, the lowest analyst cohort leans hard into the risk that cloud native and SaaS platforms squeeze its older hardware and point tools. These analysts still model revenue of about US$944.2 million and earnings of US$123.7 million by 2029, yet see a lower P/E of 27.1x as more realistic. That is a more cautious story than consensus, and none of these views include the new MCP connectivity yet, so you may want to explore both sets of assumptions and decide which feels closer to your own expectations.
Explore 4 other NetScout Systems fair value estimates, including one that suggests it could be worth just $37.13.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective based on research and analysis.
- A great starting point for your NetScout Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetScout Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetScout Systems' overall financial health at a glance.
Looking For More Ideas Beyond NetScout Systems?
If this NetScout Systems story has you rethinking how AI ready infrastructure fits into a portfolio, the next step is to widen the search. Use the Simply Wall St Screener to quickly surface other companies that match the kind of quality, risk and income profile you want instead of relying on headlines or hunches.
- If you want resilient businesses that aim to keep downside risk in check, start with a 30 resilient stocks with low risk scores to see which stocks align with that mindset.
- For investors who care most about rock solid finances and clean balance sheets, filter for companies in the list of solid balance sheet and fundamentals (23 results) and focus your research time where the fundamentals already look robust.
- If you are hunting for lesser known opportunities with strong underlying metrics, scan the 17 high quality undiscovered gems and build your own watchlist of potential future additions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com