
September 2026's High Insider Ownership Growth Leaders
The United States market has shown a positive trend recently, rising 1.8% over the past week and 13% over the last year, with earnings projected to grow by 17% annually in the coming years. In this environment, growth companies with high insider ownership can be particularly appealing as they often indicate strong alignment between management and shareholders' interests, potentially enhancing investor confidence.
Top 10 Growth Companies With High Insider Ownership In The United States
| Name | Insider Ownership | Earnings Growth |
| Uxin (UXIN) | 34.3% | 69.4% |
| Upstart Holdings (UPST) | 14.0% | 68.4% |
| Standard Nuclear (STDN) | 18.8% | 61.3% |
| Precigen (PGEN) | 11.7% | 55.4% |
| Nu Holdings (NU) | 22.8% | 22.5% |
| Karman Holdings (KRMN) | 14.4% | 56.2% |
| Himax Technologies (HIMX) | 29.2% | 70.2% |
| Dave (DAVE) | 16.7% | 23.6% |
| Carlyle Group (CG) | 27.4% | 22% |
| Almonty Industries (ALM) | 10.8% | 38% |
Underneath we present a selection of stocks filtered out by our screen.
Hennessy Capital Investment VII (HVII)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Hennessy Capital Investment Corp. VII is a company without significant operations, with a market cap of $260.23 million.
Operations: Revenue segments for the company are not applicable as it does not have significant operations.
Insider Ownership: 25.4%
Hennessy Capital Investment Corp. VII is undergoing significant changes, including a business combination with ONE Nuclear Energy LLC and a corporate move from the Cayman Islands to Delaware. This transition aligns with its strong growth prospects, as its revenue is forecasted to grow at 71.5% annually, significantly outpacing the US market average. Despite recent earnings declines, projected earnings growth of 78.9% per year remains robust, though high share price volatility poses a risk for investors seeking stability.
- Navigate through the intricacies of Hennessy Capital Investment VII with our comprehensive analyst estimates report here.
- In light of our recent valuation report, it seems possible that Hennessy Capital Investment VII is trading beyond its estimated value.

Dingdong (Cayman) (DDL)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Dingdong (Cayman) Limited operates as an e-commerce company in China with a market cap of approximately $492.43 million.
Operations: The company's revenue primarily comes from its online retail segment, which generated CN¥18.55 billion.
Insider Ownership: 27.7%
Dingdong (Cayman) Limited is positioned for growth with expected earnings to increase by 56.29% annually, and the company is forecasted to become profitable within three years, outpacing average market growth. Recent Q2 results showed revenue of CNY 73.2 million, up from CNY 53.74 million a year ago, and net income rose significantly to CNY 269.02 million. The stock trades at a substantial discount compared to its estimated fair value, though recent executive changes may impact investor sentiment.
- Take a closer look at Dingdong (Cayman)'s potential here in our earnings growth report.
- Insights from our recent valuation report point to the potential undervaluation of Dingdong (Cayman) shares in the market.

Nuvation Bio (NUVB)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Nuvation Bio Inc. is a clinical-stage biopharmaceutical company dedicated to developing cancer treatment product candidates, with a market cap of approximately $2.05 billion.
Operations: The company's revenue segment is primarily derived from oncology development activities, totaling $169.90 million.
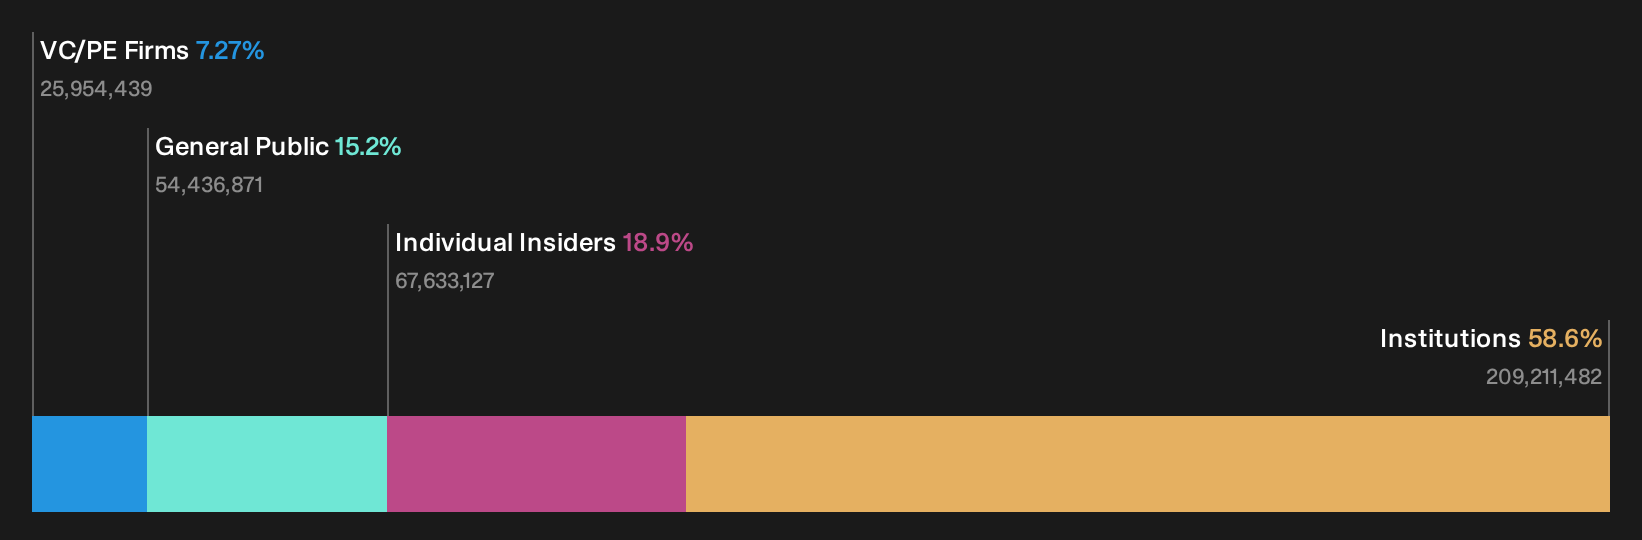
Insider Ownership: 18.9%
Nuvation Bio is poised for growth with projected revenue expansion of 31.6% annually, surpassing the US market average. The company recently received FDA approval for IBTROZI, a ROS1 inhibitor for advanced non-small cell lung cancer, underscoring its innovative pipeline. Despite trading significantly below estimated fair value, Nuvation faces challenges such as being dropped from several Russell indexes and reporting a net loss of US$62.84 million in Q2 2026.
- Dive into the specifics of Nuvation Bio here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Nuvation Bio is priced lower than what may be justified by its financials.
Summing It All Up
- Explore the 179 names from our Fast Growing US Companies With High Insider Ownership screener here.
- Looking For Alternative Opportunities? Uncover the next big thing with financially sound penny stocks that balance risk and reward.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com