
Nordson (NDSN) Just Gave Investors Something To Think About
Nordson’s new Vantage XL launch puts semiconductor tools in focus
Nordson (NDSN) has introduced its ASYMTEK Vantage XL fluid dispensing system, aimed at larger semiconductor panels that serve AI infrastructure, high-performance computing, and automotive electrification manufacturers.
The platform is built for panel-level packaging, a production approach that can support higher throughput and more cost-efficient assembly compared with traditional wafer-focused methods.
Nordson’s share price has eased over the past month, with a 30-day share price return of 5.38% in the red. Yet the stock still carries firm momentum, given a year-to-date share price return of 30.42% and a 1-year total shareholder return of 41.24% that points to investors reassessing its long-run role in semiconductor and industrial tools.
Scan beyond Nordson and see how other precision manufacturers are positioned for the same AI and semiconductor surge with the curated 87 AI infrastructure stocks.
Nordson appears to be a high-quality industrial story, spanning diversified fluid systems as well as newer semiconductor tools. The share price has already risen significantly this year, and the key question now is whether that strength is already fully reflected in today’s valuation.
Most Popular Narrative: 1% Undervalued
Nordson’s most followed valuation narrative puts fair value at about $319 per share, only slightly above the last close at $314.35. As a result, the focus shifts from a big discount to how durable its earnings and backlog story really looks.
Demand for advanced technology solutions is accelerating, especially in semiconductor packaging and electronics assembly, as customers ramp capacity for AI, cloud, and advanced consumer devices. Nordson's exposure to the back end of these markets and its ongoing new product launches are expected to drive sustained revenue growth and market share gains.
See why 14 investors see Nordson as 1% undervalued.
The narrative uses an 8.66% discount rate and a fair value estimate of $319.13, which leaves Nordson trading only about 1.5% below that level. That tight gap suggests analysts see current pricing as broadly in line with their long term earnings and margin assumptions rather than a clear bargain or an obvious excess.
Earnings forecasts of 11.3% annual profit growth and a modeled net margin of about 20.5% feed into this view, along with a future P/E assumption near 30.4x on projected 2029 earnings. Those inputs reflect confidence in Nordson’s recurring revenue mix and semiconductor heavy Advanced Technology Solutions segment, but they also leave limited room for disappointment if order timing or acquisition execution falls short.
Result: Fair Value of $319 (ABOUT RIGHT)
Still, the Nordson narrative could be knocked off course if polymer processing and automotive demand remain weak or if acquisition integration fails to deliver the expected benefits.
Find out about the key risks to this Nordson narrative.
Another View on Nordson’s valuation
Nordson may look roughly fairly priced against that $319 fair value narrative, yet the SWS DCF model tells a different story. On that measure, the shares at $314.35 sit above an estimated future cash flow value of $294.56, which implies investors are paying up today for long term optimism.
That kind of gap can still make sense if you think cash generation will beat current assumptions, or if you put a premium on Nordson’s earnings quality and semiconductor exposure. It also raises a straightforward question: How much are you personally willing to pay above modeled cash flows for that story to play out?
Look into how the SWS DCF model arrives at its fair value.
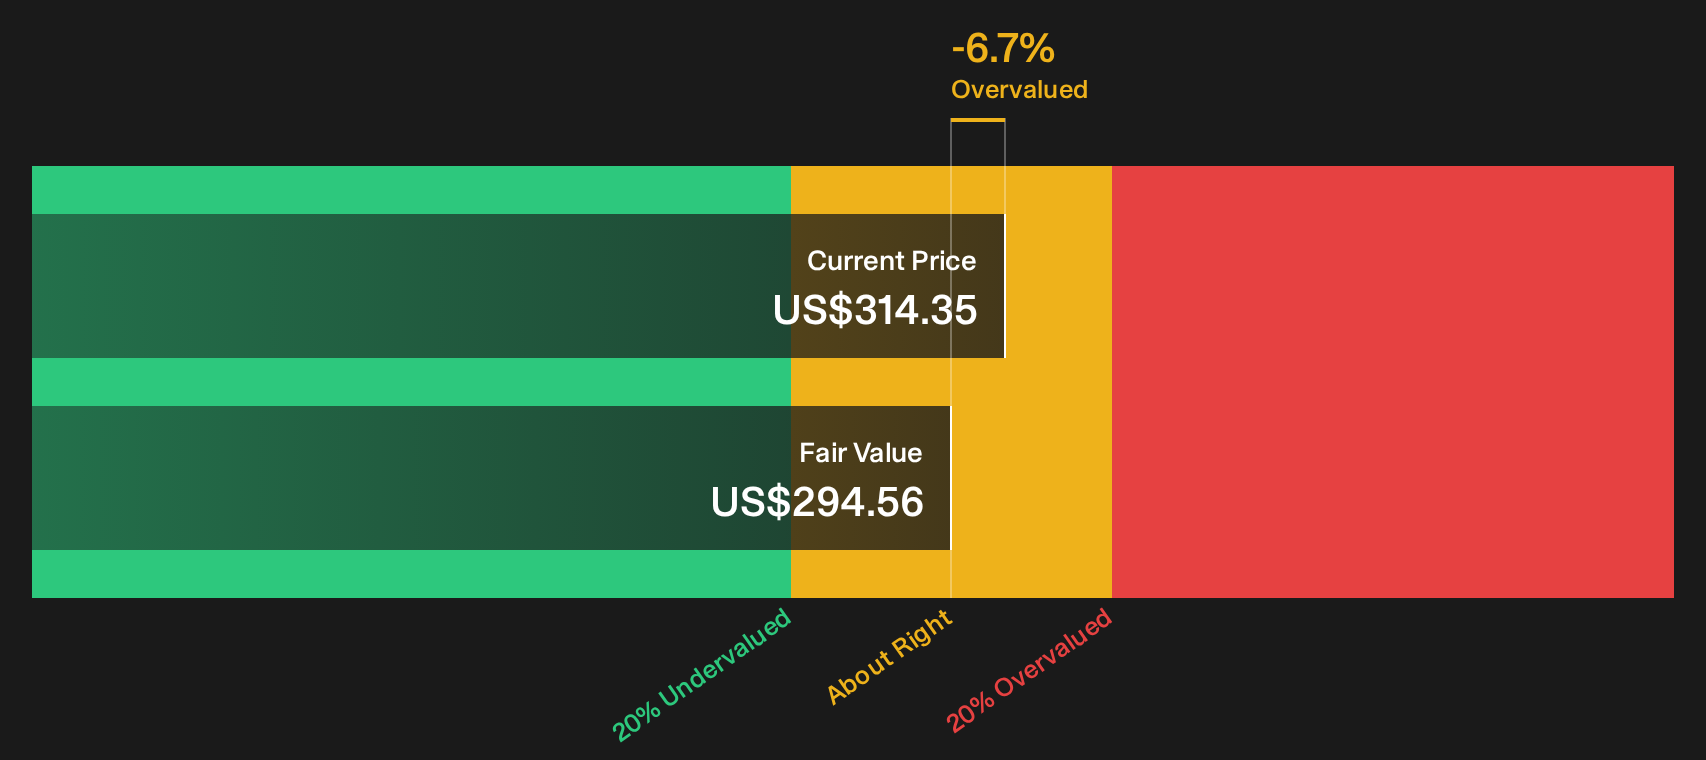
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nordson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Nordson story feels finely balanced between optimism and caution, take that as your cue to act promptly. Stress test the assumptions yourself, then weigh both the potential benefits and the red flags by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Nordson-like investment ideas?
If Nordson’s setup has you thinking about your next move, do not stop here. Broaden your watchlist now so you are not chasing the crowd later.
- Target resilience first by scanning a curated 30 resilient stocks with low risk scores that focuses on businesses with steadier risk profiles and fewer balance sheet surprises.
- Hunt for potential bargains using the 30 high quality undervalued stocks that highlights companies combining quality fundamentals with prices that sit below modeled fair value.
- Sharpen your income stream by reviewing a 7 dividend fortresses geared toward higher yielding stocks that pair sizeable payouts with sturdier financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com