
Cactus (WHD) Expands Its Pressure Control Footprint, Is The Premium Already Priced In?
Cactus (WHD) has drawn fresh attention after recent share performance data showed a 1 day gain of about 1.2%, following a modest move over the past week and a decline over the past month.
At a share price of US$67.45, Cactus has seen momentum cool slightly over the past month, even after a strong 90 day share price return of 27.6% and a year to date gain of 43.4%. The 1 year total shareholder return of 74.5% points to investors recently rewarding the story more fully than price moves alone suggest.
Scan how Cactus compares to other potential breakouts by reviewing a hand picked 30 high quality undervalued stocks that combine strong fundamentals with recent share price momentum.
Bulls see Cactus as a quality pressure control and spoolable pipe business, and they argue that recent momentum only starts to reflect this. Skeptics point to the run already logged. Which story will the valuation support next?
Most Popular Narrative: 20% Undervalued
Cactus is trading at $67.45 against a widely followed fair value estimate of $67.56, which implies roughly 20% upside once the discount model is applied. That pricing gap sits on top of a business already generating $1,363.0m of revenue and $81.9m of net income.
The acquisition of a majority interest in Baker Hughes' Surface Pressure Control business will significantly expand Cactus' geographic footprint and customer base into the Middle East, an area poised for long-term energy infrastructure investment and supply security. This is likely to drive sustained revenue growth and higher earnings resiliency.
See why 8 investors see Cactus as 0% undervalued.
Result: Fair Value of $67.56 (UNDERVALUED)
Still, the bullish Cactus story could be challenged if tariffs keep input costs elevated, or if weaker U.S. drilling activity further pressures demand for its equipment.
Find out about the key risks to this Cactus narrative.
Another View: What Cactus’ P/E Is Telling You
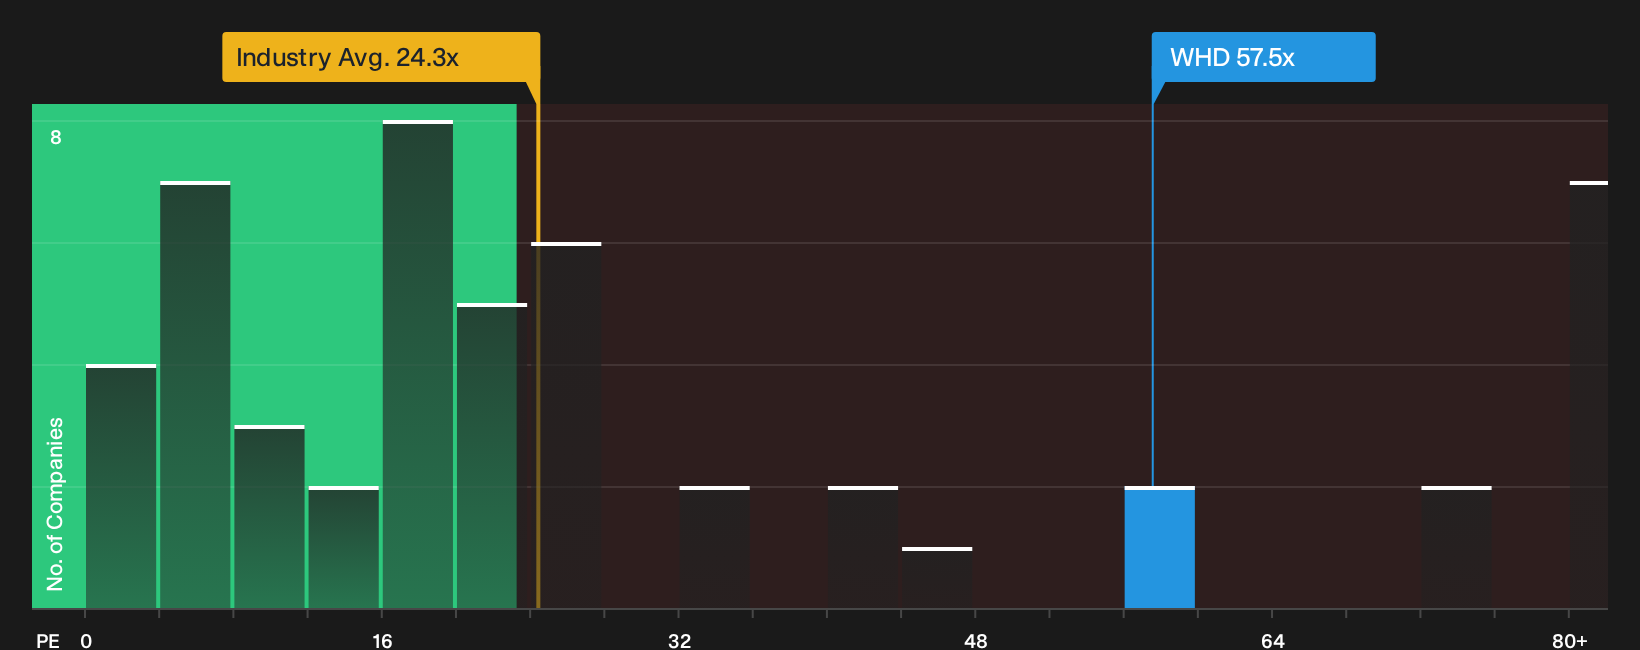
The earlier narrative leans on fair value around $67.56, yet the market is paying a very different multiple. Cactus trades on a P/E of 57.5x, compared with 24.2x for the US Energy Services industry and a fair ratio estimate of 43.5x. That gap points to meaningful valuation risk if sentiment cools.
Investors weighing that premium against growth expectations may want to see what the numbers imply in more detail through our valuation breakdown, starting with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Cactus story so far. If you want to move quickly and cut through the noise, start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Cactus?
If you stop with Cactus, you risk missing other setups that fit your style. Use the screener to help turn raw market noise into focused, actionable ideas.
- Target dependable income streams by reviewing companies in the 7 dividend fortresses that may better align with your cash flow goals.
- Spot resilient balance sheets early through our list of solid balance sheet and fundamentals (23 results) if you want financially stronger candidates on your watchlist.
- Hunt for lesser known opportunities by scanning the 17 high quality undiscovered gems before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com