
Block (XYZ) Could Be 25% Undervalued Following Square Expansion Wins
Block (XYZ) is back in focus after Ideal Nutrition expanded its use of Square’s tools while pursuing a national footprint, tying much of its in-store, online, and franchise operations to Block’s ecosystem.
Recent trading reflects that mixed backdrop. Block’s 1-day share price return of 2.14% contrasts with a 30-day share price return that is down 5.17%. Meanwhile, the 19.59% year-to-date share price gain and 3-year total shareholder return of 70.89% point to momentum that has been building over a longer stretch as investors weigh product expansion wins like Ideal Nutrition and regulatory steps such as the Builders Bank & Trust application.
Scan beyond Block to spot other payment and fintech players building similar ecosystems through our hand picked 30 high quality undervalued stocks.
Block’s share price has pulled back over the past month while still trading well below both analyst targets and intrinsic value estimates. Is that gap signalling an opportunity, or a warning on where fair value really sits?
Most Popular Narrative: 20% Undervalued
Block’s most followed valuation story pegs fair value at $97.60, compared with the recent $77.91 close. Supporters see the sizeable gap as grounded in specific product and earnings drivers rather than hope.
The scaling and innovation within Square for Businesses highlighted by the launch of new hardware like Square Handheld, adoption of omnichannel commerce tools, and growing field/telesales teams positions Block to further capture share from the global trend toward digitalization and consolidation of small business commerce, supporting topline growth and eventual margin expansion as the business scales internationally.
Aggressive investments in international expansion (25% YoY GPV growth in international markets) and upmarket sales motions (rapid ramp in field/telesales, strong ROI and payback periods) increase the platform's total addressable market, diversify revenue streams, and create long-term compounding effects on both revenue and operating income, as new customer cohorts and markets mature.
See why 189 investors see Block as 20% undervalued.
Result: Fair Value of $97.60 (UNDERVALUED)
Still, heavy reliance on Cash App engagement and exposure to volatile Bitcoin related income could quickly challenge Block’s upbeat valuation story.
Find out about the key risks to this Block narrative.
Another View: What Block’s P/E Is Telling You
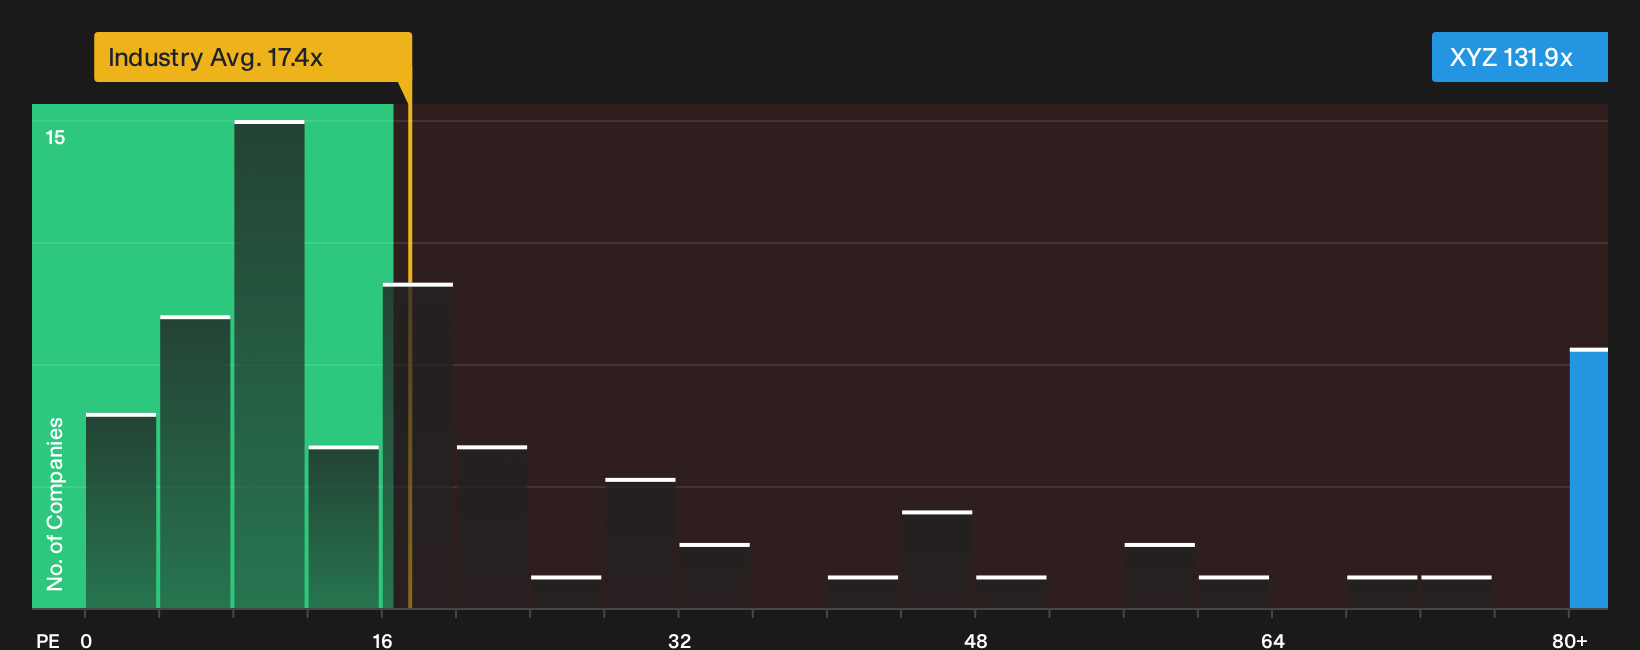
While the SWS DCF model points to undervaluation, the simple earnings multiple sends a very different signal for Block. The stock trades on a P/E of 131.9x, compared with 17.4x for the US Diversified Financial industry, 21.7x for peers, and a fair ratio of 35.8x that the market could move towards. That gap suggests a lot of optimism is already in the price, so how much shortfall in future earnings would it take to compress that multiple and hit returns?
Before leaning on the current earnings multiple alone, it is worth stress testing the underlying assumptions in the valuation breakdown and how sensitive your thesis is to a lower P/E over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Block story so far? If you want to move fast and build your own view from the ground up, start with the 3 key rewards and 3 important warning signs.
Looking for more Block adjacent investment ideas?
If you stop with Block, you only see part of the opportunity set. Take two minutes to scan a broader watchlist and you might spot your next winner.
- Target resilience by checking companies that feature in our 30 resilient stocks with low risk scores, so you are not relying on a single story to carry your portfolio.
- Hunt for quality at a discount by reviewing the 30 high quality undervalued stocks, where solid fundamentals meet prices that may not fully reflect them yet.
- Broaden your opportunity set with the 17 high quality undiscovered gems, and get ahead of the crowd on businesses that are not widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com