
Huntington Bancshares (HBAN) Cuts Guidance Following Fed Rate Hike, But Is It A Bargain
Huntington Bancshares (HBAN) is reshaping its playbook after the latest Federal Reserve rate hike, cutting 2027 earnings guidance and 2026 net interest income growth expectations, while lifting its 2027 share repurchase goal by US$200 million.
Recent trading shows that momentum in Huntington Bancshares has cooled, with the share price down 5.8% over the past month and 8.2% year to date. However, the 3 year total shareholder return of about 74% points to a much stronger longer term payoff profile for investors who stayed in through earlier volatility.
Compare Huntington Bancshares' playbook shift with other regional lenders by scanning hand picked list of solid balance sheet and fundamentals (23 results) that may be positioned differently on rates, funding costs, and capital return plans.
Huntington Bancshares now trades at a steep discount to both analyst targets and an estimated fair value. The open question is whether that gap reflects opportunity or a clear warning from the market on future risks.
Most Popular Narrative: 20% Undervalued
The most followed narrative pegs Huntington Bancshares' fair value at about $20.04, compared with the recent $16.04 close, which frames the current discount as material and worth understanding in detail.
The main thing that has to go right is Huntington Bancshares successfully executing its shift toward larger, recurring fee income streams and partnership-driven cost and revenue synergies, while managing ongoing net interest margin pressure.
The current valuation implies that Huntington Bancshares’ lowered 2027 earnings and return targets, along with planned share buybacks and dividend, are being discounted as if the company’s partnership playbook and fee growth may not fully translate into sustained share price upside.
See why 50 investors see Huntington Bancshares as 20% undervalued.
Result: Fair Value of $20.04 (UNDERVALUED)
Still, the Huntington Bancshares story can break if higher funding costs bite harder than expected or if partnership integrations keep expenses elevated longer than planned.
Find out about the key risks to this Huntington Bancshares narrative.
Another View: Huntington Bancshares Through The P/E Lens
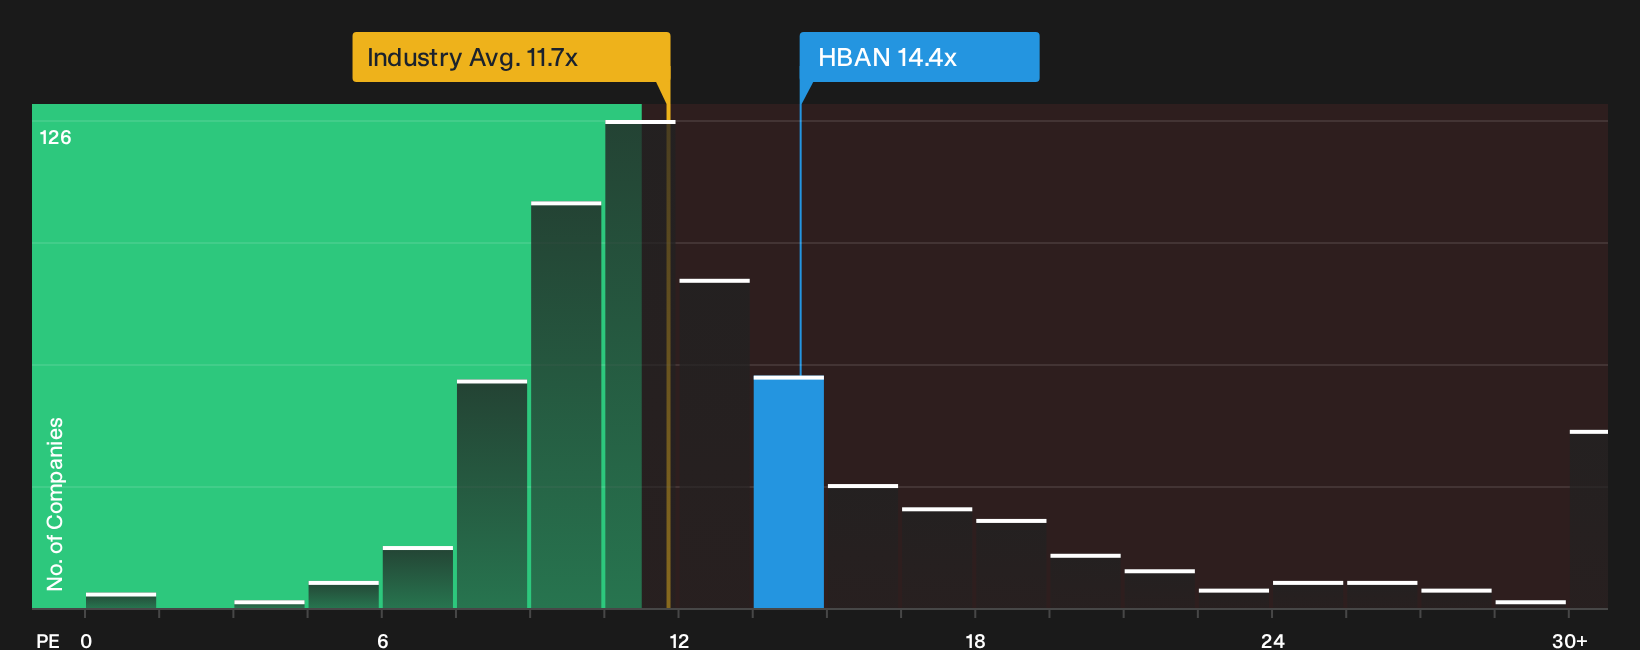
The SWS DCF model points to Huntington Bancshares trading well below an estimated fair value, yet the P/E picture tells a different story. HBAN changes hands at 14.4x earnings, richer than both the US Banks industry at 11.7x and peer average at 12.3x, while the fair ratio sits higher again at 18.1x. That mix of discount on cash flows but premium on earnings raises a simple question for investors: Which signal should carry more weight in your own work?
See what the numbers say about this price in the full valuation breakdown by heading to See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Huntington Bancshares so far. If you want to move quickly and build your own view from the ground up, start by weighing its 5 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Huntington Bancshares?
You have a clearer read on Huntington Bancshares now, so do not miss the chance to line up fresh ideas before the next move catches you off guard.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that filters for financial strength first.
- Hunt for quality at a discount by reviewing a focused 30 high quality undervalued stocks that screens for companies combining solid cash flows with compelling prices.
- Build your income playbook by checking a hand picked 7 dividend fortresses aimed at shares offering higher yields with stability in mind.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com