
Is Return To Profit Altering The Investment Case For DIA Stock?
- Distribuidora Internacional de Alimentación has shifted from losses to profit, supported by strong earnings growth over the past year and the last five years, with forecasts indicating further profit and revenue expansion.
- The supermarket group now trades on a higher P/E ratio than peers. This highlights that investors are weighing improved profitability against risks from one off items and interest costs.
- We will look at how Distribuidora Internacional de Alimentación's investment narrative is being reshaped by its return to profitability and improving earnings.
Compare Distribuidora Internacional de Alimentación's profit turnaround with curated opportunities showing similar momentum in our 616 high quality undiscovered gems.
What Is Distribuidora Internacional de Alimentación's Investment Narrative?
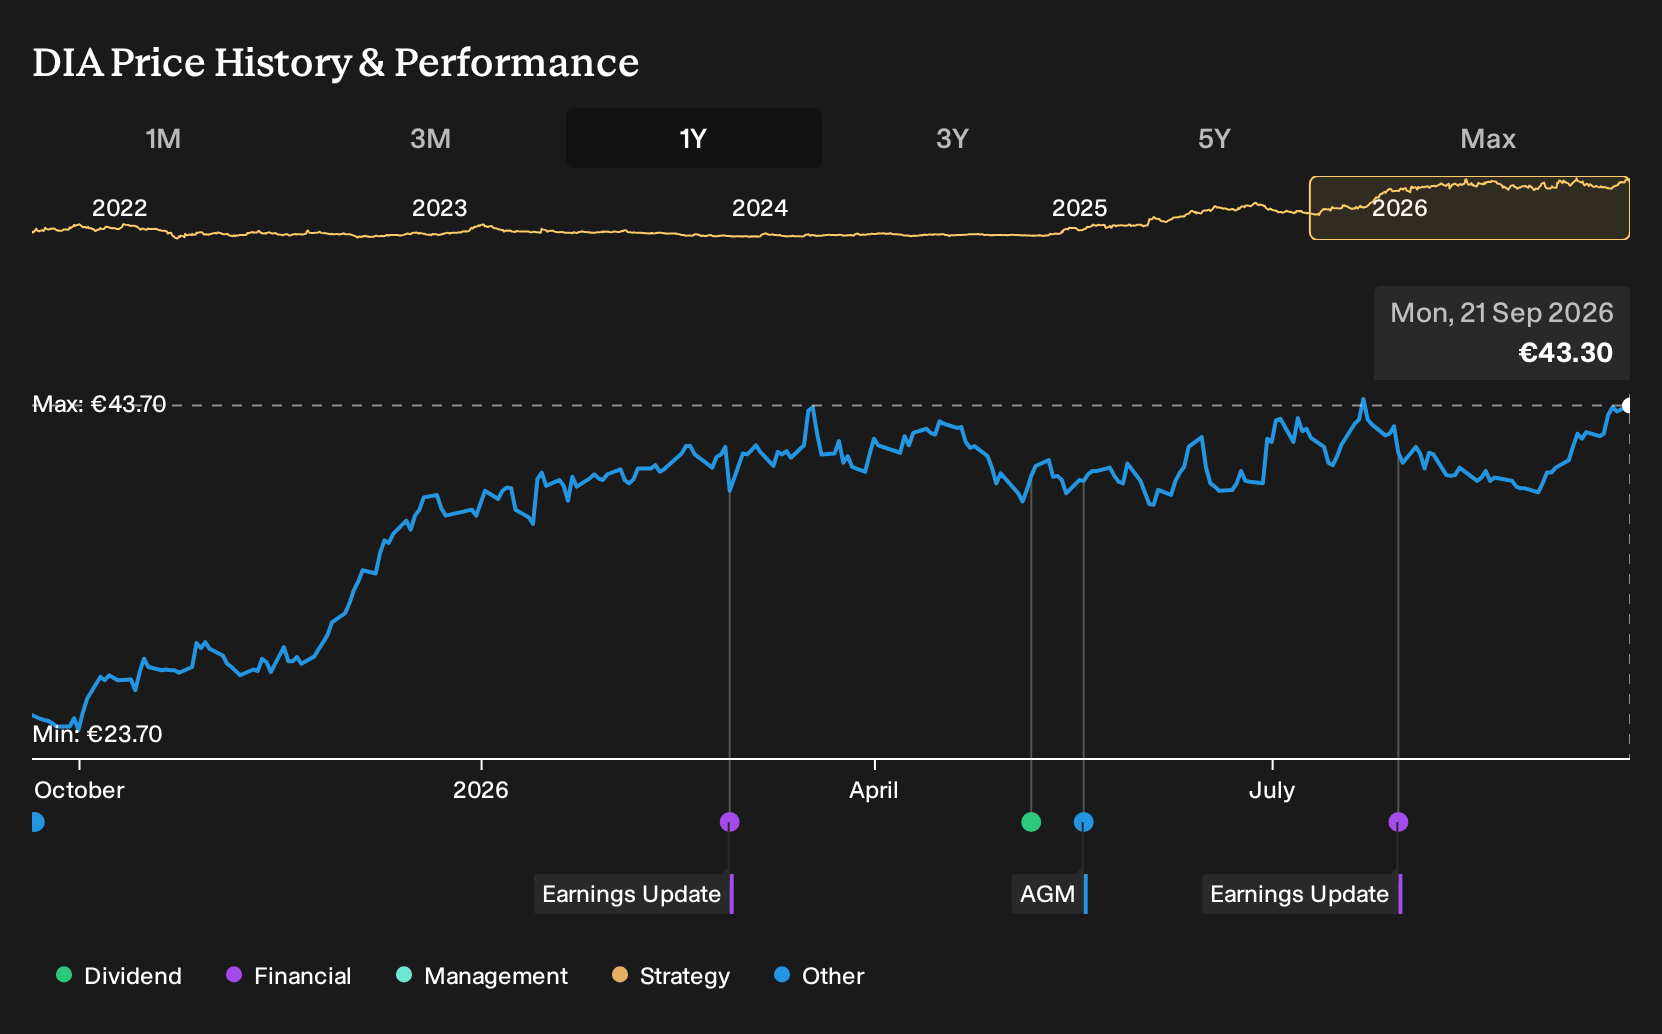
To own Distribuidora Internacional de Alimentación, you have to buy into a fairly simple idea. The chain needs to keep turning solid store level execution and tight cost control into consistent earnings, while managing a capital intensive store network in Spain and Argentina. The recent 11.17% 30 day and 13.50% year to date share price gains suggest investors are reacting to the shift back into profit and the 102.2% earnings growth over the past year, rather than any clear new operational catalyst.
In the short term, the key question is whether that profitability is repeatable once large one off items and interest costs are stripped out. DIA now trades on a P/E of 22.6x versus a peer average of 14.4x. This suggests the market already prices in cleaner earnings and forecasts of profit growth of 15.09% per year and revenue growth of 4.8% per year. Interest payments are not well covered by earnings, and with 100% of liabilities funded through higher risk borrowing, any stumble in execution or pricing power could matter quickly.
Even so, there is a quieter piece of the DIA story that could matter more than the recent rally if ...
There's only one way to know the right time to buy, sell or hold Distribuidora Internacional de Alimentación. Head to Simply Wall St's company report for the latest analysis of Distribuidora Internacional de Alimentación's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly €49.78 to €246.82, so retail opinions on Distribuidora Internacional de Alimentación already cover a wide gap. Those estimates were set before the recent share price rally. This gives you a reason to revisit assumptions and compare several sharply different viewpoints.
Explore another Distribuidora Internacional de Alimentación fair value estimate, including one that suggests it could be worth just €49.78.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Distribuidora Internacional de Alimentación research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Distribuidora Internacional de Alimentación. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Distribuidora Internacional de Alimentación's overall financial health at a glance.
Looking For More Investment Ideas Beyond Distribuidora Internacional de Alimentación?
Once you have formed a view on Distribuidora Internacional de Alimentación, it can help to widen the lens and compare it with other businesses that share some of the qualities you care about most. The Simply Wall St Screener lets you filter for factors like value, balance sheet strength, dividends, or risk profile so you can quickly surface a shortlist that fits your own approach.
- If you are hunting for quality at a reasonable entry point, check out companies screened as 178 high quality undervalued stocks that may align with a value focused watchlist.
- For investors who care most about financial resilience, the list of solid balance sheet and fundamentals (198 results) can help you focus on businesses with stronger foundations.
- If steady income is high on your priority list, the 161 dividend fortresses could point you toward potential yield ideas to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com