
The Case for Buying Netflix Stock
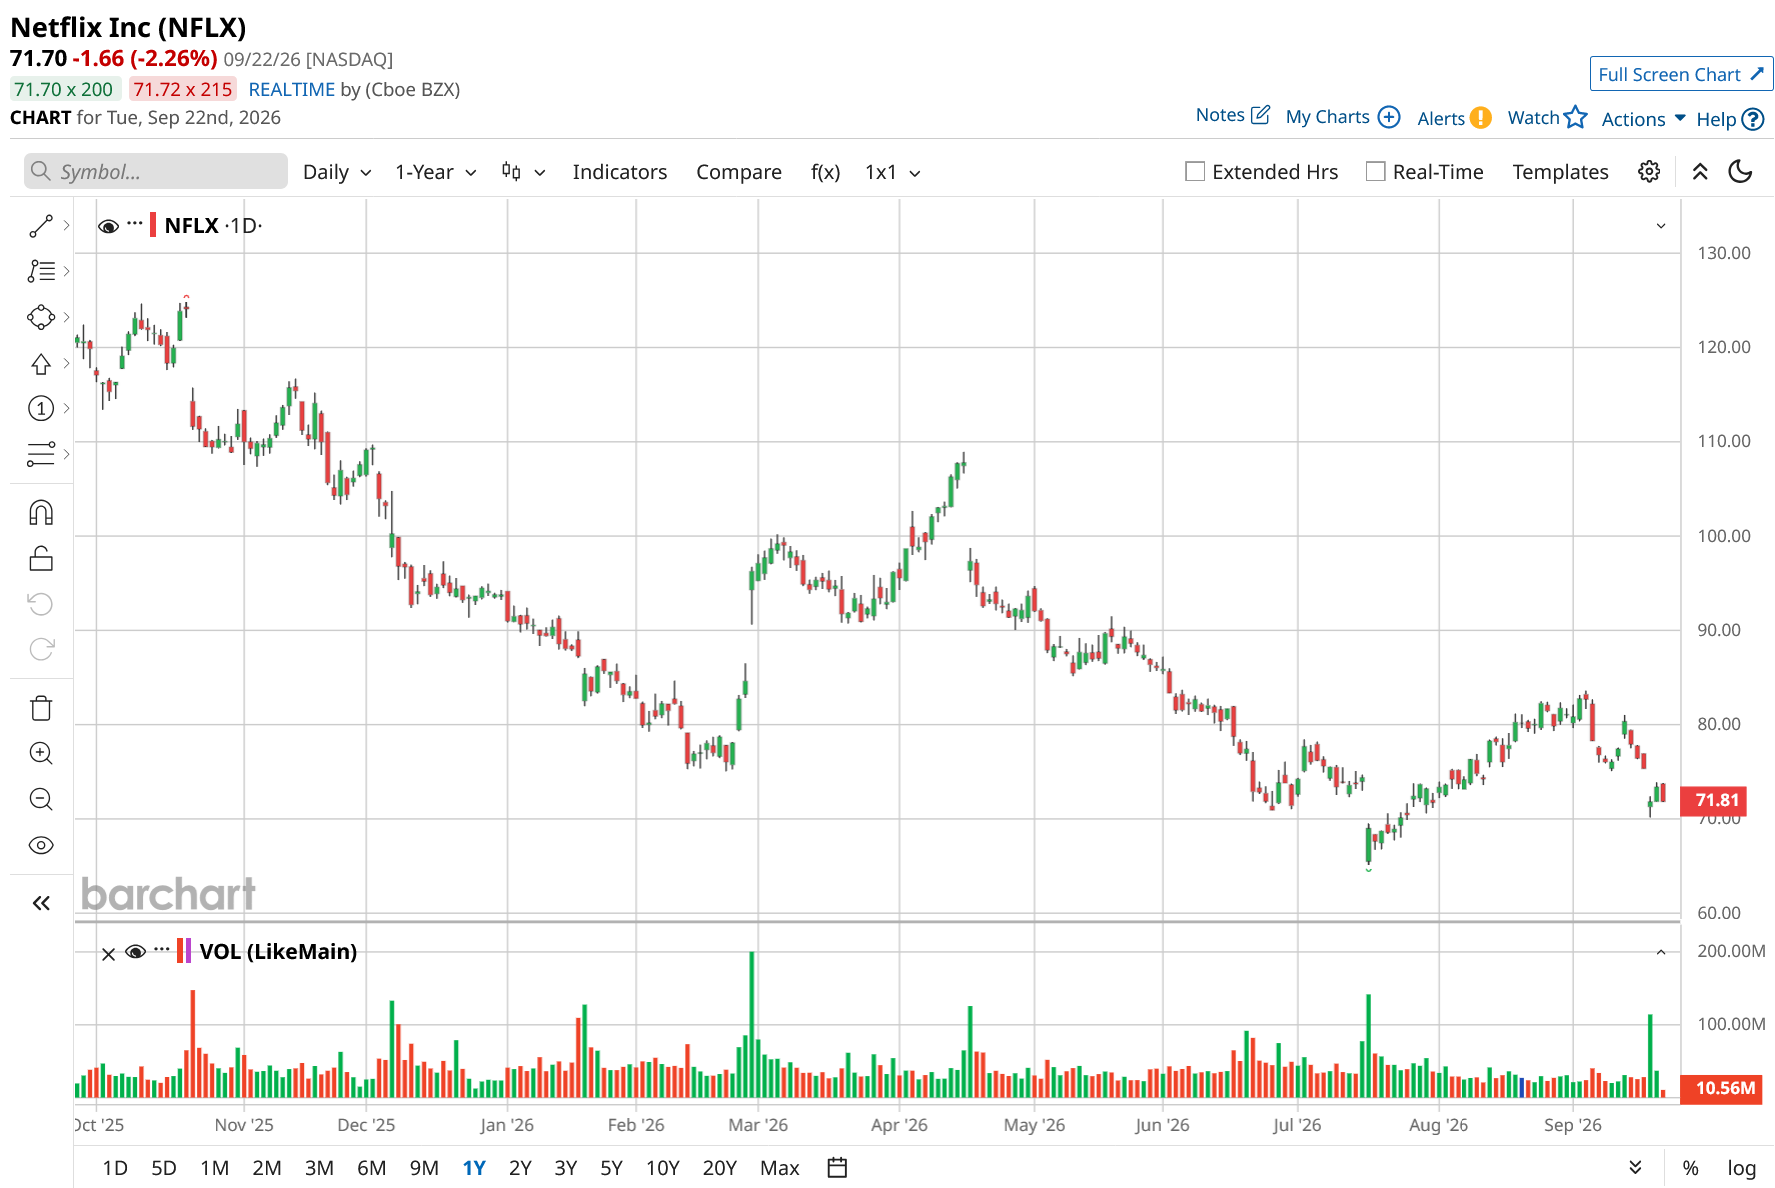
Netflix (NFLX) stock has faced considerable pressure so far this year. Shares are down about 23% year-to-date (YTD) and are currently trading around 42% below their 52-week peak. One of the primary issues weighing on investor sentiment is concern about the streaming giant’s engagement trends.
Concerns about declining viewership for second seasons of Netflix series raised questions about the platform’s ability to sustain engagement growth, especially amid heightened competition. At the same time, concerns about the strength and consistency of Netflix’s upcoming original-content lineup have contributed to expectations that engagement could soften further.
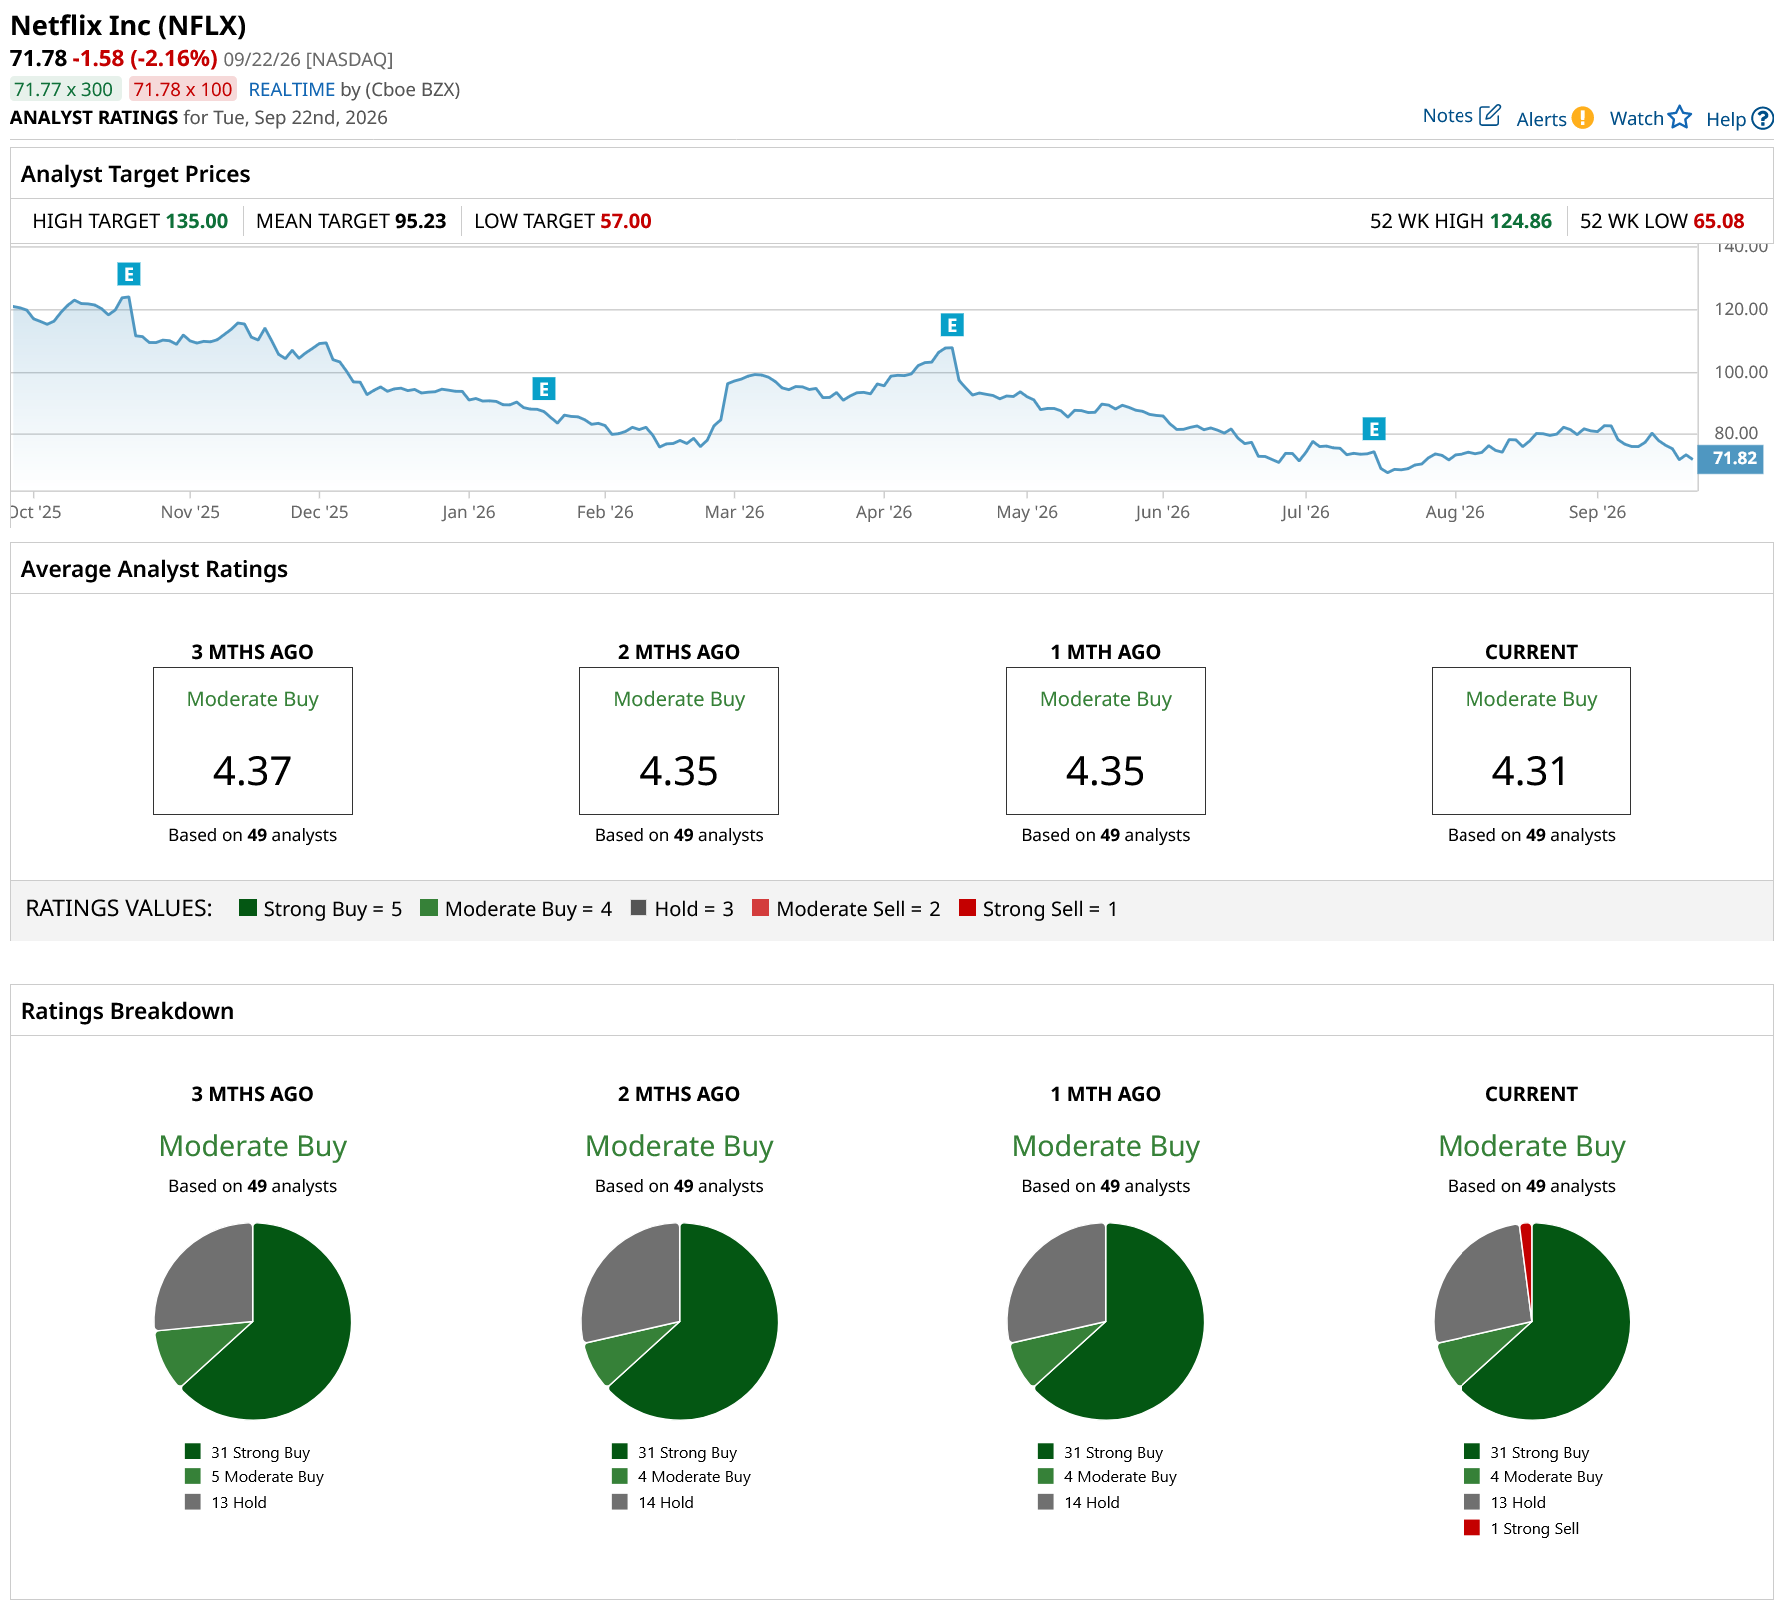
Adding to the negative sentiment, a Wells Fargo analyst recently downgraded Netflix stock to a “Sell.” The downgrade was based largely on expectations that the company could experience a slowdown in engagement growth.
Netflix Addresses Engagement Concerns
Concerns over Netflix’s engagement levels have raised questions about whether slower growth in viewing hours could affect the company’s financial performance. However, management argues that viewing hours should not be treated as a direct proxy for revenue or profitability because different content generates different levels of economic value.
Live programming illustrates this distinction. Although live events are expected to account for only around 5% of Netflix’s 2026 content expenditure and approximately 1% of viewing hours, their strategic contribution extends beyond consumption. Management highlighted their ability to attract new subscribers and support monetization and advertising. This suggests that relatively low viewing volume can still translate into significant commercial value.
The available viewing data also provides some evidence that engagement itself has not deteriorated materially. During the first half of 2026, Netflix reported a 2% increase in viewing hours, equivalent to roughly 1.5 billion additional hours compared with the corresponding period in 2025. This represented a modest acceleration from the 1.5% growth recorded in 2025. This suggests that the platform continues to expand consumption rather than experiencing an outright contraction in viewing activity.
Management has also indicated no material weakening in second-season viewing, with returning seasons continuing to perform broadly within expected ranges. This matters because sustained consumption across subsequent seasons can indicate continued audience interest and Netflix’s content portfolio's ability to retain viewers over time.
Netflix’s broader argument is that engagement should ultimately be assessed through its impact on subscriber acquisition, retention, and advertising demand, rather than through viewing volume alone.
Why Consider Netflix Stock Now?
Amid engagement concerns, Netflix's management offered lower-than-expected Q3 revenue guidance. Its top line is projected to increase 11.7% year-over-year (YoY) in Q3, below analysts’ expectations. The company also faces tougher YoY comparisons in the second half of the year, which could place additional pressure on reported growth rates.
While the near-term growth trajectory is under pressure, the significant pullback suggests the negatives are already priced in. Further, Netflix’s fundamentals remain solid, with its top and bottom lines set to grow.
Netflix expects 2026 revenue of approximately $51 billion to $51.4 billion, implying growth of 13%–14%. Subscriber additions and pricing remain the core drivers, while advertising represents an increasingly important opportunity. Management expects advertising revenue to reach approximately $3 billion in 2026, broadening monetization beyond subscriptions.
Profitability also remains a key strength. Netflix expects content costs to rise by about 10% in 2026, below its projected revenue growth rate. This dynamic could support continued margin expansion and earnings growth. At the same time, Netflix’s focus on high-quality content should help drive engagement and retention and support its pricing power.
What Analysts Are Saying About NFLX Stock
Analysts remain cautiously optimistic, with a “Moderate Buy” consensus rating on NFLX stock. However, the company's valuation supports its investment case. NFLX currently trades at about 20 times forward earnings, a level below the premium valuation multiples the stock has historically commanded.
Overall, Netflix’s near-term growth faces headwinds, but its ability to deliver double-digit revenue growth, strong margins, expanding advertising monetization, and a reasonable valuation provide a constructive long-term investment case.
On the date of publication, Amit Singh did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.