
How Index Inclusion Will Impact Liberty Global Stock Investors
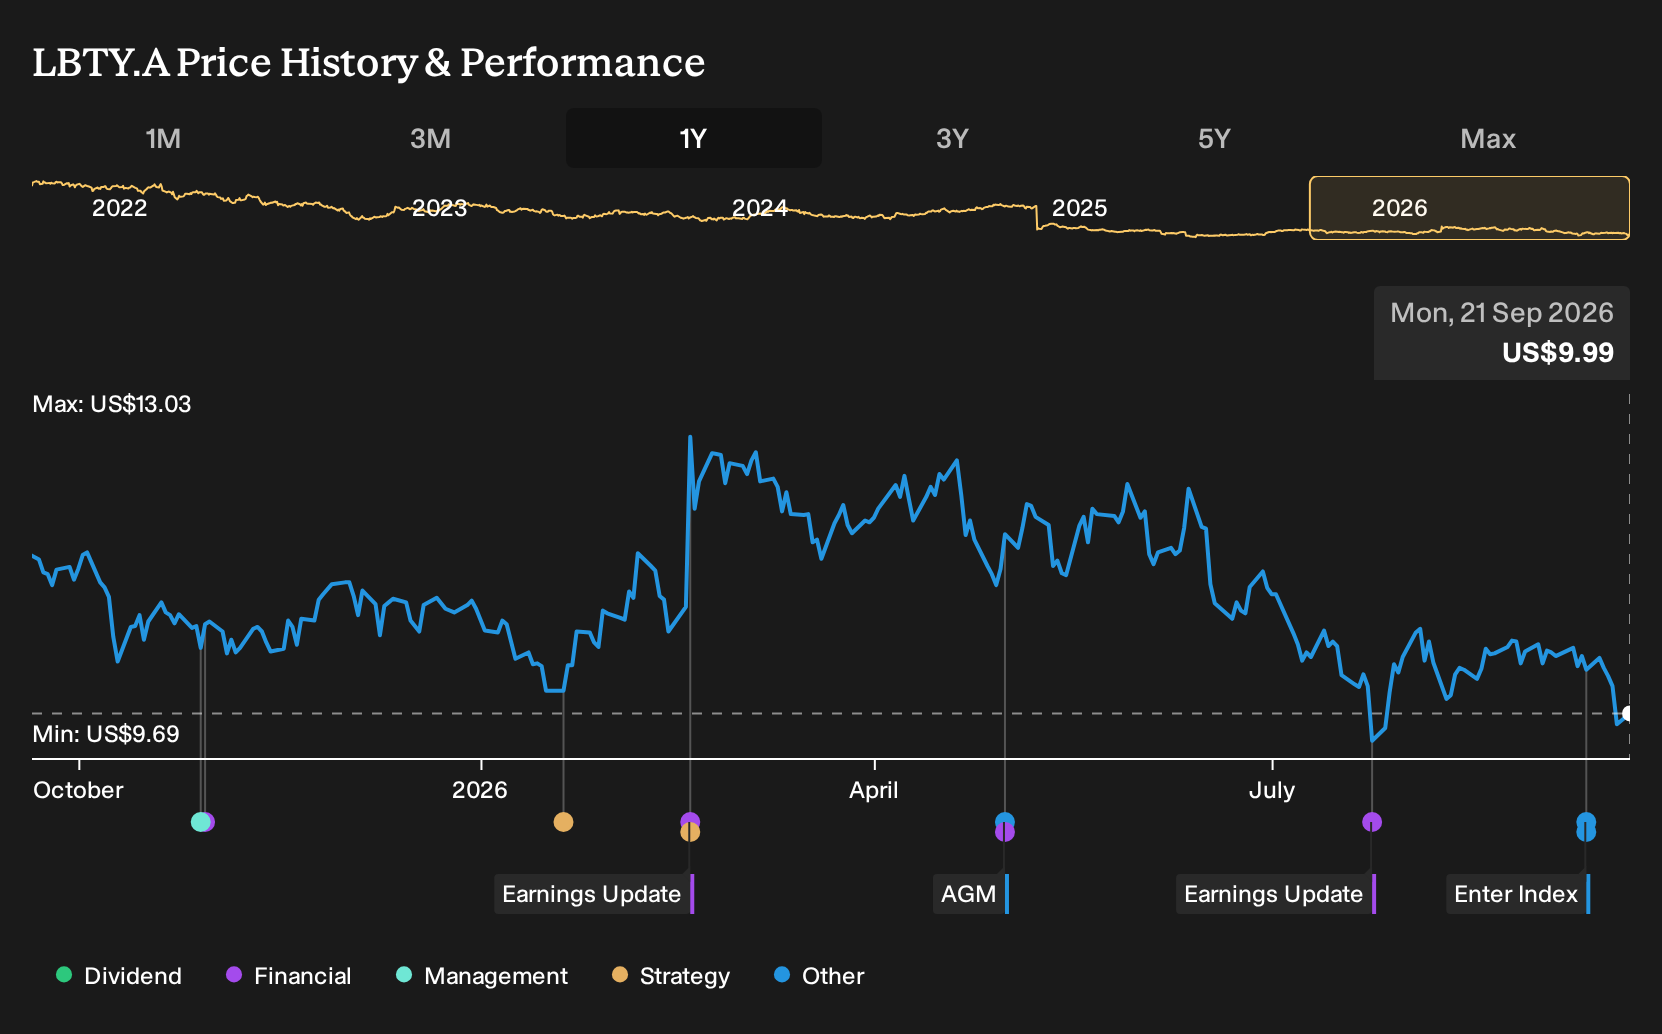
- Liberty Global reported that its LBTY.A class of shares was added to the S&P Telecom Select Industry Index in September 2026, while the LBTY.K class was removed, shifting how index-tracking funds may gain exposure to the business.
- This reshuffle concentrates benchmark-linked flows into LBTY.A, which may influence liquidity and capital market access at a time when Liberty Global is pursuing network upgrades, asset optimization, and corporate simplification.
- We will examine how Liberty Global's investment narrative is affected by LBTY.A joining the S&P Telecom Select Industry Index.
Scan how Liberty Global's index reshuffle compares with other telecom plays with resilient balance sheets by reviewing our hand picked list of solid balance sheet and fundamentals (23 results).
Liberty Global Investment Narrative Recap
To own Liberty Global, you need to be comfortable with a turnaround story in a mature European telecom market. The core belief is that heavy investment in gigabit broadband, fiber and fixed mobile bundles can eventually stabilize revenue and move the group closer to breakeven, even while headline revenue is currently drifting lower and losses remain large.
The index switch into LBTY.A does not change that central thesis. It mostly affects which share class index trackers hold. The nearer-term swing factor still sits in execution on network upgrades, cost cuts and asset optimization. The biggest risk remains high leverage on unprofitable operations in markets facing tough competition and regulatory oversight.
With no fresh operating announcements tied directly to the index reshuffle, the most relevant context is Liberty Global’s existing focus on asset monetization and digital efficiency programs. Management has outlined plans to refine the portfolio, use tower and fiber transactions to recycle capital and push corporate simplification to reduce overhead and complexity.
For you as a shareholder, the main catalyst to watch is whether these moves translate into steadier free cash flow and a path toward smaller losses, given that analysts currently expect the group to stay in the red over the next three years. Any stumble on network investment, refinancing or asset sales would quickly re-amplify concerns around debt, which already leans heavily on higher-risk borrowing.
Liberty Global's narrative projects US$4.4b revenue and US$390.2m earnings by 2029. This assumes revenue declines by 3.3% per year and implies an earnings swing of about US$3.4b from earnings today of a US$3.0b loss.
Uncover why Liberty Global's fair value indicates a 46% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the index switch as potentially reinforcing a very different catalyst for Liberty Global. They were already modeling revenue of about US$5.2b and earnings of roughly US$548.0m by 2029. You can treat those pre news forecasts as one end of the spectrum and stress test your own view against them.
Explore another Liberty Global fair value estimate, including one that suggests as much as 277% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Liberty Global research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Liberty Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Liberty Global's overall financial health at a glance.
Looking for more Liberty Global style investment ideas?
If Liberty Global has you thinking about where else disciplined balance sheets and clear stories might exist, the Simply Wall St Screener can help you scan the market quickly and focus on the kind of profiles that fit your approach.
- If capital preservation is high on your list, review a set of companies screened for resilience and lower risk profiles through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, broaden your watchlist by checking out the 30 high quality undervalued stocks that combine solid fundamentals with attractive pricing.
- If you prefer businesses with healthier finances, start your wider search with a curated list of solid balance sheet and fundamentals (23 results) that can complement or contrast your view on Liberty Global.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com