
CenterPoint Energy (CNP) Replaces Its Credit Facility, Is The Stock Still Cheap?
Why CenterPoint Energy’s New Credit Facility Matters
CenterPoint Energy (CNP) has replaced its prior US$2.4b unsecured revolving credit line with a new US$2.2b five-year senior unsecured facility, reshaping its access to short term funding and bank liquidity.
For investors tracking CenterPoint Energy, the new credit facility comes after a softer period for the share price, which is down 12.67% over 90 days and 2.01% over 30 days. However, the 5 year total shareholder return of 69.55% highlights stronger performance over a longer horizon.
Compare CenterPoint Energy’s funding shift with other utilities that are adjusting their balance sheets by scanning our curated list of list of solid balance sheet and fundamentals (23 results).
Bulls see CenterPoint Energy using this fresh credit line to reinforce a steadier utility model, while bears focus on leverage limits and recent share softness. Which side does the current valuation actually support next?
Most Popular Narrative: 16% Undervalued
On the most followed narrative, CenterPoint Energy’s fair value sits at $45.35 against a last close of $37.99, which frames the new credit facility against a valuation that still assumes a higher future earnings base.
CenterPoint Energy expects to grow non-GAAP EPS at the mid to high end of a 7% to 9% range annually through 2028 and through 2035, which ties long dated earnings growth directly to its US$66.7b capital investment plan and large-load expansion and therefore to future revenue and earnings.
See why 5 investors see CenterPoint Energy as 16% undervalued.
Result: Fair Value of $45.35 (UNDERVALUED)
Still, the CenterPoint Energy story can break if the premium P/E multiple compresses, or if funding the US$66.7b capex and US$1b equity program dilutes shareholder returns.
Find out about the key risks to this CenterPoint Energy narrative.
Another View: CenterPoint Energy Through Its P/E
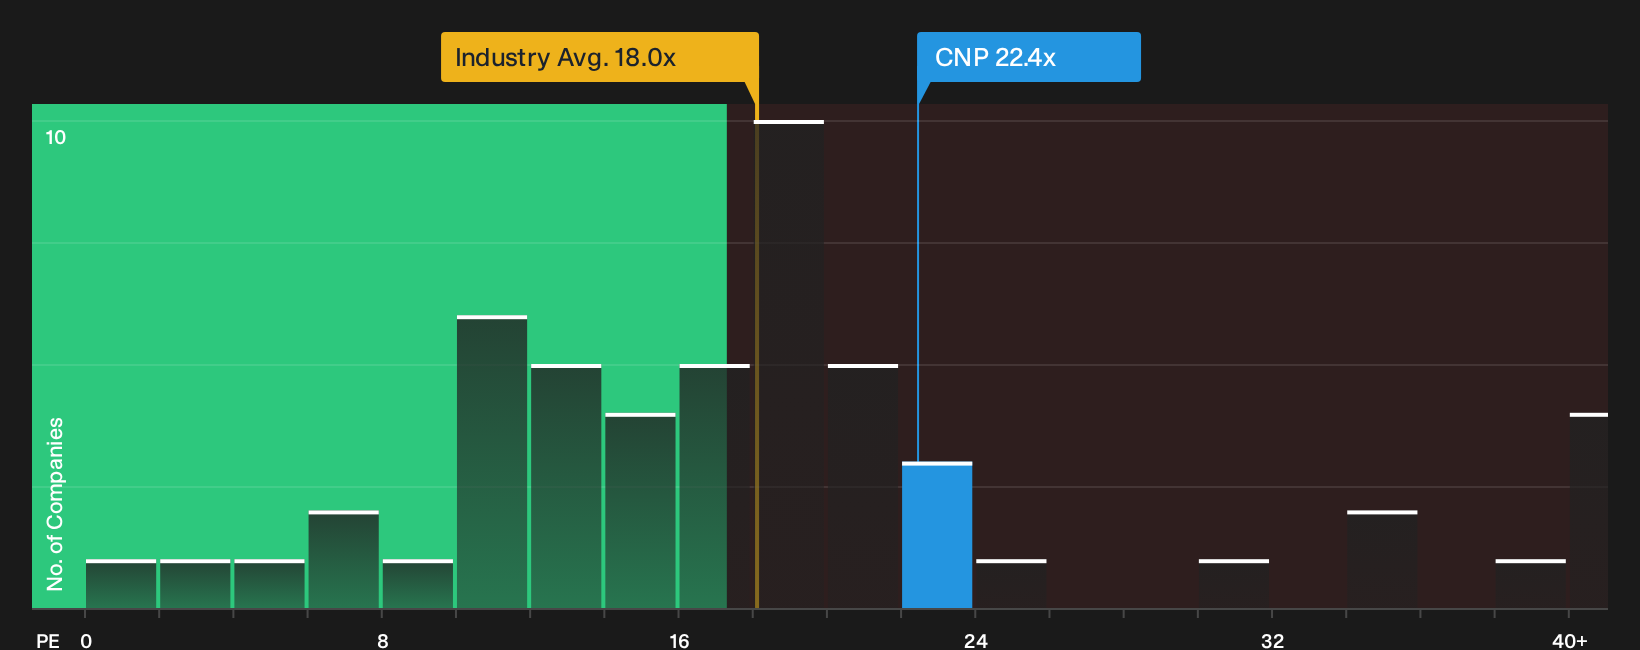
There is a different read on CenterPoint Energy when looking at the P/E ratio. The stock trades on 22.4x earnings compared with 18x for the global Integrated Utilities group and a fair ratio of 22.2x, which points to limited valuation cushion if sentiment cools.
Investors who focus on this pricing lens can pressure test whether that extra premium feels justified or stretched by digging into the detailed valuation work behind these numbers, including the See what the numbers say about this price — find out in our valuation breakdown..
Visualizing how CenterPoint Energy’s valuation stacks up against its sector can also help you judge how much room there is for that P/E premium to move, as shown in the latest comparison chart for
Next Steps
Mixed about whether CenterPoint Energy’s valuation really balances its long term plans with current risks and rewards. Move quickly and test the thesis against the full picture by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CenterPoint Energy?
If CenterPoint Energy has sharpened your thinking on risk, reward, and valuation, do not stop here. Use the screeners below to surface fresh opportunities with clear fundamentals.
- Target stronger downside protection by focusing on companies that score well for resilience and financial stability through the 30 resilient stocks with low risk scores.
- Hunt for mispriced quality by filtering for businesses that combine healthy balance sheets with attractive valuations using the 30 high quality undervalued stocks.
- Zero in on underfollowed opportunities by scanning a curated 17 high quality undiscovered gems before the wider market starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com