
AeroVironment (AVAV) Could Be 55% Above Fair Value Following Its $50 Million LOCUST Win
AeroVironment (AVAV) just secured its first international purchase order for the LOCUST Laser Weapon System, a deal worth more than US$50 million. This agreement highlights growing interest in its directed energy counter drone technology.
Recent trading has been mixed for AeroVironment, with the share price up 7.9% over the past 90 days but down 37.2% on a year to date share price return. The 1-year total shareholder return has declined 44.2%, while the 3-year and 5-year total shareholder returns of 43.6% and 86.6% point to stronger longer term momentum. This LOCUST contract and recent guidance reaffirmation could influence performance further as investors reassess growth potential and risk around the defense pipeline.
Scan other defense and robotics stocks with similar contract momentum by reviewing our curated list of 95 robotics and automation stocks alongside AeroVironment’s latest LOCUST win.
AeroVironment now has contracts, guidance and a high profile defense niche all pointing in the same direction. The real tension is whether that story is already fully baked into today’s US$160.90 share price.
Most Popular Narrative: 55% Overvalued
AeroVironment’s most followed narrative pegs fair value at $103.94, well below the recent $160.90 close. This frames today’s price as rich according to LunaRodas.
The previous framework positioned international adoption as a downstream consequence of U.S. Army endorsement, with allied customers waiting for the U.S. military validation signal before moving. The current call confirms that theory played out at speed: Nawabi told the Bank of America analyst that the international customer “was more waiting for the U.S. Army to select on EHEL,” and that the U.S. Army win combined with a live demonstration against competing systems produced the award. The causal chain described earlier worked in sequence, in the same quarter.
See why 3 investors see AeroVironment as 55% overvalued.
Result: Fair Value of $103.94 (OVERVALUED)
Still, the AeroVironment story can break if the goodwill and controls issues linger or if key programs like MAYHEM 10 and AV_Halo quietly lose priority.
Find out about the key risks to this AeroVironment narrative.
Another View On AeroVironment’s Valuation
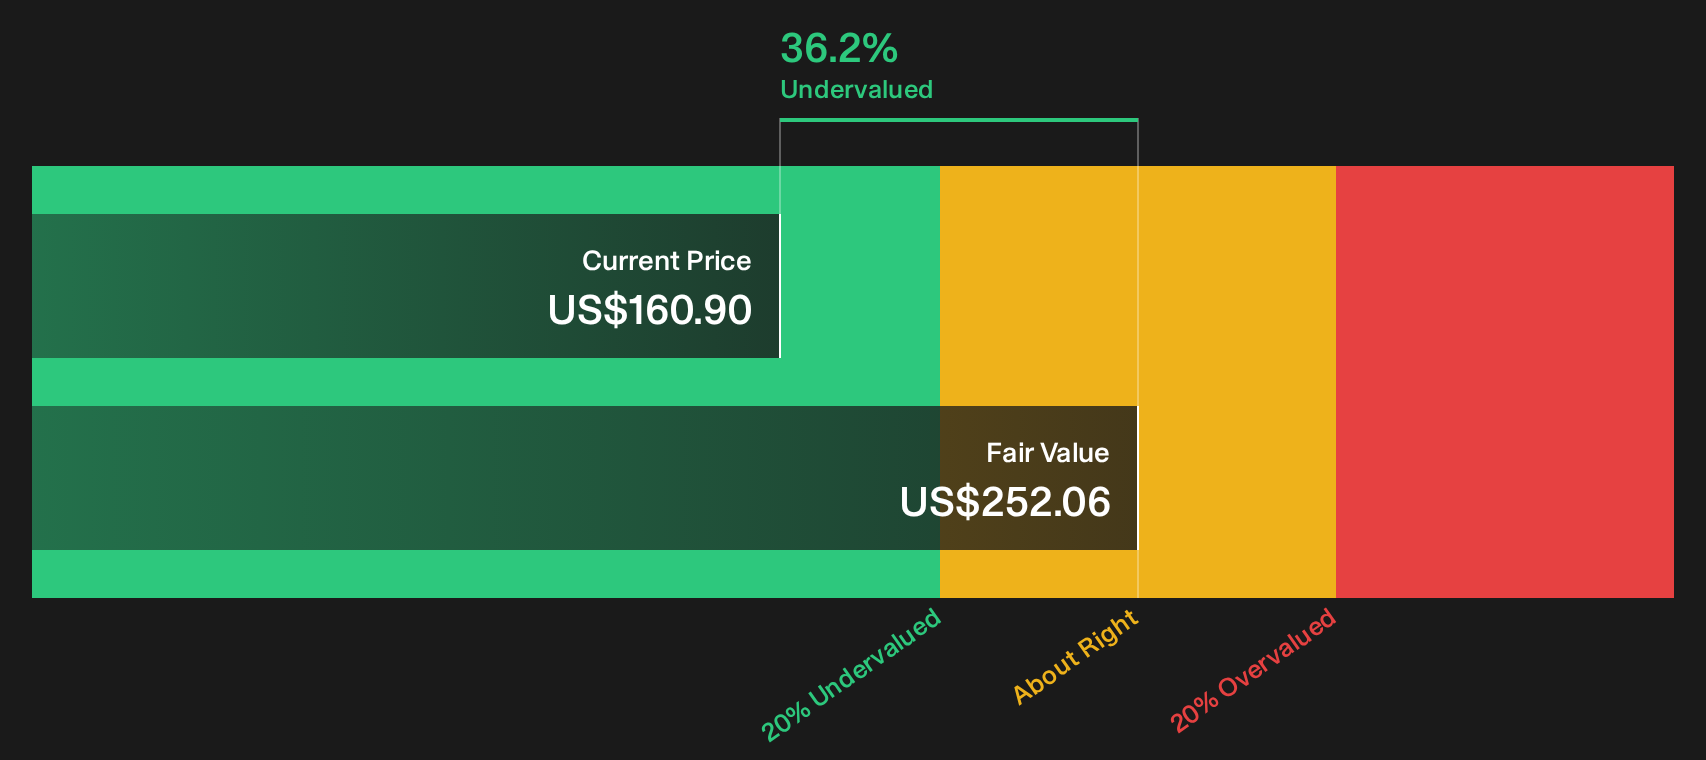
The narrative from LunaRodas pegs AeroVironment’s fair value at $103.94, which paints the current $160.90 price as rich. The SWS DCF model points in the opposite direction. It values the stock at $252.06, suggesting the market could be underpricing future cash flows.
If those cash flow assumptions hold, the gap between $160.90 and $252.06 looks less like froth and more like a question about how durable this contract pipeline really is. Look into how the SWS DCF model arrives at its fair value.
Next Steps
If AeroVironment’s mixed signals leave you torn, that is exactly the point; both risk and upside are on the table. Pressure test the story yourself with 2 key rewards and 1 important warning sign.
Looking for more AeroVironment investment ideas?
If AeroVironment’s story has you thinking harder about risk, cash flow and staying power, use the Simply Wall Street Screener to surface fresh opportunities before others do.
- Target resilient payers by zeroing in on reliable income opportunities through the 7 dividend fortresses that can complement a growth name like AeroVironment.
- Hunt for quality at a discount by scanning the 30 high quality undervalued stocks that combine strong fundamentals with pricing that still looks reasonable.
- Spot sturdy balance sheets early by reviewing the list of solid balance sheet and fundamentals (23 results) so potential weak links do not quietly erode your long term returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com