
Havas (ENXTAM:HAVAS) Stock Still Looks Reasonable On Earnings Value
Havas has delivered a 20.2% gain over the past year, which naturally pushes investors to ask whether that move is backed up by the advertising group’s earnings power or mainly by sentiment. With the shares recently closing at €18.0, the key issue now is how much of the business’s profit story is already built into that price.
- The 20.2% return over the last 12 months puts real weight on the question of whether Havas stock is now closely aligned with what its earnings can justify.
- The group’s valuation heavily depends on how consistently it can convert its media and creative revenues into stable profits and cash flows, since that earnings base shapes what investors may reasonably be willing to pay.
- There is a second opinion on Havas worth weighing. See what analysts think Havas's shares could be worth.
For investors, the debate is whether Havas earnings support the current €18.0 share price when judged against the Fair Ratio benchmark.
If you are weighing whether Havas at €18.0 fully reflects its earnings, it can help to compare ideas side by side using a focused stock list such as 178 high quality undervalued stocks
Is Havas Still Cheap on Earnings?
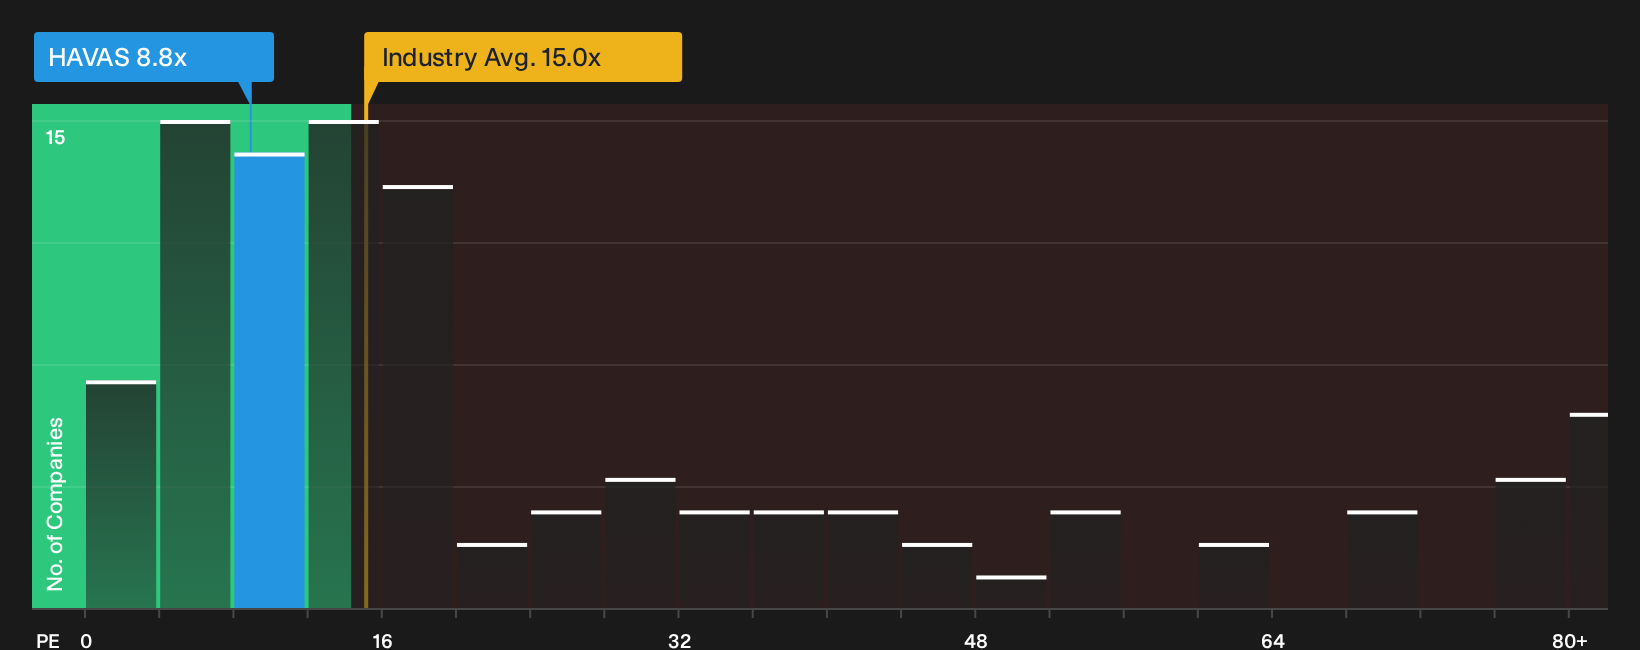
The P/E ratio works well for Havas because earnings remain the main anchor for how this media group is priced. On this measure, the stock trades on a P/E of 8.8x, which is well below the broader media industry average of about 15.0x and also far under the peer group level of 52.0x.
Fair Ratio analysis, which adjusts the benchmark P/E for Havas based on its own mix of growth profile, profit margins, scale and risk, points to a higher multiple than where the shares currently change hands. That gap suggests the market price is undervalued on this earnings yardstick, so any investor weighing the €18.0 share price against the profit base will want to judge whether that discount reflects real business risks or simply cautious sentiment. Explore the numbers behind Havas's P/E valuation.
The Havas Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Havas build on this valuation puzzle by spelling out which future paths for growth, margins and earnings would need to play out for the shares to be worth meaningfully more or less than €18.0, and they sit on the stock’s Community page. Each narrative links its number to a clear view on how Havas' prospects and risks could evolve, which you can revisit as fresh information comes through.
A clear, number-driven narrative on Havas now helps you pin down what earnings, margins and cash generation would need to look like for the current P/E gap to make sense. It turns vague expectations into explicit assumptions that can be checked against how Havas' actual results and valuation develop over time.
Share your own Narrative for Havas and set out the assumptions behind your valuation.
One more Havas angle worth checking before you move on
There is a whole extra layer to Havas that sits outside today’s share price and current P/E. This reflects what professional analysts expect this business to look like a few years from now. Explore where analysts expect Havas to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com