
Is Bank of China (SEHK:3988) Fairly Valued Or Still Undervalued After Its Recent Rally?
Bank of China (SEHK:3988) has drawn fresh attention after recent price moves, with the share price closing at HK$6.02. Investors are weighing solid profitability metrics against a valuation that screens as materially discounted.
The recent pullback of 0.66% on the day sits against a stronger run, with a 30-day share price return of 9.36% and a year-to-date share price gain of 32.89% suggesting momentum has been building. A 1-year total shareholder return of 48.40% and 5-year total shareholder return of 218.40% indicate longer term holders in Bank of China have seen materially higher overall rewards than short term traders.
Scan beyond Bank of China and compare this rally with a hand picked set of quality value opportunities in our 178 high quality undervalued stocks.
Bank of China now screens at a steep implied discount to intrinsic value, yet trades only modestly below analyst targets. After such a strong run, is the market applying healthy caution or mispricing the risk altogether?
Most Popular Narrative: 6% Overvalued
According to the most followed narrative on Bank of China, the shares at HK$6.02 sit slightly above a fair value estimate of HK$5.69 when using a discount rate of 8.23%, which frames the recent rally as leaving only a small valuation gap.
Bank of China Limited (“BOC”) is one of China’s “Big Four” state-owned commercial banks, with a leading position in global banking services and cross-border finance.
The investment thesis centers on:
• Strong sovereign backing
• Global footprint
• Diversified revenue mix
See why 5 investors see Bank of China as 6% overvalued.
Result: Fair Value of HK$5.69 (OVERVALUED)
Still, pressure on asset quality from property exposure and any renewed weakness in Chinese credit demand could quickly challenge the current valuation story for Bank of China.
Find out about the key risks to this Bank of China narrative.
Another View: Bank of China Through Cash Flows
The narrative that Bank of China looks slightly overvalued at HK$6.02 is not the only lens available. A separate assessment using our DCF model points to a future cash flow value of HK$12.28, meaning the share price screens as materially undervalued on this framework. Which signal should investors trust when the story appears to change so sharply between methods?
Look into how the SWS DCF model arrives at its fair value.
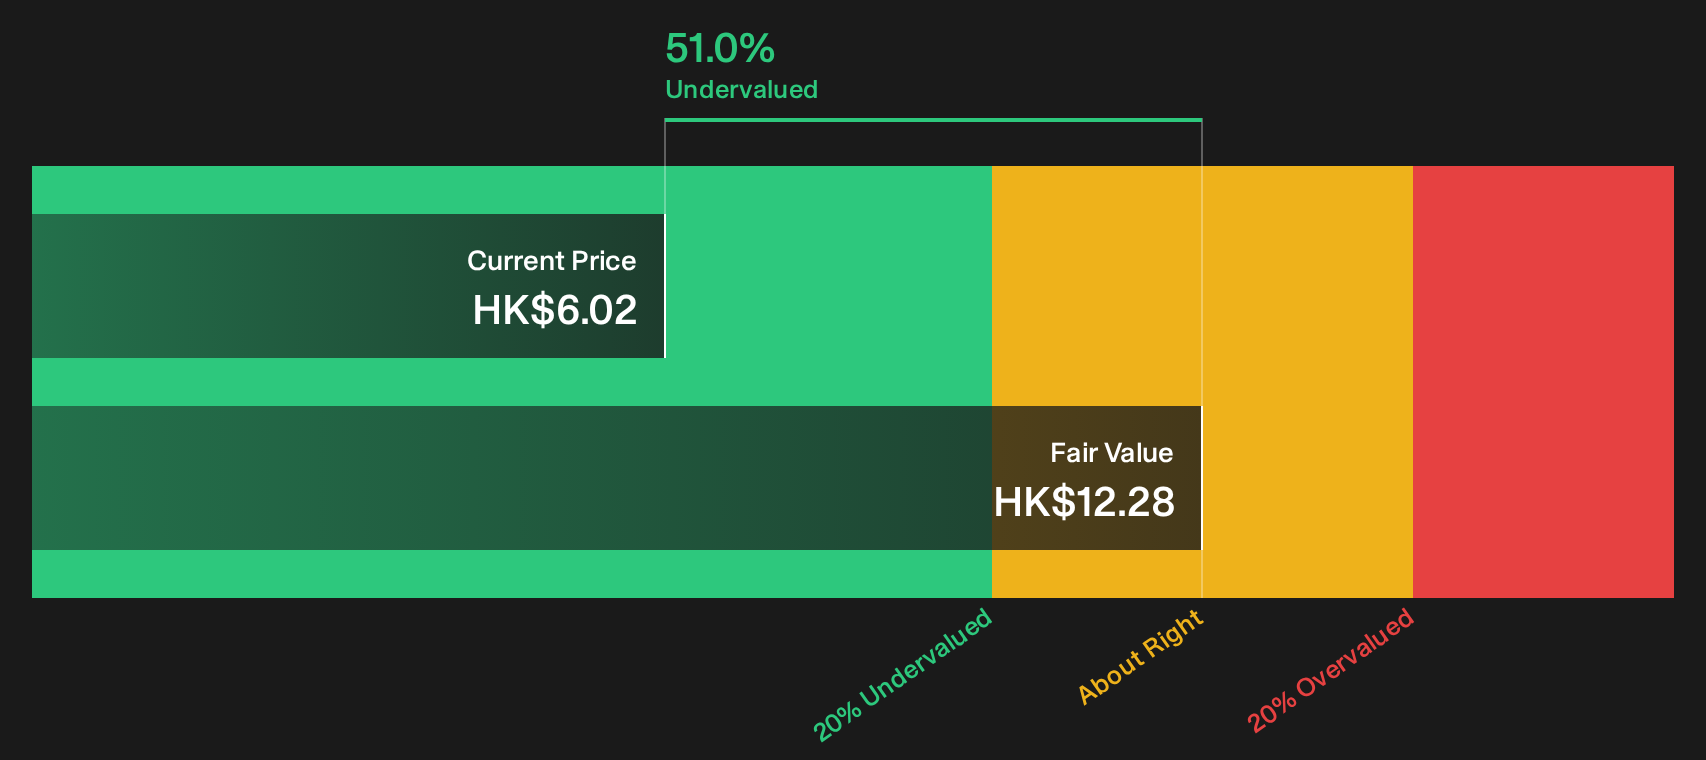
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bank of China for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 178 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Bank of China is split, with valuation signals pointing in different directions, so check the underlying numbers yourself and move promptly before views settle. To see what some investors already like about the business, review the 4 key rewards.
Looking for more Bank of China sized ideas?
If you want fresh momentum beyond Bank of China, now is the time to line up your next moves using focused stock lists built from hard data.
- Target stronger income potential by scanning companies that match the 161 dividend fortresses and see which payouts look most compelling for your income goals.
- Seek resilient capital by reviewing the 229 resilient stocks with low risk scores and compare businesses that score well on stability and downside protection.
- Hunt for future leaders early by checking the 616 high quality undiscovered gems before the crowd starts paying close attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com