
Grab Stock Is Worth the Risk as Valuations Fall to Historical Lows
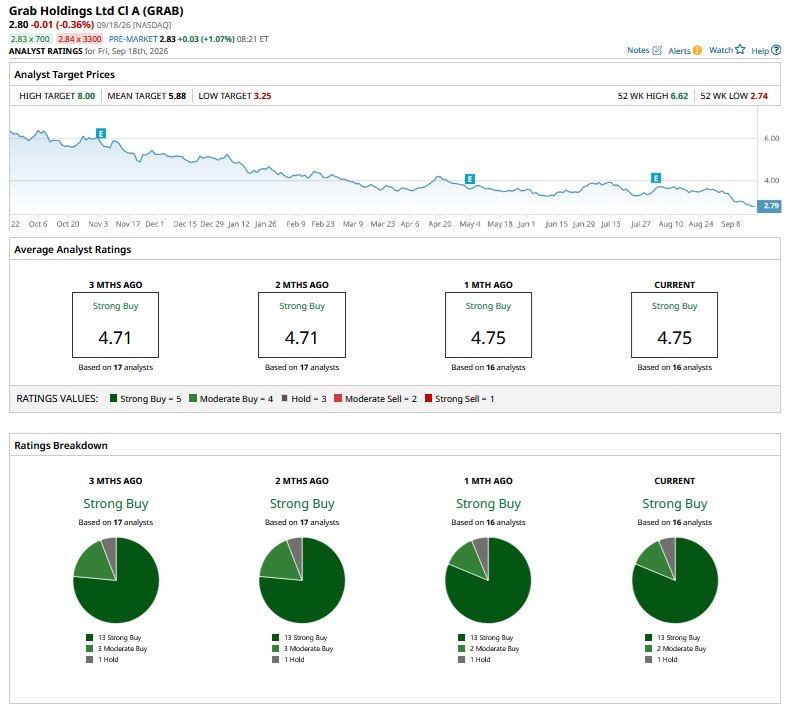
Grab Holdings (GRAB), the largest special purpose acquisition company (SPAC) merger ever, is having a dismal run this year. It fell to its 52-week lows on Friday, Sept. 18, and is down nearly 44% for the year. It is a penny stock even as the market cap is above $11 billion. Meanwhile, thanks to the sharp decline in GRAB stock, its valuation has plummeted, and it trades at a forward price-to-earnings (P/E) multiple of 21.50x with a P/E-to-growth (PEG) multiple of 0.73x.
The P/E is at a historical low and looks particularly attractive given the nearly 25% topline growth the company is expected to post this year. The earnings per share (EPS) estimates are even rosier, with consensus estimates calling for a 116% rise this year.
Sell-side analysts are quite upbeat on Grab, and of the 16 analysts covered by Barchart, only one rates it a “Hold” while the remaining rate it as either a “Strong Buy” or a “Moderate Buy.” The stock trades below its Street-low target price of $3.25, while the mean target price of $5.88 implies the stock can more than double over the next year.
Key Risks Grab Investors Should Watch Out For
While the headline valuation numbers suggest that Grab is a growth stock worth “grabbing,” it has been falling for a reason(s). Here are some risk factors weighing on Grab.
- Regulatory Risks: While nearly every company faces regulatory risks and these boilerplate challenges are omnipresent in annual reports, they are quite prominent in Grab’s case. The company operates a ride-hailing and delivery business in Southeast Asia, and like other companies in the business, it relies on the take rate, or the commissions that it charges on the passenger’s total fare. Indonesia has capped commissions for two-wheeled ride-hailing services from 20% to 8%. After protests by drivers, Vietnam is also reviewing the commissions that Grab charges and has asked the company for details on its fare-setting policies and commission rates. If more countries where Grab operates take a similar line, it would hurt Grab's earnings.
- Higher Oil Prices: Higher oil prices are another headwind for Grab. Not only are they impacting consumer spending, but specifically for ride-hailing companies, it is squeezing driver earnings, which in turn is leading to protests and calls for Grab to lower its commissions.
- Higher Competition: Higher competition, particularly from Sea Limited (SE), is another risk for Grab, and the company has had to offer higher incentives to lure customers. Consider this: in Q2 2026, it spent $706 million on driver and customer incentives. On-Demand incentives as a percentage of On-Demand gross merchandize value (GMV) rose to 10.9% in Q2, an increase of 72 basis points over the corresponding quarter last year.
- Rising Exposure to Lending Business: Grab has been growing its financial services segment, its fastest-growing but unprofitable business, through acquisitions. Earlier this year, it announced the acquisition of U.S.-based Stash, and now it has bought a 60% stake in buy now, pay later (BNPL) company Atome for $1.49 billion. The company also agreed to acquire the remaining stake after two years at a valuation between $2 billion and $4.5 billion. While Atome offers positive adjusted earnings before interest, tax, depreciation, and amortization (EBITDA), Grab seems to have overpaid in the deal considering the valuations of listed BNPL companies. There are concerns over Grab's increased exposure to the lending business and, by extension, consumer credit.
Grab Is a Growth Story
Meanwhile, the picture is not all that scary, and there are several opportunities for Grab, which is a proxy to play the Southeast Asian consumer economy where it is the biggest ride-hailing and super app company.
Financial services are the next growth frontier for Grab. So far, Grab's lending business was mostly concentrated with drivers and merchants on its platform, and only 1% of the 138 million annual transacting customers on its platforms borrowed from it. In terms of formal credit, Southeast Asia is underpenetrated, and only 14% of adults have ever borrowed from a financial institution or bank, per the data provided by Grab.
The company expects its financial services segment to become EBITDA positive in the second half of this year. Following the Atome acquisition, it raised its 2028 guidance and expects the financial services business to generate an adjusted EBITDA of $500 million. It raised the group's 2028 adjusted EBITDA guidance to $1.5 billion. While the Superbank, Atome, and Foodpanda Taiwan acquisitions are expected to add $360 million in incremental EBITDA, Grab announced an additional deployment of $160 million in its business by 2028. CFO Peter Oey said that the investment will “widen our affordability offerings across the platform and to continue building structural advantages in groceries and retail.”
Grab also has a strong balance sheet and has a net cash position of $5.4 billion at the end of June. This allows the company to pursue acquisitions while also repurchasing shares. Incidentally, despite the Atome acquisition, Grab intends to complete its remaining buyback mandate of $900 million over the next year. As a side note, Grab is among the rare former SPACs that are repurchasing shares, and many from the lot are still raising cash amid perennial cash burn. Lucid Group (LCID), the biggest SPAC merger before Grab took the crown later in 2021, is a case in point. The company has been on a share-selling spree to fund its burgeoning cash burn.
The Final Word: Grab Looks Like a Buy
All said, I believe that Grab is worth the risk at these levels. It is a growth stock with valuations not very different from a value name. The stock has the potential to deliver strong returns over the next couple of years, but only risk-tolerant investors should consider the stock, given its volatility and the various moving parts in the equation.
On the date of publication, Mohit Oberoi had a position in: GRAB . All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.