
Should CEO Appointment Require Action From Bavarian Nordic (CPSE:BAVA) Investors?
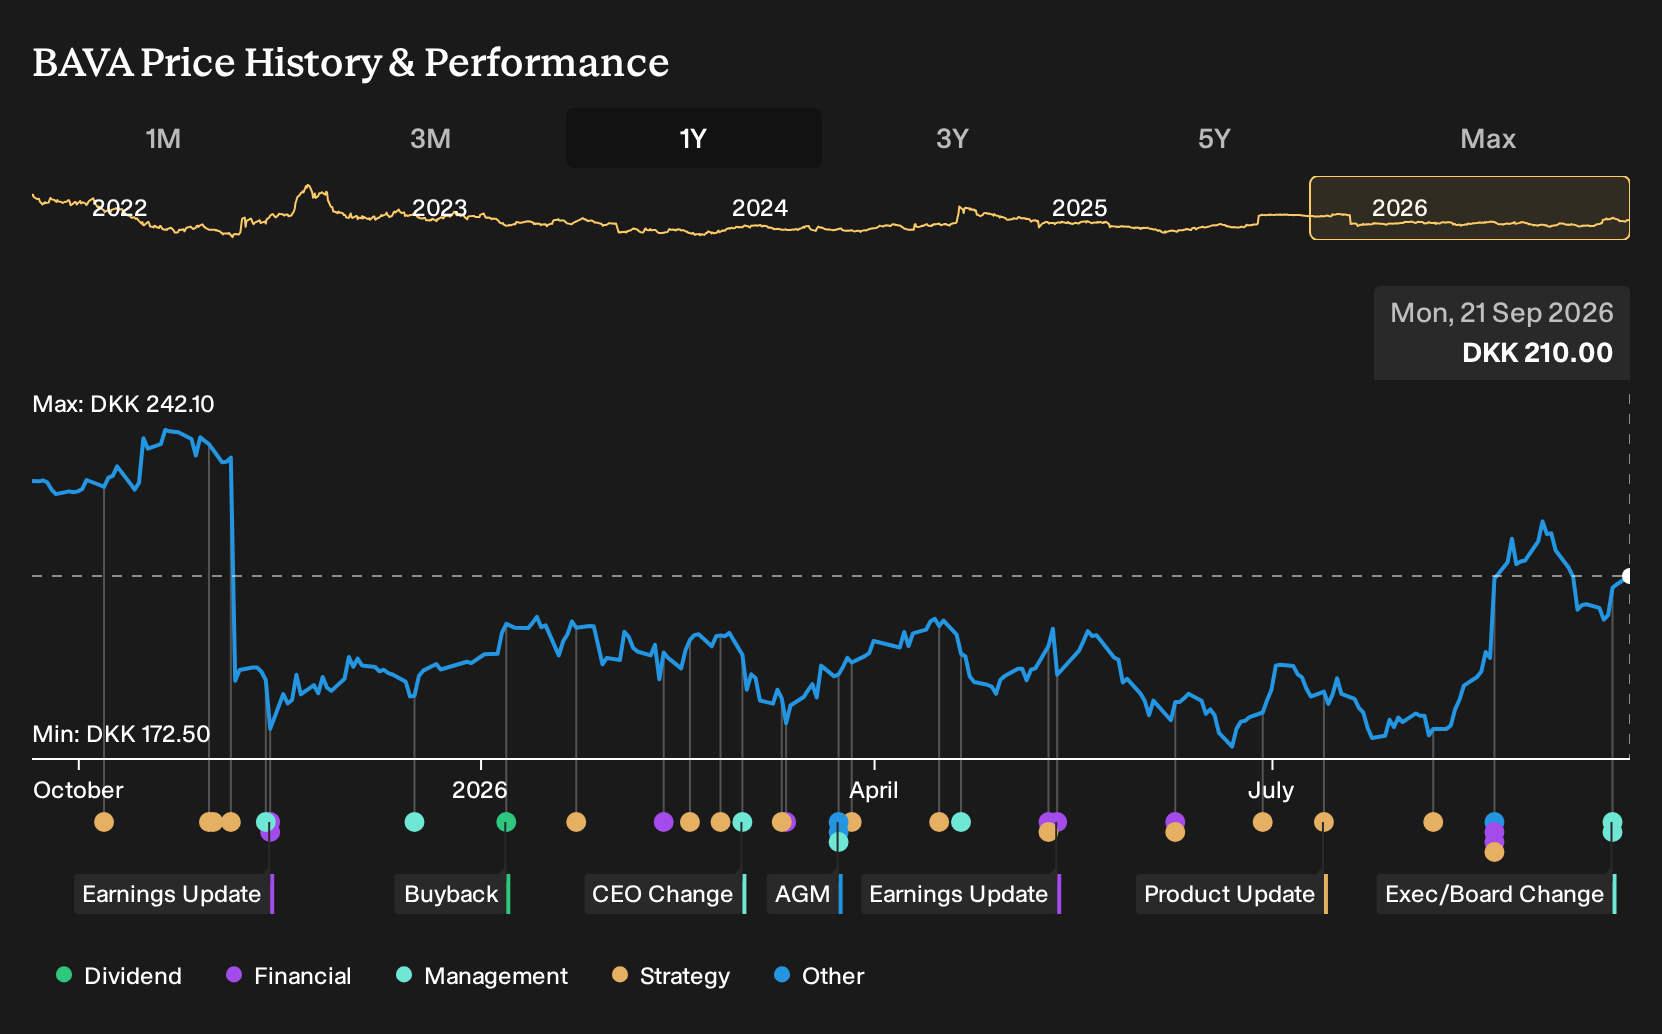
- Bavarian Nordic confirmed that Tarja Stenvall will take over as President and CEO on 15 October 2026, following Paul Chaplin, while the company continues repurchasing shares under a DKK 250 million buy-back program that has lifted treasury holdings to 3,959,913 shares, or 4.996% of share capital.
- Investors gain a leader with more than €3 billion profit and loss responsibility and deep vaccine and general medicines experience, alongside an active capital return program that could modestly reduce the share count over time.
- We will now look at how Bavarian Nordic's investment narrative could shift as Tarja Stenvall steps in with significant vaccine leadership experience.
Bavarian Nordic Investment Narrative Recap
To own Bavarian Nordic, you need to be comfortable with a vaccine specialist that leans on a concentrated portfolio in rabies, tick borne encephalitis, and smallpox or monkeypox, while trying to broaden its base through products like Chikungunya. The near term story still revolves around how resilient travel health and government preparedness demand remains as exceptional order patterns normalise.
The biggest swing factor right now is how earnings hold up if short term contracts ease and pricing pressure from public buyers tightens. The largest risk remains reliance on a few key vaccines and government stockpiling behaviour, and the incoming CEO appointment does not fundamentally change that near term operational exposure.
The share buy back program of up to DKK 250 million is the clearest recent signal that feeds into the current narrative. Management is actively reducing the free float, with treasury shares now at 3,959,913, or 4.996% of the share capital. This slightly amplifies the impact of any future earnings path on each share you own.
For you as a shareholder, that capital return story only really matters if Bavarian Nordic can keep volumes and margins resilient while analysts currently expect earnings to decline on average 5% a year over three years. The buy back helps on a per share basis, but operational execution on vaccine demand, pricing, and manufacturing efficiency still drives the main catalysts and risks.
What The Bavarian Nordic Forecasts Really Assume
Bavarian Nordic's consensus playbook is built on a simple idea. Revenue stays roughly where it is, while profitability does a bit more of the heavy lifting than it has in the past few years of exceptional demand.
Analysts currently model fairly flat top line performance over the next three years. They also assume profit margins ease back from 19.7% today to 16.1% in 2029, which means earnings do more than just mirror revenue. For you, that sets the scene for a story that is less about rapid expansion and more about how efficiently existing vaccines are produced and priced once one off contracts fade out.
On their numbers, earnings today of about DKK 1.2b are expected to settle at DKK 987.7m by 2029. That is a decrease of a little over DKK 200m in profit even before thinking about any upside or downside from future products or new contracts. The range of forecasts is wide, from DKK 616.8m at the cautious end to DKK 1.3b at the optimistic end, so you are dealing with meaningful disagreement on how resilient the business model will be as conditions normalise.
Those same forecasts imply Bavarian Nordic would be on a P/E of 23.5x in 2029 compared with 11.9x today and above the current 12.0x for the GB Biotechs industry. For that kind of multiple to make sense to you, the story has to be about more than headline earnings. It becomes a question of how durable the vaccine portfolio feels, whether management can protect pricing with large public sector buyers, and how much confidence you have in that June 2029 earnings line.
Bavarian Nordic's narrative projects DKK 6.1b revenue and DKK 987.7m earnings by 2029. This implies revenue that is broadly flat and an earnings decrease of a little over DKK 200m from current earnings of about DKK 1.2b.
Uncover why Bavarian Nordic's fair value indicates a 30% potential upside to its current price before that discount begins to close.
Exploring Other Perspectives
You can also zoom in on a very different catalyst. The most optimistic analysts were already pencilling in DKK 6.6b of revenue and DKK 1.3b of earnings by 2029 before this Bavarian Nordic CEO change. That is far above the cautious DKK 6.1b and DKK 987.7m path, and it shows how sharply opinions can diverge. Some investors may now reassess whether Tarja Stenvall’s vaccine and general medicines background makes that upper range feel more achievable, while others may stay closer to the lower band. Treat this leadership change and buyback news as a fresh prompt to compare those competing perspectives and decide which version of Bavarian Nordic you think is closer to reality.
Explore 2 other Bavarian Nordic fair value estimates, including one that suggests the potential for as much as 94% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bavarian Nordic research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bavarian Nordic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bavarian Nordic's overall financial health at a glance.
Looking for more Bavarian Nordic style ideas?
If the Bavarian Nordic story has you thinking about position sizing, risk and balance sheets, it can help to widen the lens and compare it with other listed businesses that share some of those qualities.
- For investors who care most about stability, especially when headlines are noisy, it can be useful to scan a curated set of lower risk profiles through 229 resilient stocks with low risk scores.
- If the appeal of Bavarian Nordic is its focus on fundamentals, you might want to see how that stacks up against a broader universe of strong operators using the 615 high quality undiscovered gems.
- Income focused readers can round out their watchlist by checking companies that offer higher yields and aim to keep payouts resilient with the 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com