
What ALKS 7290 ADHD Trial Results Mean For Alkermes (ALKS) Stock
- Alkermes reported positive topline data from a Phase 1b proof of concept study of ALKS 7290 in adults with ADHD, showing the orexin 2 receptor agonist was generally well tolerated over 14 days and associated with clinically meaningful changes on AISRS and CGI S scales.
- The trial produced the first clinical signal for an orexin agonist in ADHD and provided dosing, EEG biomarker and cognitive performance data that are being used directly in the design of Alkermes' ongoing Phase 2 program.
- This analysis examines how Alkermes' existing investment narrative may be influenced by this early ADHD orexin signal and proof of concept.
Alkermes Investment Narrative Recap
To own Alkermes, you need to believe the core neuroscience franchise can fund and support a broader orexin platform over time, even as R&D climbs and one off gross to net benefits fade. The recent ALKS 7290 proof of concept readout feeds directly into that story, because it adds another potential use case for the orexin portfolio beyond narcolepsy, using data already feeding Phase 2 design.
In the short term, the most important swing factor still looks like execution on Vivitrol, Aristada and Lybalvi while R&D and orexin costs step up. Profitability remains sensitive to rising trial spend and to any reset in those transient revenue tailwinds. The biggest operational risk is that heavier orexin investment, including ALKS 7290, does not convert into approvable, reimbursed products, which would pressure margins and limit earnings progress.
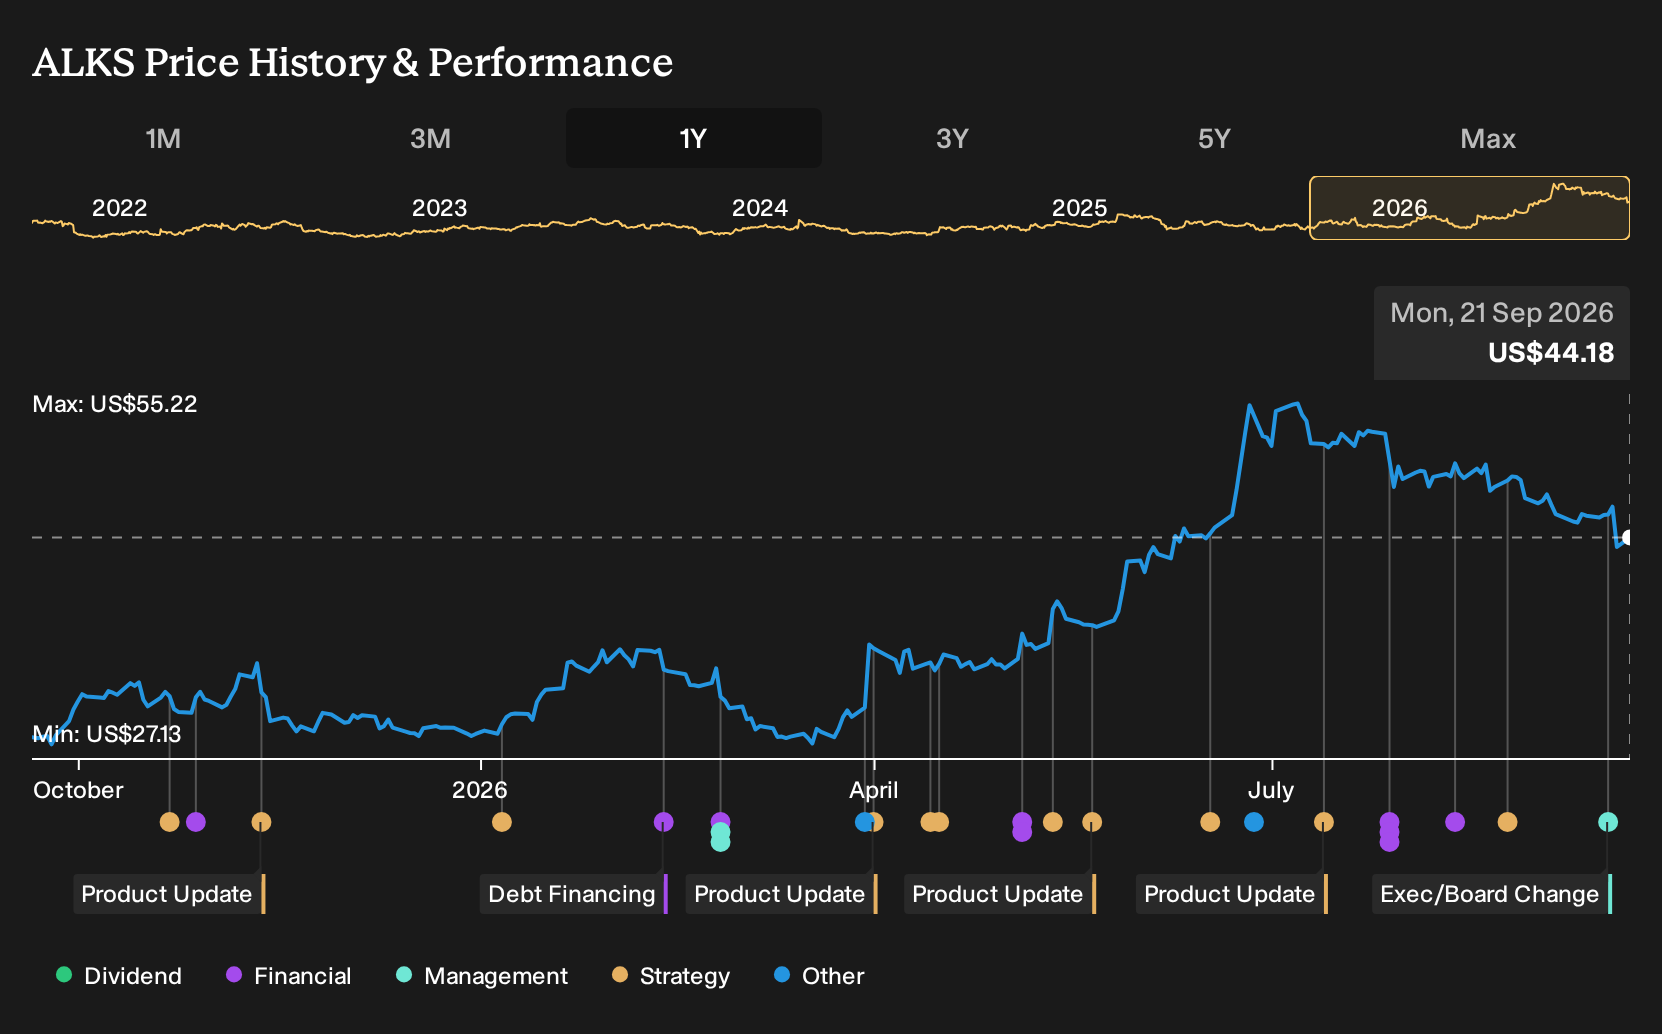
The news that ties closest to this orexin update is the appointment of Anne C. Whitaker as an independent director on 16 September 2026. Her background across commercial stage biopharma and clinical stage organizations gives Alkermes extra board level experience in scaling CNS assets and making trade offs between late stage spend and financial discipline.
For you as a shareholder, that kind of board profile matters when management is leaning into a bigger orexin program while carrying debt that is not yet well covered by operating cash flow and absorbing higher R&D. Oversight on capital allocation, go or no go decisions for Phase 2 and Phase 3 commitments, and the balance between pipeline ambition and near term cash generation could all influence how much operational risk Alkermes is willing to take on as ALKS 7290 moves forward.
What The Orexin Program Means For Alkermes' Analyst Case
Analyst models for Alkermes already incorporate a sizeable shift in the income statement, before giving any explicit credit for ALKS 7290 ADHD upside. Consensus assumptions point to revenue expanding at about 10.6% a year over the next three years, with profit margins moving from roughly 4.0% today to 16.6% by 2029 as the neuroscience portfolio scales and orexin spending is expected to be absorbed. Those same forecasts call for earnings to reach about US$374.7 million by 2029, compared with current earnings of roughly US$66.1 million, which implies an increase of a little under 5.7x on today’s profit base.
Alkermes' narrative projects revenue of about US$2.3b and earnings of roughly US$374.7 million by 2029. This assumes revenue growth of 10.6% per year and implies earnings rising by a little under 5.7x from around US$66.1 million today.
Uncover why Alkermes' fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts pricing pressure in the spotlight. Under that more cautious Alkermes narrative, the lowest analysts were only assuming about 7.5% annual revenue growth and roughly US$333.7 million of earnings by 2029, compared with the higher consensus figures. Your takeaway is that opinions already differed widely before this ADHD orexin news, and they may shift again as fresh data arrives.
Explore 4 other Alkermes fair value estimates, including one that suggests as much as 14% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Alkermes research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Alkermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alkermes' overall financial health at a glance.
Looking For More Investment Ideas Beyond Alkermes?
Once you have a view on Alkermes, it often helps to compare it with other listed businesses that match different portfolio goals, from income to resilience to future growth potential.
- For investors who care most about capital preservation and steadier profiles, consider scanning a 30 resilient stocks with low risk scores that can help you focus on businesses with lower overall risk scores.
- If you want to anchor your watchlist around cash rich operators with strong fundamentals, start with a list of solid balance sheet and fundamentals (23 results) that screens for healthier balance sheets and cleaner finances.
- Those hunting for overlooked opportunities can review a 17 high quality undiscovered gems that highlights under the radar companies which still screen well on quality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com