
Is Randstad (ENXTAM:RAND) Fully Valued After Its Malaysia Expansion?
Randstad Malaysia expansion puts regional growth in focus
Randstad (ENXTAM:RAND) is drawing attention after Randstad Malaysia expanded its Bangsar South presence in Kuala Lumpur, adding Level 5 to accommodate a 15% year-on-year rise in internal headcount and stronger first half 2026 activity.
Recent trading tells a mixed story. Randstad’s share price is €36.33 after a 90 day share price return of 36.84% and year to date share price gain of 12.13%, while the 5 year total shareholder return is down 13.41%. This suggests that shorter term momentum contrasts with weaker longer term outcomes.
Scan how Randstad compares with other recruiters and HR platforms by reviewing hand picked opportunities in the list of solid balance sheet and fundamentals (198 results).
Randstad now trades almost exactly in line with analyst targets, while one intrinsic value model points to a near 50% gap. Is the recent share price surge already fair, or is it only halfway there?
Most Popular Narrative: 2% Overvalued
Randstad’s most followed valuation story pegs fair value at €35.72, slightly below the recent €36.33 close. The current rally therefore sits just ahead of that reference point while still relying on a gradual recovery in staffing demand.
Randstad's ongoing investment and growth in digital staffing platforms and AI-driven talent matching are increasing operational efficiency and productivity, for example more placements per FTE, robust digital marketplace adoption in the US, APAC, and Australia/NZ. This should support improved net margins and drive future earnings growth.
See why 24 investors see Randstad as 2% overvalued.
Result: Fair Value of €35.72 (OVERVALUED)
Still, Randstad’s story could change quickly if ongoing weakness in higher margin professional hiring persists, or if margin pressure from large clients intensifies.
Find out about the key risks to this Randstad narrative.
Another View on Randstad valuation
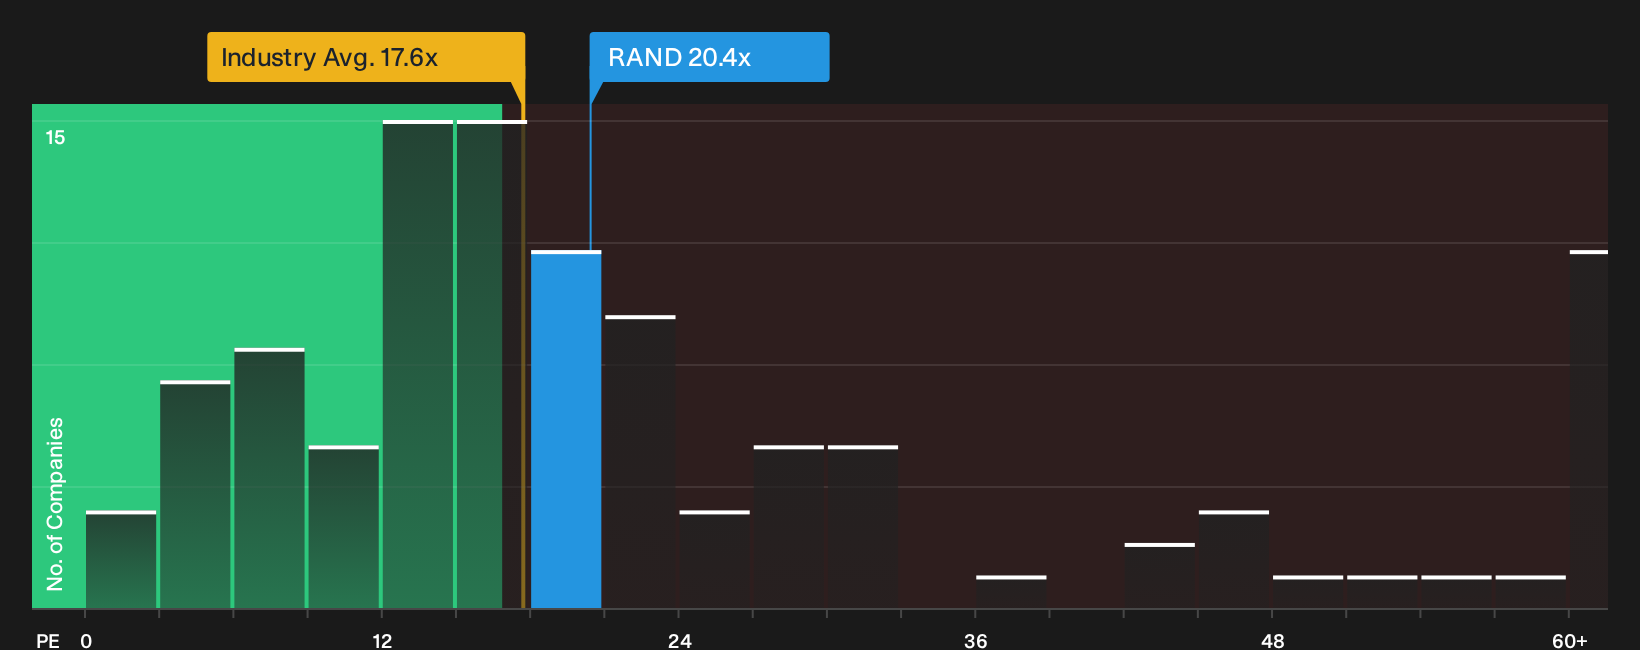
Analyst targets suggest Randstad is only slightly ahead of fair value, yet the market is valuing the business on a P/E of 20.4x. That is below peer average at 21.2x, and also below a fair ratio estimate of 21.4x, which points to only a modest valuation gap either way.
This means investors are paying a small premium to the wider European professional services group, while still sitting under the level our fair ratio suggests the multiple could move towards. Does that narrow band leave enough upside to justify the recent share price swing, or does it mostly cap the room for error from here?
For a deeper look at how this earnings multiple compares with sector peers and that fair ratio, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Randstad valuation can feel messy, so act while the data is fresh and weigh both sides for yourself with 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Randstad?
Do not stop with Randstad. Use fresh data, filter for what matters to you, and build a watchlist that actually reflects how you want to invest.
- Target potential mispricings by scanning companies that screen as strong quality at appealing valuations through the 174 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses that combine robust finances with dependable fundamentals using the 229 resilient stocks with low risk scores.
- Spot opportunities the crowd may be missing by filtering for financially solid but less followed stocks through the 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com