
Applied Materials (AMAT) Stock Looks Above Fair Value After Its 248% Run
Applied Materials has delivered eye catching gains over the past few years, and with the share price recently closing at US$464.24, many investors are asking whether those returns are still grounded in the company’s earnings power. With the stock closely linked to the semiconductor and AI build out, the core issue now is how much of that story is already reflected in what you pay per dollar of profit.
- Over the past 3 years, Applied Materials has returned 247.9%, which puts pressure on current earnings to support the higher equity value.
- Recent commentary around strong AI related demand for chipmaking tools and metrology equipment can support expectations for future profitability, which in turn matters for how much investors are willing to pay for each unit of earnings.
- There is a second opinion on Applied Materials worth weighing. See what analysts think Applied Materials's shares could be worth.
The stock's next move may depend on whether today's valuation is justified by Applied Materials' earnings when measured against Fair Ratio.
If you are weighing Applied Materials against the wider AI hardware build out, it can help to line it up beside other 87 AI infrastructure stocks.
Where Does Applied Materials Sit on Earnings?
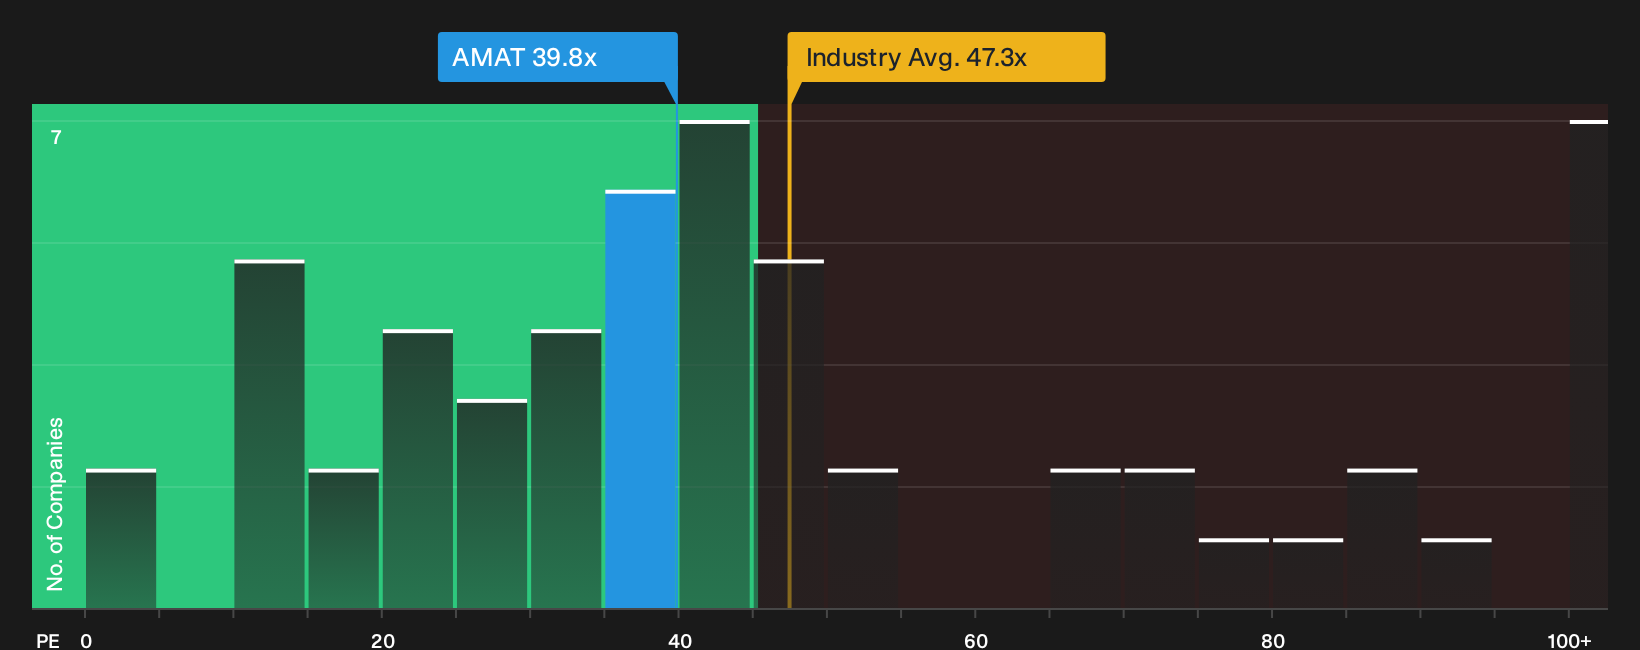
The P/E ratio suits Applied Materials because earnings remain the main yardstick most investors use to judge what they are paying for each dollar of profit. At roughly 39.8x earnings, the stock trades below the wider semiconductor sector on about 47.3x and also sits under the peer group at around 43.3x.
Because the latest Fair Ratio, which blends in factors such as growth expectations, margins, size and risk, points to a level close to where Applied Materials trades today, the current P/E looks about right relative to that tailored benchmark. Despite management commentary around strong AI driven demand for chipmaking and metrology tools lifting expectations, the market is not placing a clear premium multiple on the shares compared with sector norms. This leaves the P/E as a starting point for weighing how durable those earnings are. Explore the numbers behind Applied Materials's P/E valuation.
The Applied Materials Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Applied Materials valuation puzzle leaves off. Each scenario explains what would need to happen to growth, profitability and earnings for the stock to be worth materially more or less than today’s price. It also ties a grounded fair value to a clear story about potential catalysts and risks, so you can track over time which version of the future appears to be gaining traction on the Community page.
Applied Materials attracts both investors who see a long AI equipment cycle ahead and others who think current optimism already prices that in.
Bull case: 26% undervalued
"Advanced packaging remains Applied's area of highest market share, bolstered by strong customer collaboration and a growing pipeline of new hybrid bonding and integration technologies…"
Discover why this Narrative puts Applied Materials at 26% undervalued.
Bear case: 7% overvalued
"Trade restrictions and slowed DRAM and ICAPS sales may significantly limit revenue growth, especially from the China market…"
Explore why this Narrative puts Applied Materials at 7% overvalued.
Applied Materials: why the share price is only one part of your decision
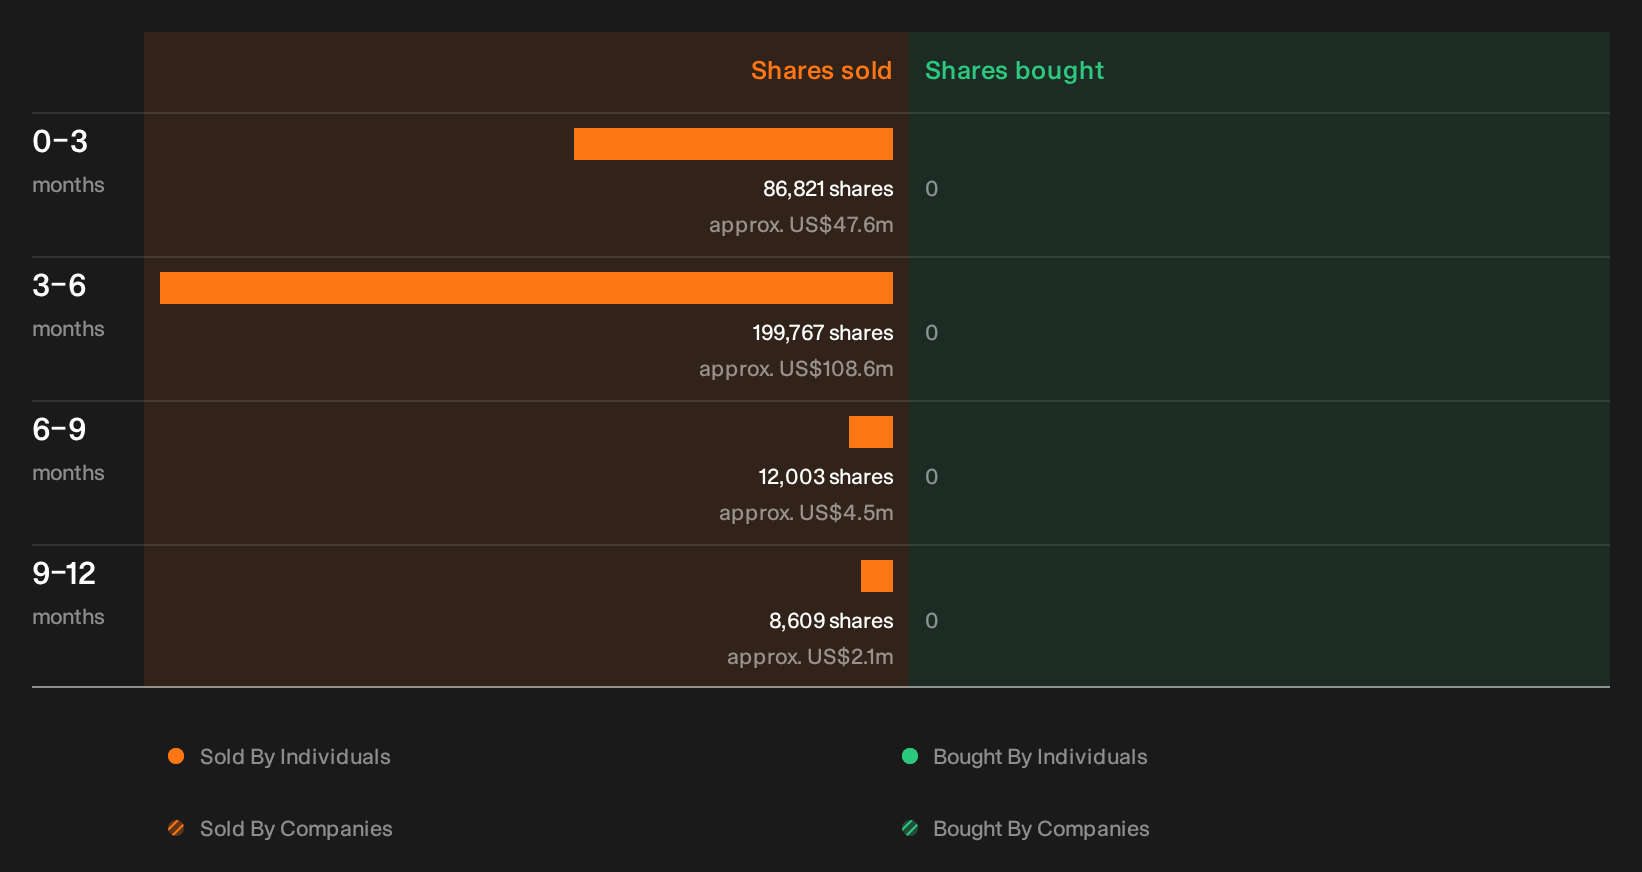
Valuation tells you what you are paying, but the recent trading activity from key insiders can hint at how people closest to Applied Materials are acting. The identities, scale and possible read throughs are all set out here. See the recent insider selling flagged for Applied Materials.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com