
Advanced Drainage Systems (WMS) Pulls Back On Valuation Debate, Is The Discount Real?
Advanced Drainage Systems (WMS) has drawn fresh attention after a recent pullback, with the share price down about 12% over the past month and roughly 9% over the past 3 months.
Against that pullback, Advanced Drainage Systems is still working through a weaker patch, with the share price down 15.2% year to date and 11.25% lower on a 1-year total shareholder return basis. However, the 3-year and 5-year total shareholder returns of 11.54% and 17.73% point to a much stronger longer-term record, which indicates that recent selling may reflect a reset in expectations and risk appetite rather than a verdict on the company’s entire track record.
Compare this pullback in Advanced Drainage Systems with a curated list of solid balance sheet and fundamentals (23 results) that may also interest long term investors looking beyond a single quarter.
Advanced Drainage Systems now sits in a pocket of weakness after a solid multi year run, so investors may be weighing whether it makes more sense to step in at today’s level or wait for an even cheaper entry before committing fresh capital.
Preferred P/E of 20.9x: Is it justified?
Valuation on Advanced Drainage Systems today hinges on a P/E of 20.9x, which sits below its peer group average yet slightly above the broader US Building industry.
The P/E ratio compares the current share price with earnings per share, so it reflects how much investors are paying for each dollar of profit. For Advanced Drainage Systems, a 20.9x multiple sits against reported earnings growth of 5.8% over the past year and a 5 year earnings growth rate of 11.4% per year, as well as a high Return on Equity of 25.4%.
Compared with similar companies, Advanced Drainage Systems is described as good value relative to a peer P/E average of 33.4x. This suggests the market is applying a lower earnings multiple than that tighter peer set. At the same time, the stock is described as expensive versus the wider US Building industry P/E of 20.1x. In other words, investors are paying a premium to that broader group even though earnings are forecast to grow, but not significantly. The estimated fair P/E of 24.9x also sits above the current 20.9x level. This is framed as a level the market could move towards if sentiment and results stay aligned with this assessment.
Explore the SWS fair ratio for Advanced Drainage Systems.
Result: Price-to-earnings of 20.9x (UNDERVALUED).
Still, the Advanced Drainage Systems story can be knocked off course if construction demand weakens further or if rising input costs reduce its 25.4% Return on Equity.
Find out about the key risks to this Advanced Drainage Systems narrative.
Another View: What The DCF Model Says About Advanced Drainage Systems
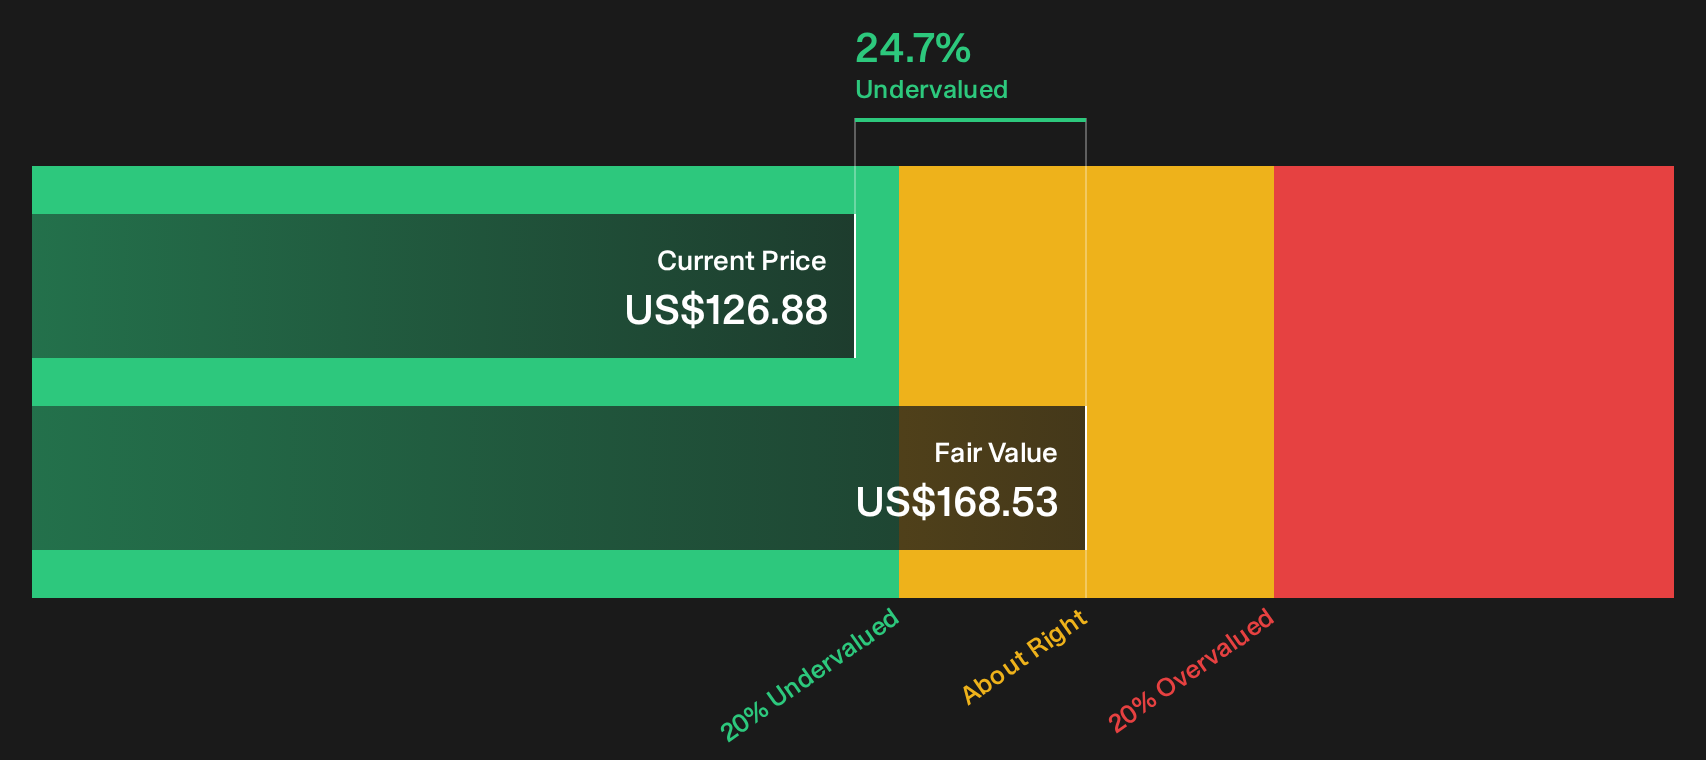
A second lens on Advanced Drainage Systems comes from the SWS DCF model, which values the shares at $168.53 against a recent price of $126.88. That gap points to the stock trading at a discount, although any DCF output is only as strong as the assumptions that feed it. If those inputs shift, does this implied upside still hold up for you as an investor?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Advanced Drainage Systems for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Advanced Drainage Systems so far, right? If you want to move early and rely on your own homework, weigh up the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Advanced Drainage Systems?
If Advanced Drainage Systems is already on your radar, do not stop there. Use the tools available to scan for fresh opportunities before the crowd notices them.
- Target value opportunities early by reviewing a focused 30 high quality undervalued stocks that highlights companies combining quality fundamentals with prices that may not fully reflect them.
- Prioritise strength and resilience by scanning a curated 30 resilient stocks with low risk scores that filters for businesses with lower risk profiles and more robust financial footing.
- Hunt for future leaders by working through a hand picked 17 high quality undiscovered gems filled with under the radar stocks supported by solid underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com