
Bank Of Nova Scotia (TSX:BNS) Launches Scotia Growth Institute As Fair Value Debate Tightens
Bank of Nova Scotia (TSX:BNS) has kicked off a new business expansion with the Scotia Growth Institute, a platform aimed at supporting long term economic competitiveness across Canada and North America for key stakeholders.
Recent trading has been strong for Bank of Nova Scotia, with a 30 day share price return of 11.03% and a year to date gain of 30.73% at a share price of CA$133.87. The 1 year total shareholder return of 57.00% and 3 year total shareholder return of 153.19% suggest momentum has been building over time as investors react to new initiatives like the Scotia Growth Institute and a series of fixed income offerings completed in September 2026.
Scan how Bank of Nova Scotia’s recent momentum compares with other established financial institutions by reviewing the hand picked 8 resilient stocks with low risk scores in similar sectors.
After a 57.00% 1 year total return and a move above the current analyst price target, Bank of Nova Scotia now forces a simple choice. Investors can either pay up for the recent momentum or wait and hope for a better entry as valuation comes into focus next.
Most Popular Narrative: 1% Overvalued
Bank of Nova Scotia is trading at CA$133.87 compared to a narrative fair value of about CA$132.71, which leaves almost no valuation gap for investors to lean on and places more emphasis on how the story around growth and margins develops from here.
Expansion of banking and wealth management services in high-growth Pacific Alliance countries (Mexico, Peru, Chile, Colombia) positions BNS to capture revenue growth from increasing financial inclusion and rising middle-class demand for loans and investment products, supporting future top-line and earnings expansion.
See why 175 investors see Bank of Nova Scotia as 1% overvalued.
Result: Fair Value of CA$132.71 (ABOUT RIGHT)
Still, Bank of Nova Scotia’s heavy exposure to Latin America and the Canadian housing market could pressure credit quality and earnings if conditions worsen in either region.
Find out about the key risks to this Bank of Nova Scotia narrative.
Another View on Bank of Nova Scotia’s Valuation
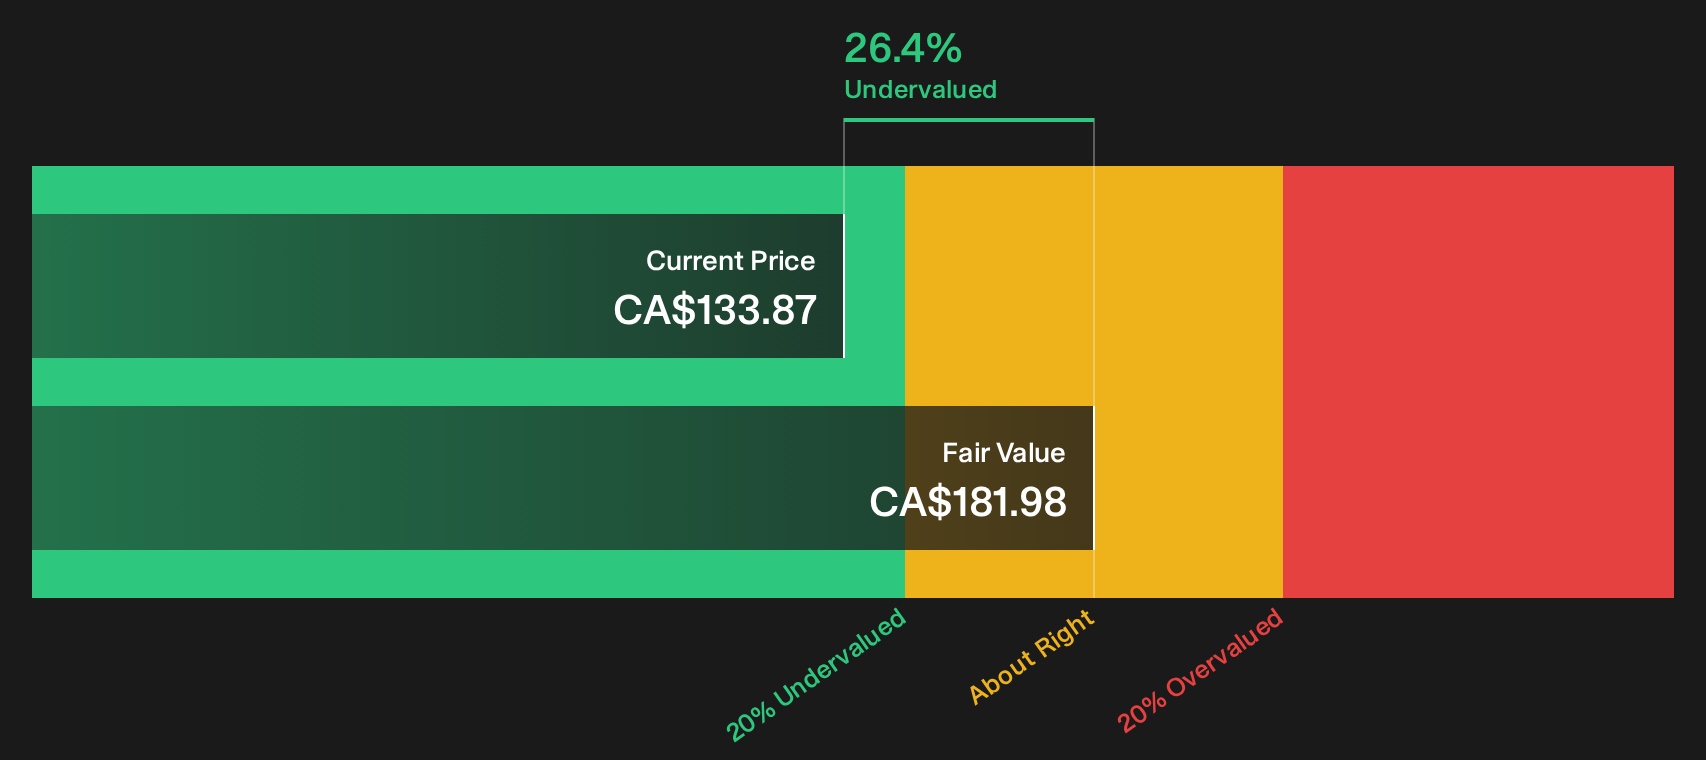
On the one hand, Bank of Nova Scotia screens as roughly in line with analyst fair value at CA$132.71. On the other hand, our DCF model points to future cash flow value of CA$181.98 at a share price of CA$133.87. This raises a simple question: Which story do you trust more, the spreadsheet or the Street?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Bank of Nova Scotia’s valuation and risk profile can feel messy. Move quickly, review the full picture, and decide for yourself by checking the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Bank of Nova Scotia?
If Bank of Nova Scotia has you thinking more broadly about where to put fresh capital to work, use this moment to widen your opportunity set with targeted screeners.
- Spot potential mispricings early by scanning companies that look statistically cheap on key metrics using the 6 high quality undervalued stocks.
- Build a cash flow focused watchlist by zeroing in on income plays highlighted in the 1 dividend fortresses.
- Secure a sturdier core portfolio by filtering for financially robust businesses through the list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com