
Is Balchem (BCPC) A Bargain Following Its Recent Pullback?
Balchem (BCPC) has drawn fresh attention after a recent pullback, with the stock down about 8% over the past month even as its year to date return remains positive.
Recent trading has been choppy for Balchem, with the share price return down 7.69% over the past month but still showing an 8.65% share price gain year to date and a 34.44% total shareholder return over three years. That pattern points to fading short term momentum, while longer term holders have still seen compounded gains as investors reassess growth prospects and risk around the current US$167.34 share price.
Scan beyond Balchem's recent pullback and review other high quality, potentially mispriced companies with our hand picked 30 high quality undervalued stocks.
Balchem now trades at roughly a 25% discount to both analyst targets and one intrinsic value estimate after that pullback. Is this cautious pricing pointing to hidden issues, or creating room for upside as assumptions reset?
Most Popular Narrative: 19% Undervalued
Against Balchem's last close at $167.34, the most followed narrative anchors fair value at $207. This frames the recent pullback as a potential gap between price and modeled fundamentals.
The new state-of-the-art microencapsulation facility in New York is set to more than double Balchem's capacity in a high-growth, premium segment. This is expected to enable sustained double-digit sales growth in Human Nutrition & Health while also boosting manufacturing efficiency for future margin expansion.
Strong clinical research pipeline and recent high-impact studies (e.g., choline and Alzheimer's, OptiMSM and recovery) are likely to accelerate adoption of Balchem's differentiated, science-backed ingredients. This would support increased market penetration and premium pricing power, positively impacting both revenues and net margins.
See why 2 investors see Balchem as 19% undervalued.
Result: Fair Value of $207 (UNDERVALUED)
Still, the bullish Balchem narrative depends on smooth execution of its new US$36 million facility and on product innovation not stalling under competitive pressure.
Find out about the key risks to this Balchem narrative.
Another View: Balchem On Earnings Multiples
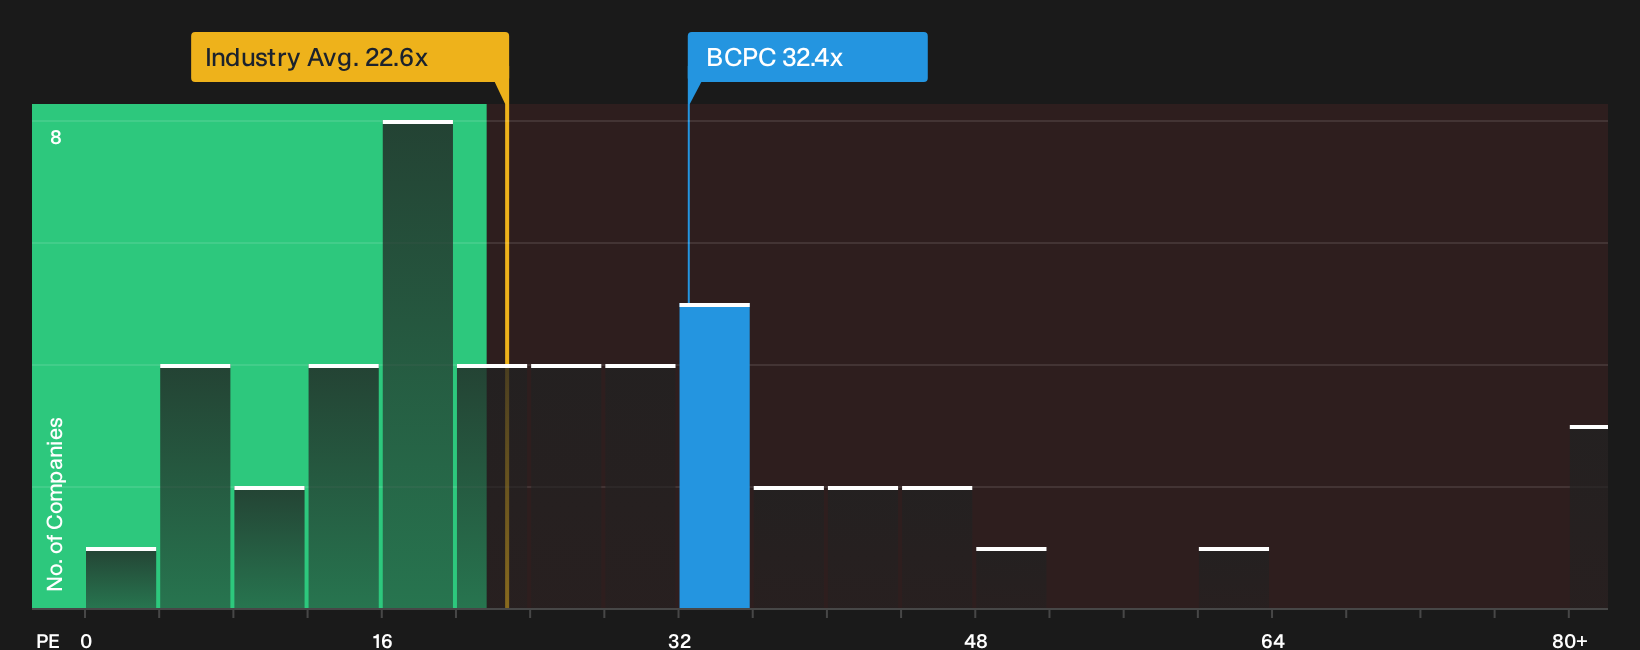
There is a different read on Balchem when you look at the current P/E of 32.4x against the US Chemicals sector on 22.7x and a peer average of 30.5x, and against a fair ratio of 16.7x. That kind of premium can signal quality, but it also raises the question of how much valuation risk you are comfortable carrying.
For a closer look at how this pricing compares with earnings power and peers, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Is the mood around Balchem too cautious or not cautious enough? Act while sentiment is still recalibrating and stress test the optimism by reviewing the 4 key rewards.
Looking for more investment ideas beyond Balchem?
If you are reassessing Balchem after the recent pullback, this is a smart moment to widen your watchlist and line up a few strong alternatives.
- Target potential mispricing opportunities by scanning a curated 30 high quality undervalued stocks that already clear quality and balance sheet checks.
- Lock in more predictable cash flow by focusing on income ideas filtered through our 7 dividend fortresses with yields that stand out from the market average.
- Sleep easier at night by concentrating on companies in the 30 resilient stocks with low risk scores that score well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com