
Wendel (ENXTPA:MF) Could Be 22% Undervalued On Interim Dividend News
Why Wendel’s interim dividend matters now
Wendel (ENXTPA:MF) has set an interim dividend of €2.55 per share for the 2026 financial year, with ex-dividend on 17 November, record on 18 November, and payment on 19 November.
Recent trading reflects a mixed picture for Wendel. The share price return is up 1.9% over the past 90 days and 2.1% year to date, while the 1 year total shareholder return of 10.3% points to steadier gains once dividends like this interim payment are included. This suggests that recent price softness over the past month may reflect shifting views on risk rather than a clear change in the longer term story.
Scan other dividend-focused opportunities with the same income angle as Wendel by checking our curated list of 162 dividend fortresses.
Given Wendel’s recent gains over 1 year but a softer past month, the interim dividend adds another layer. Does the current valuation still leave enough upside to justify the risks from here?
Most Popular Narrative: 22% Undervalued
Against Wendel’s last close at €83.35, the most followed fair value estimate of €106.67 points to a sizeable valuation gap, which frames how this interim dividend might sit within a wider rerating story.
Expansion in asset management and digital transformation initiatives is associated with higher earnings, revenue growth, and improved margins through new products and increased global capital inflows. Strategic portfolio rebalancing and a strengthened ESG focus are described as enhancing liquidity, reinvestment capacity, and access to institutional capital, with potential implications for growth and valuation.
See why 4 investors see Wendel as 22% undervalued.
Result: Fair Value of €106.67 (UNDERVALUED)
Still, the Wendel narrative can be knocked off course if non listed holdings keep struggling or if FX swings continue to drag on reported net asset value.
Find out about the key risks to this Wendel narrative.
Another view on Wendel’s valuation
The SWS DCF model paints a very different picture for Wendel. On that framework, the estimated future cash flow value is €68.01 per share, compared with the current price of €83.35. That implies the stock screens as overvalued on cash flows, even while analyst targets point higher. Which lens do you trust more for the next decision?
Look into how the SWS DCF model arrives at its fair value.
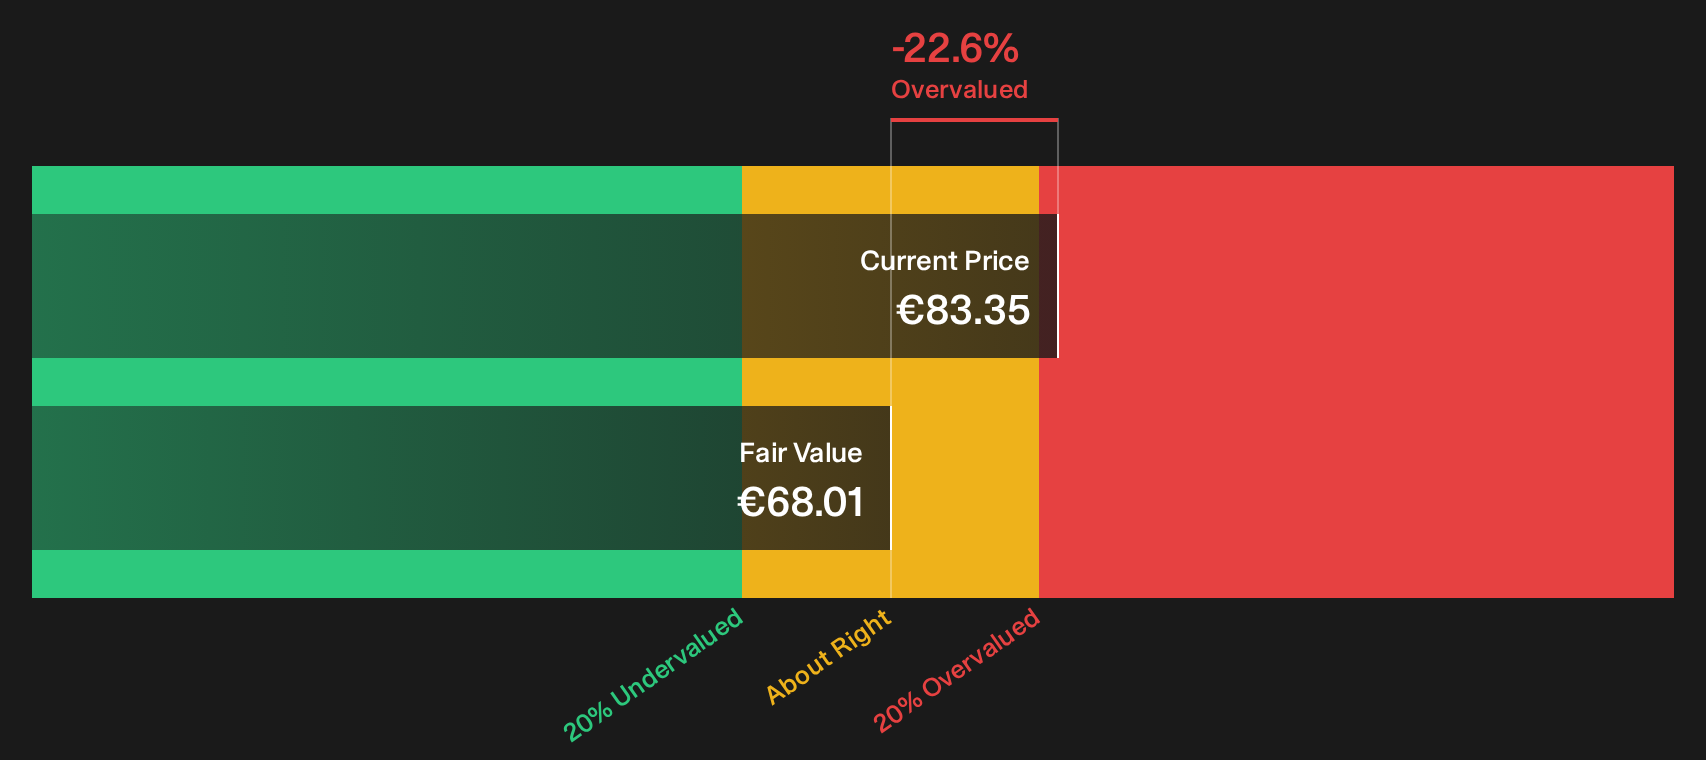
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Wendel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 173 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and income rarely resolve themselves for you. Check the underlying data now, weigh Wendel’s risks against its potential rewards, and use the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Wendel?
If Wendel has your attention, do not stop here. The same tools that helped frame this dividend and valuation story can surface other opportunities that fit your style.
- Target dependable income streams by scanning companies that look like potential 162 dividend fortresses for yield-focused portfolios.
- Hunt for potential mispriced opportunities by running through a curated set of 173 high quality undervalued stocks that pair quality with attractive valuations.
- Prioritise resilience under pressure by focusing on 229 resilient stocks with low risk scores that aim to keep volatility in check while you stay invested.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com