
Sigma Lithium (SGML) Pushes Back On Brazil Ruling, Is The Stock Below Fair Value?
Assessing the judicial overhang on Sigma Lithium
Sigma Lithium (SGML) responded to reports of a preliminary judicial ruling in Brazil by stressing that mining and processing activities remain ongoing and environmental licenses have not been formally suspended.
The business linked the situation to a reported court decision issued during a recess and more than 300 km from its operations in Vale do Jequitinhonha. Management stated it has not received official notice of any injunction and has already prepared legal steps as courts reopen.
For investors, the core issue is not only the legal process itself but how long this uncertainty could sit over Sigma Lithium and its share price. Legal commentary in the company release points to multi year timelines before any final ruling or potential fines would be confirmed.
In parallel, the miner reiterated its production ambitions tied to the TAC Agreement with Minas Gerais authorities. Sigma Lithium highlighted delivery expectations of 240,000 tonnes of lithium oxide concentrate within 12 months and 330,000 tonnes in fiscal 2027, framing the ruling as separate from this accord.
The same statement pushed back against media stories suggesting that the preliminary decision might override the TAC Agreement. Management described those reports as inaccurate and positioned the company as operating within Brazilian law, with a long track record of engagement with regulators and local communities.
Beyond the courtroom angle, the release spent significant space on environmental and social practices at Sigma Lithium. The group pointed to dry stacking of tailings, water reuse, absence of toxic chemicals in processing and bio regeneration of rock piles as key features of its operations in Brazil.
The company also emphasized more than 1,100 days without accidents with lost days, low dust and noise levels and its role in supporting 19,000 job positions and roughly 80,000 family members in the region. Those operational and community details give investors more context for assessing reputational risk alongside legal risk.
On the market side, Sigma Lithium shares last closed at US$10.27, with the stock up 3% on the day and higher over the past week. Over the past month the share price has declined 14%, and over the past 3 months it is down about 19%, while the 1 year total return is reported at 64%.
The longer record looks different. Sigma Lithium shows a 3 year total return down about 70% and a 5 year total return of roughly 23%, which underlines how volatile early stage resource stories can be when funding needs, commodity prices and project execution all matter at once.
On fundamentals, the miner reports revenue of US$142.494m from its metals and mining activities, with Brazil as its sole geographic revenue source. The business still posted a net loss of US$27.564m, so investors are dealing with a growth focused producer that is not yet consistently profitable.
Market value sits around US$1.12b, which gives a rough market cap to sales multiple of about 8x based on the latest revenue figure. That kind of ratio is not unusual for a developing resource producer, although investors often compare it against peers and their stage of production maturity.
The data provided lists a value score of 1 for Sigma Lithium, which may suggest the stock does not screen as cheap on some quantitative models. Readers should treat that as a starting flag to dig deeper into capital intensity, expected production volumes and cost structure rather than a verdict in itself.
Annual revenue growth is given at 35.989%, while net income growth is 85.203%. Since Sigma Lithium is still loss making, those percentages may reflect shifts from a low base rather than a stable earnings pattern, so it helps to focus on absolute dollar numbers and the path to sustainable free cash flow.
For context, the company positions itself as part of the lithium supply chain serving electric vehicle batteries and related storage uses. Every tonne of lithium oxide concentrate that Sigma Lithium brings to market feeds into a broader ecosystem that includes battery makers, automakers and, increasingly, data centers and grid storage projects.
The September 8 legal update also touched on Brazil's political backdrop ahead of the November 15 election. Sigma Lithium suggested that media noise around its operations could increase into the vote, which reminds investors to separate source quality from speculation when trading headlines.
When looking at a situation like this, retail investors can break the story into a few practical questions. What is actually happening on the ground, what are the legal scenarios and how is the current share price reflecting those moving parts?
- Operationally, Sigma Lithium says mines and industrial plants are functioning, with no formal notice of license suspension in hand.
- Legally, the preliminary ruling appears early in the process, and the firm expects a multi year pathway before any final judgment or financial impact would be confirmed.
- Commercially, the delivery targets under the TAC Agreement give a quantitative reference for future output, although investors still need to consider execution risk and funding needs.
Environmental and social claims also matter for a miner whose brand leans on "Quintuple Zero Lithium." For readers, the checklist might include independent verification of safety records, environmental audits, and the durability of agreements with state and municipal authorities in Minas Gerais.
Given the mix of judicial questions, production goals and recent share price swings, Sigma Lithium sits at the intersection of legal risk, commodity exposure and ESG themed investing. Retail investors weighing exposure to this stock can consider position sizing carefully and think about how a concentrated lithium producer fits within a broader portfolio that may also hold diversified miners or battery makers.
For Sigma Lithium, that mix of courtroom headlines and production messaging is feeding into a sharp split between short term swings and longer term payoffs, with recent share price strength over the past week and year sitting alongside a weaker multi year total shareholder return profile.
The stock's 1 day share price move of 3.01% and 7 day share price return of 15.26% suggest buying interest has picked up into the latest legal update, even though the 30 day and 90 day share price returns are still down 14.20% and 18.56%. Those shorter term losses sit against a 1 year total shareholder return of 63.80%, while the 3 year total shareholder return is down 70.18%, which underlines how quickly sentiment has shifted as investors reassess both growth potential and legal risk around Sigma Lithium.
Spot opportunities around Sigma Lithium by scanning a curated list of 36 best rare earth metal stocks that could also be leveraged to the EV and battery supply chain story.Bulls see Sigma Lithium as a beaten up pure play on EV materials, while bears see a loss making miner with legal noise and a rich sales multiple. Which case does the current valuation actually lean toward?
Most Popular Narrative: 49% Undervalued
On the most followed narrative, Sigma Lithium is framed as materially undervalued, with a fair value of $20.00 against the latest close at $10.27, and that gap is built on a specific view of low cost Brazilian output and future earnings power.
Structural positioning at the extreme low end of the global cost curve, with all in sustaining costs guided down toward about $500 per tonne after Plant 2, is expected to provide significant cushion in volatile pricing environments and support stronger net margins over the long term.
See why 1 investors see Sigma Lithium as 49% undervalued.
Result: Fair Value of $20.00 (UNDERVALUED)
Still, the bullish Sigma Lithium story runs into trouble if legal challenges drag longer than expected or if lithium prices weaken and squeeze the low-cost thesis.
Find out about the key risks to this Sigma Lithium narrative.
Another View on Sigma Lithium’s Valuation
The fair value narrative around Sigma Lithium leans heavily on future earnings power, yet the SWS DCF model tells a different story. On that measure, the stock at $10.27 trades above an estimated future cash flow value of $5.02, which implies an overvalued signal and a very different risk profile. How comfortable are you backing cash flow assumptions that far out?
Look into how the SWS DCF model arrives at its fair value.
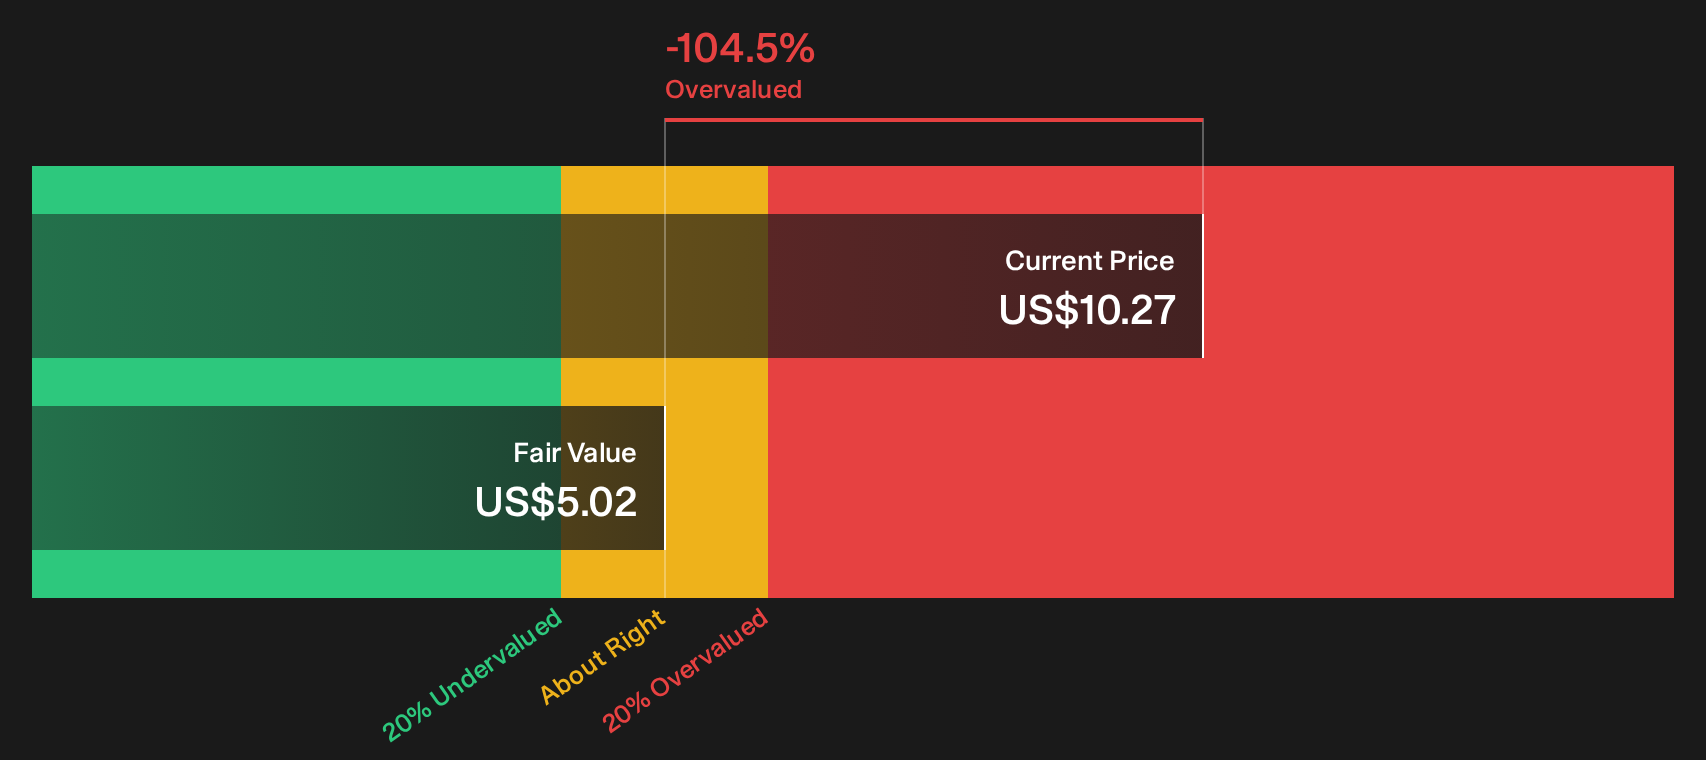
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sigma Lithium for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With Sigma Lithium framed as both a legal question and a valuation puzzle, the real edge comes from doing the work yourself. Take a closer look at the 2 key rewards.
Looking for more Sigma Lithium sized opportunities?
Do not stop with Sigma Lithium. The same tools that surfaced this story can help you quickly spot other potential winners and avoid weaker ideas.
- Target stronger price tags by scanning a curated pool of 30 high quality undervalued stocks that combine quality fundamentals with more modest expectations baked into their current share prices.
- Prioritise resilience by reviewing a focused 30 resilient stocks with low risk scores that leans toward companies with steadier risk profiles and fewer financial red flags.
- Get ahead of the crowd by working through a 17 high quality undiscovered gems that highlights under-followed businesses with solid numbers and room for the story to spread.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com