
Cracker Barrel Old Country Store (CBRL) Has Investors Watching Closely, What Is Driving The Attention?
Cracker Barrel Old Country Store (CBRL) heads into a key week as it prepares to release fourth quarter earnings before the opening bell on Wednesday, Sept. 23, with expectations signaling sharply lower profit per share.
Cracker Barrel Old Country Store shares closed at US$44.87, with the 30-day share price return down 22.17%. The year-to-date share price return is up 67.11%, while the 1-year total shareholder return of 4.64% against a 5-year total shareholder return decline of 61.56% points to momentum that has improved recently but follows a long period of weaker compounding for long-term holders.
Scan how Cracker Barrel Old Country Store compares with other consumer names facing earnings pressure by reviewing our curated list of 30 high quality undervalued stocks that may offer a different balance of risk and return.
Cracker Barrel Old Country Store now carries a sharp short term pullback, layered on top of a strong year to date rebound. Does that swing reflect business reality, or just a reset in sentiment as earnings hit?
Most Popular Narrative: 0% Undervalued
Cracker Barrel Old Country Store last closed at $44.87, almost exactly in line with the most followed fair value estimate of $45.00. This frames earnings week as more of a test of expectations than of valuation extremes.
Cracker Barrel's remodel and refresh program, which remains in the test-and-learn phase, aims to significantly enhance store atmosphere and guest experience, potentially leading to increased foot traffic and higher sales, positively affecting revenue growth.
What is behind that confidence in higher future earnings, and how are investors reading it into the stock rating right now? 10 investors see Cracker Barrel Old Country Store as 0% undervalued.
Result: Fair Value of $45.00 (ABOUT RIGHT)
Still, softer traffic trends and higher interest expenses on planned debt refinancing could quickly weaken the upbeat Cracker Barrel Old Country Store margin narrative that investors are watching.
Find out about the key risks to this Cracker Barrel Old Country Store narrative.
Another View: Cracker Barrel Old Country Store Through Earnings Multiples
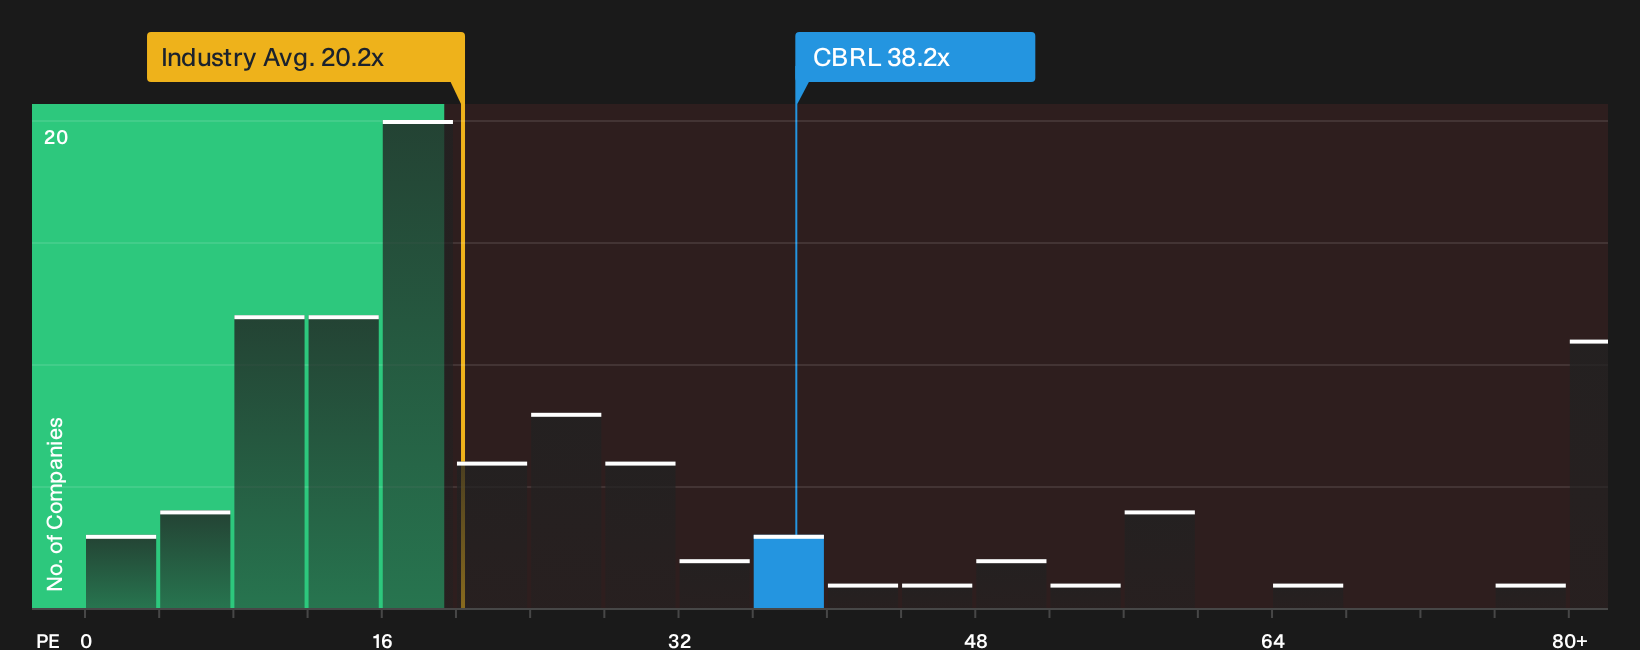
Fair value modelling presents Cracker Barrel Old Country Store as roughly in line with a $45.00 target, yet the current P/E of 38.2x tells a tougher story. That ratio sits well above the fair ratio of 25.9x, the US Hospitality average of 20.3x, and a 33.1x peer average. For anyone watching valuation risk, the key question is whether earnings can grow fast enough to close that gap before the multiple compresses.
For a deeper look at what the numbers imply at different earnings levels, you can track how this valuation compares in our detailed multiple breakdown, then decide which side of the argument feels more realistic for you. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone on Cracker Barrel Old Country Store has you on the fence, use that hesitation as a prompt to move quickly and review the numbers yourself. The next move belongs to you, so consider both the potential benefits and the risks through our breakdown of 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Cracker Barrel Old Country Store?
Do not stop with Cracker Barrel Old Country Store. Cast a wider net using focused stock lists that can surface opportunities you might otherwise overlook.
- Spot potential turnaround plays early by scanning 7 elite penny stocks with strong financials that already show signs of financial strength rather than just hype.
- Zero in on resilient balance sheets through our list of solid balance sheet and fundamentals (23 results) and stress test how these businesses might hold up when conditions change.
- Hunt for quality at a discount by reviewing the 17 high quality undiscovered gems that pair solid fundamentals with limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com