
How Investors Are Reacting To Lazard (LAZ) Leadership Hires
- Lazard has recently added Matt Spence to lead Defense Technology and Emerging Technology, Daniel Burton-Morgan to head North America Equity Capital Markets Advisory, and Niul Wood to oversee Industrials and Chemicals across EMEA.
- These hires deepen Lazard's sector coverage in defense tech, capital markets, and industrials, which could reshape how the firm allocates advisory resources and manages cost intensity across its expanding franchise.
- We will now see how Lazard's investment narrative could shift as it leans on Matt Spence's defense technology expertise.
Scan how Lazard’s new sector specialists compare with peers by reviewing a curated group of advisory-focused companies with resilient fundamentals in our list of solid balance sheet and fundamentals (23 results).
Lazard Investment Narrative Recap
To own Lazard, you need to be comfortable with a people heavy advisory and asset management model that is investing in new sectors and regions while margins are under pressure. Recent hiring adds more senior cost at a time when profit margins sit at 6.8% and returns over the past year have lagged both the market and Capital Markets peers.
The near term swing factor remains whether advisory and asset management pipelines convert into higher quality earnings that better cover the 5.48% dividend and support a high debt balance. If deal activity or flows stay soft, the biggest risk is that Lazard carries elevated compensation and expansion expenses without enough fee traction.
The Matt Spence appointment is directly linked to Lazard's push into defense, geopolitical and complex government related advisory work. His background across Barclays, Andreessen Horowitz and senior U.S. national security roles gives the firm deeper access to defense technology and dual use clients, an area already flagged as a focus for geopolitical and sovereign related mandates.
In terms of catalysts, this hire ties into Lazard's expansion in the Middle East, its private capital alliance in Europe and broader efforts to deepen restructuring and sponsor coverage. Execution risk is clear. Higher senior headcount can weigh on net margins if transaction volumes, asset management inflows and new mandates do not increase quickly enough to match the extra fixed compensation load.
Lazard's current analyst narrative points to revenues of US$4.7b and earnings of US$621.6m by 2029, anchored on 13.7% yearly revenue growth and an earnings increase of about US$402.6m from US$219.0m today.
Uncover why Lazard's fair value indicates a 30% potential upside to its current price. This opportunity could narrow quickly.
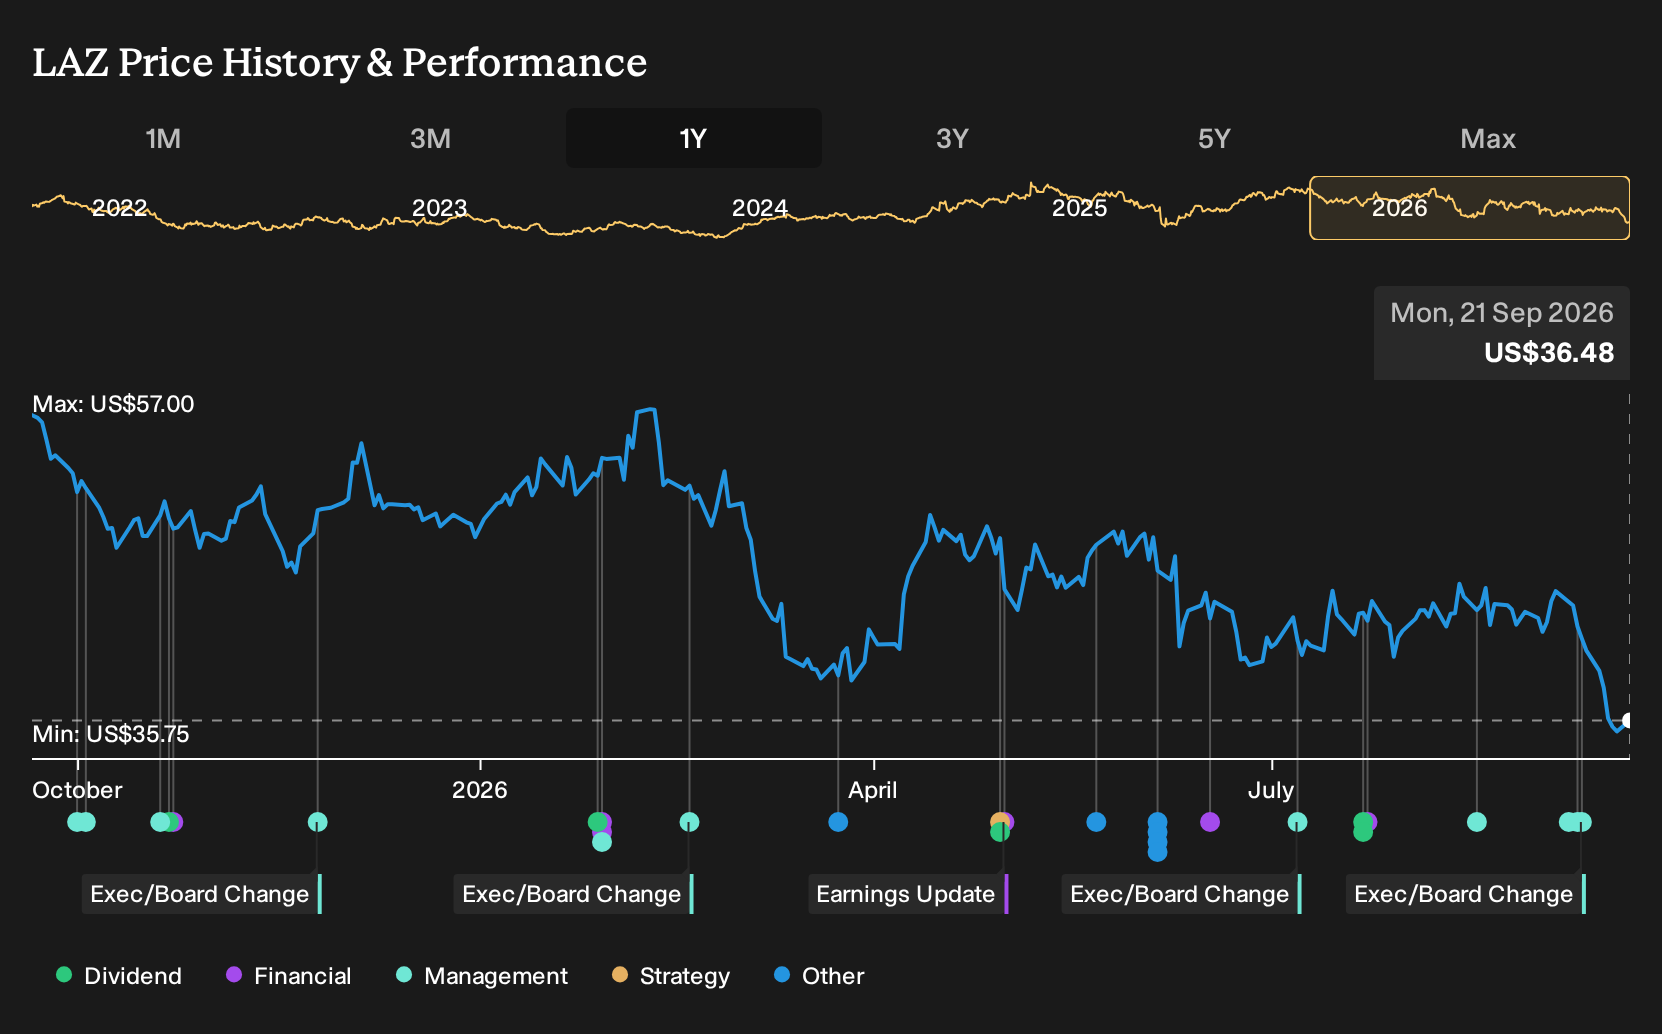
Exploring Other Perspectives
One alternate view focuses on Lazard’s fee pressure risk. The most cautious analysts already baked in only 12.1% yearly revenue growth to about US$4.5b and earnings of roughly US$633.1m by 2029 before this hiring news. That camp sees rising passive investing and fintech as bigger threats. You can compare both narratives and decide which feels closer to your own expectations.
Explore 4 other Lazard fair value estimates, including one that suggests as much as 18% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lazard research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lazard. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lazard's overall financial health at a glance.
Looking for more Lazard-like investment ideas?
If Lazard has sharpened your focus on quality, income and resilience, it can help to widen the lens and compare it with other companies that share similar financial strengths or income profiles.
- For investors who want a margin of safety backed by fundamentals, review a curated pool of companies trading on compelling metrics in our 30 high quality undervalued stocks.
- If reliable income matters to you, scan a selection of businesses that combine higher dividend yields with robust payout support in our 7 dividend fortresses.
- When capital preservation comes first, filter for companies that pair durable earnings with measured risk profiles through our 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com