
3 Great AI Stocks With P E Ratios Under 29
AI buzz is back on front pages after markets saw a lift as new consumer agents like Meta’s Muse grabbed attention and helped pull tech stocks higher. Excitement is clustering around companies that build the chips, cloud plumbing and software behind these tools. This article walks through three undervalued AI stocks from our screener that are tightly linked to this trend and may merit a closer look.
The three stocks covered below are only a sample, and the full screen surfaced 131 more listed AI players with equally compelling narratives that are not discussed here. To identify potential opportunities across chips, cloud and software tied to the ChatGPT and AI buildout, head straight to the Undervalued Artificial Intelligence/ AI Stocks screener.
NVIDIA (NVDA)
NVIDIA is one of the best-known hardware plays on the AI buildout because its compute platforms such as data center GPUs and DGX systems power many large language models, while its wider graphics and automotive lines keep the business tied to gaming and cars.
NVIDIA generates about US$275.4b from its Compute & Networking segment and roughly US$27.6b from Graphics, highlighting how data-center AI hardware now dominates its mix. The group’s value on the market sits around US$5,367.2b.
NVIDIA is a focused expression of the AI infrastructure theme, but its long-term edge still depends on whether developers continue to build on its software and hardware stack.
"Uptake of an open-source, cheaper, or better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
Everything from pricing power on high-end GPUs to the durability of those strong margins hinges on how that hidden competitive pressure evolves.
That pressure is only half the story, and the full narrative for NVIDIA maps how Nvidia's AI moat, capital needs and competitive threats could be decoupling from the headline GPU hype.
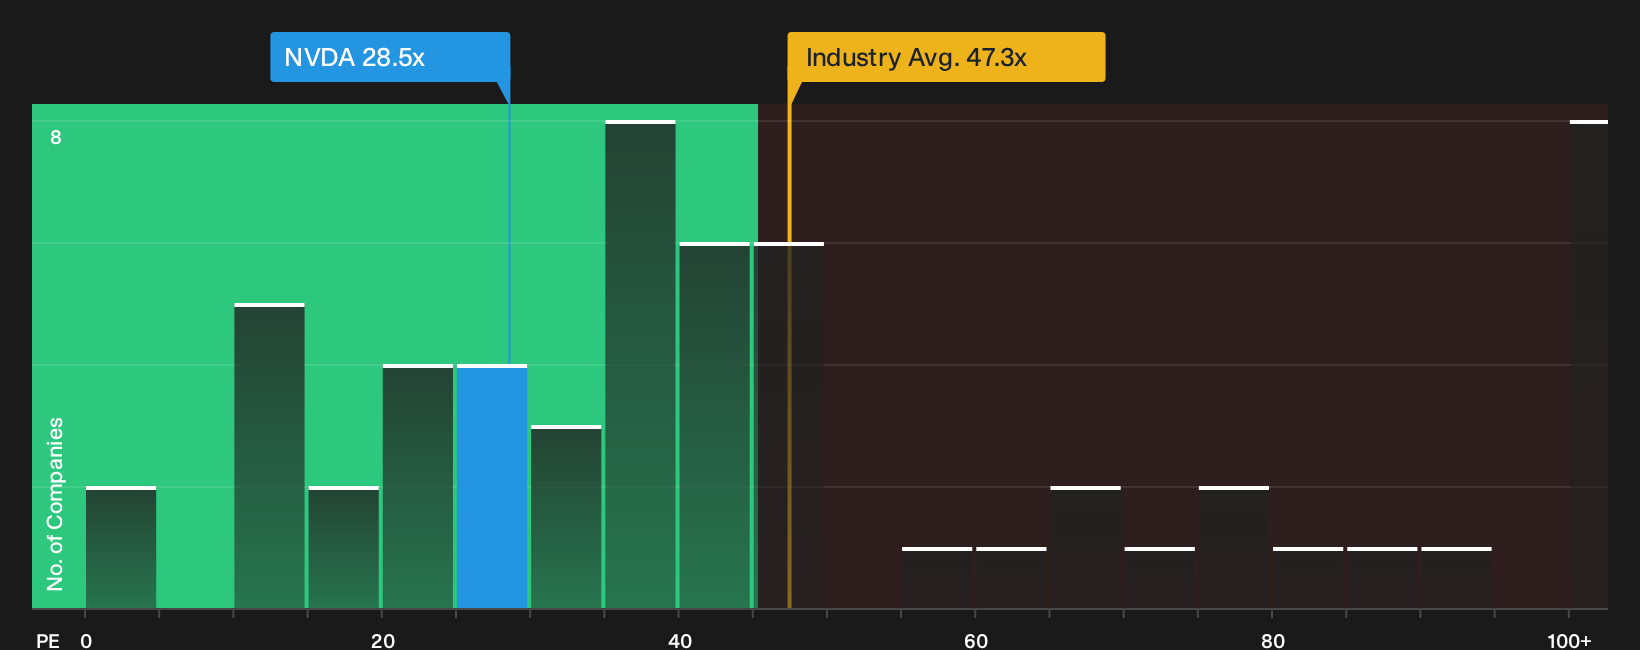
Adobe (ADBE)
Adobe leans into the AI theme through Firefly and other generative tools woven into Creative Cloud and Document Cloud, turning long-standing creative and PDF software into AI-assisted workflows for designers, marketers, and enterprises.
Adobe Inc. builds creative, document, and customer experience software that now embeds generative AI into tools like Photoshop, Acrobat, and Experience Cloud. The business is valued by the market at about US$98.9b.
"A significant portion of the bear case rests on the idea that open-source or third-party models will eventually outperform Adobe’s proprietary models. However, this ignores the "Commercial Safety" requirement of the Fortune 500."
What happens to Adobe’s AI story if a single assumption about how large clients are willing to pay for that safety net shifts?
That hinges on how resilient Adobe’s pricing power and “Commercial Safety” pitch really are, and the full narrative for Adobe shows where risks and upside could be accelerating.
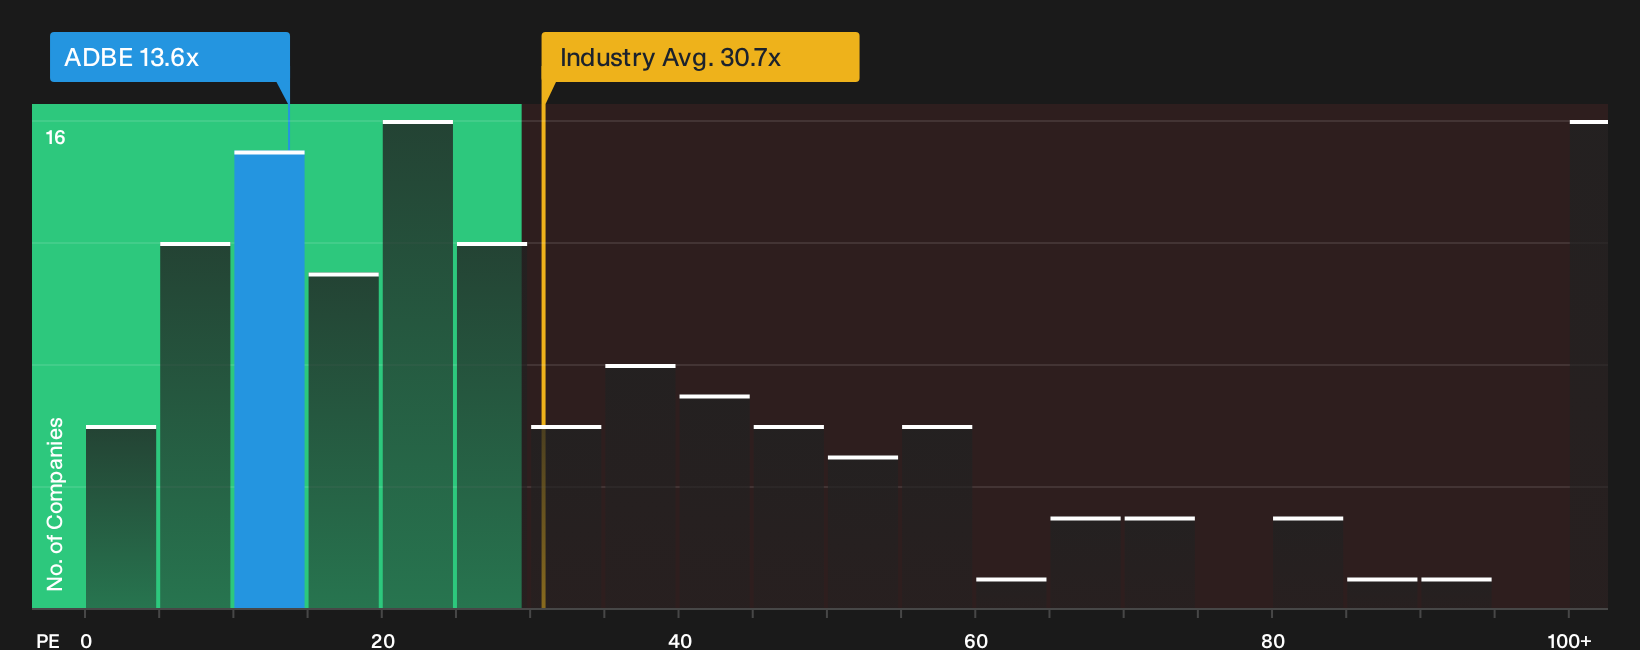
Alphabet (GOOGL)
Alphabet gives this AI screener direct exposure to enterprise-grade tools like Gemini and Vertex AI through Google Cloud, while most money still comes from search, YouTube, and other Google Services rather than pure AI infrastructure.
Alphabet Inc. runs Google’s ads, search, YouTube, Android, and other consumer platforms while Google Cloud powers its AI push through Vertex AI and Gemini. The group generated about US$367.1b from Google Services, US$77.6b from Google Cloud, and US$1.5b from Other Bets. The market values Alphabet at roughly US$4,246.5b.
"Google Cloud has gone from “meh” to money-maker, now #3 globally behind AWS and Azure, with over 11% market share and including AI‑first services like Vertex AI, Duet AI, and infrastructure tools deeply integrated into BigQuery and Workspace."
What really matters now is how one quiet shift in enterprise AI demand filters through to margins on that growing cloud AI backlog.
That cloud AI shift is exactly what the full narrative for Alphabet unpacks, showing how Alphabet’s search cash flows and cloud ambitions could be quietly rewiring the long term story.

Seeking Fresh Alternatives Before They Fly
Market momentum moves fast and the sharpest breakouts rarely wait. Scan fresh ideas that are under the radar for now, before the crowd catches up, and consider acting while they remain less noticed.
- Look for income-oriented opportunities by checking out 7 dividend fortresses that focus on cash-generating payers while yields are still high and attention is directed elsewhere.
- Explore earlier-stage opportunities with 7 elite penny stocks with strong financials offering curated smaller caps that combine stronger fundamentals with potential price momentum before they become widely followed.
- Monitor developments in automation using 95 robotics and automation stocks featuring selected businesses involved in the hardware and software behind robotics while overall interest is still developing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com