
ChemoMetec (CPSE:CHEMM) Could Be 18% Undervalued Following Full Year Results And Guidance
Why ChemoMetec’s latest earnings matter for shareholders
ChemoMetec (CPSE:CHEMM) just posted full year 2025/26 results alongside fresh guidance, with higher sales, increased net income and a new revenue range for 2026/27 that is now in focus for investors.
The recent results came after a sharp rebound in ChemoMetec’s 90 day share price return of 41.51%. However, the year to date share price return is still down 22.16%, and the 1 year total shareholder return has declined 19.09%. By contrast, the 3 year total shareholder return of 67.35% points to a much stronger longer run record despite earlier setbacks over five years.
Scan how ChemoMetec’s earnings shift fits into the wider opportunities in life sciences by checking our hand picked 131 healthcare AI stocks with exposure to data driven diagnostics and research tools.
Bulls point to ChemoMetec’s rising earnings and fresh guidance, while bears highlight the share price slide over one year. Which side looks closer to fair value once the current valuation is unpacked?
Most Popular Narrative: 18% Undervalued
ChemoMetec’s most followed valuation story points to a fair value of DKK638.33 per share compared with the last close at DKK525, so the gap between price and narrative fair value is now central to the debate.
Integration of XcytoMatic systems with large automation partners such as Hamilton, Tecan and Roche positions ChemoMetec within broader automated workflows, which can expand the potential instrument base and support margins if software and systems sales scale.
Investment of around DKK 120 million in product development for fiscal 2026 to 2027, focused on automation, sample management and XM Octopus fleet management software, can build higher value system and software revenue streams that may support EBITDA margins over time.
See why 1 investors see ChemoMetec as 18% undervalued.
Result: Fair Value of DKK638.33 (UNDERVALUED)
Still, the ChemoMetec story can break if heavy R&D and growth spending squeeze free cash flow, or if new XM and NC-203 instruments do not drive recurring consumables usage.
Find out about the key risks to this ChemoMetec narrative.
Another view on ChemoMetec’s valuation
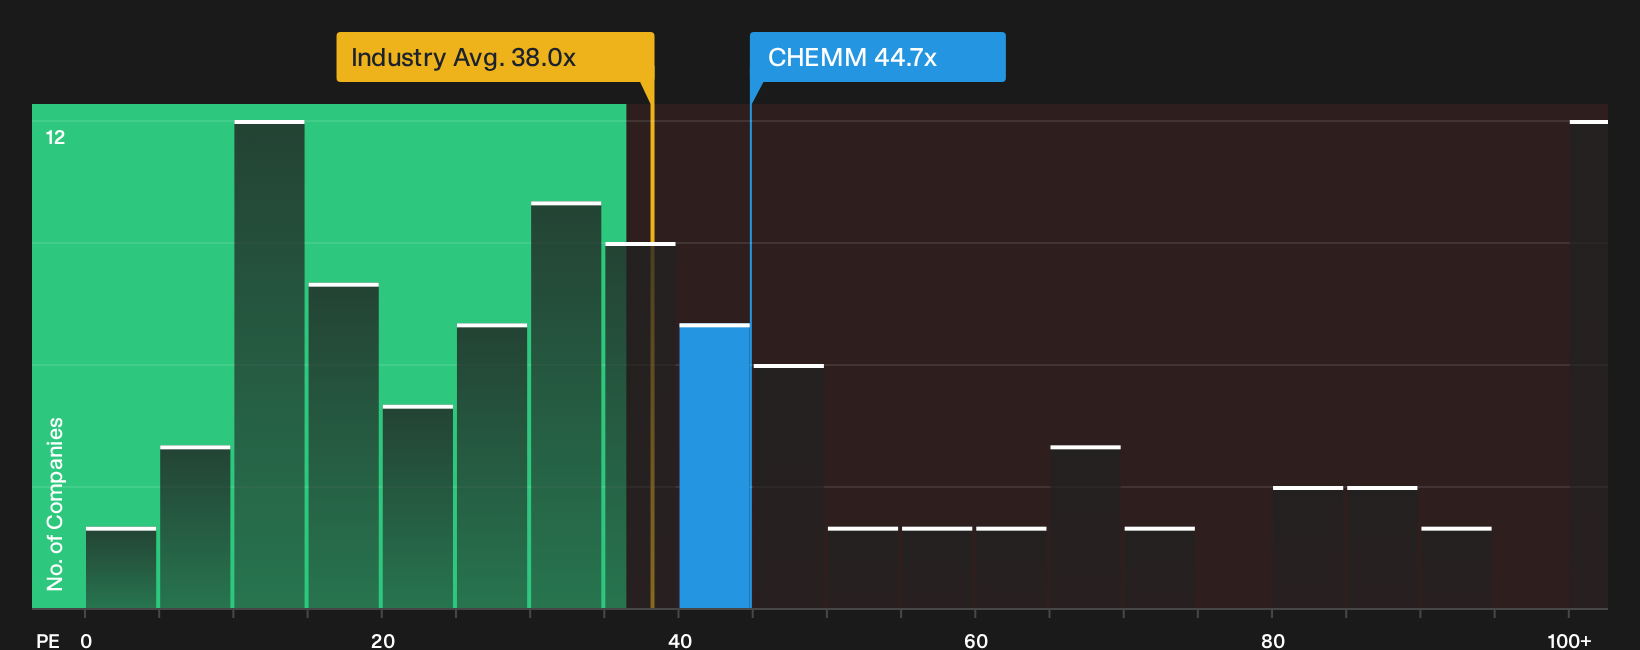
Analyst narratives frame ChemoMetec as 18% undervalued, yet the P/E of 44.7x tells a tougher story. That ratio sits above the Life Sciences industry on 37.8x and more than double the fair ratio of 20.6x, which suggests meaningful valuation risk if sentiment cools.
Before leaning on this richer earnings multiple, it is worth checking how that price stacks up against the detailed valuation work in our models, including whether the market could drift closer to the fair ratio over time. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed feelings on ChemoMetec after these results is a healthy place to start, yet the real edge comes from digging into the detail yourself and acting while the fresh data is still front of mind. To weigh the balance between the concerns and the potential upside, go straight to the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond ChemoMetec?
If ChemoMetec has sharpened your focus, do not stop here. Broader research now can protect you from regret when the next opportunity emerges.
- Target potential mispricings by scanning a 174 high quality undervalued stocks that filters for quality fundamentals at prices that may not fully reflect underlying strength.
- Strengthen the income side of your portfolio by reviewing 162 dividend fortresses that combine higher yields with the potential for steadier payout records.
- Reduce portfolio stress by focusing on 229 resilient stocks with low risk scores that screen for resilient balance sheets and lower historical volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com