
e.l.f. Beauty (ELF) Could Be 4% Undervalued On Naturium’s Sephora Expansion
Naturium’s rollout into Sephora stores across Canada and Mexico put e.l.f. Beauty (ELF) back in focus for investors, as the skincare label reaches new North American shoppers through a larger retail footprint.
Recent trading has been choppy for e.l.f. Beauty, with the 90‑day share price return of 54.02% contrasting with a 30‑day share price decline of 4.07%. The 1‑year total shareholder return is down 28.79%, but the 5‑year total shareholder return is up 226.08%, suggesting long term holders have still seen strong gains even as momentum has cooled in the past month around news such as Naturium’s broader Sephora rollout.
Spot similar beauty and personal care stories playing out across our hand-picked 17 high quality undiscovered gems, which feature fundamentals to support their momentum.e.l.f. Beauty now trades about 4% below the average analyst target and roughly 10% under one estimate of fair value, yet the stock only recently cooled after a strong 90 day run. Is that discount signaling an opportunity, or is it a sign of justified caution on a volatile story?
Most Popular Narrative: 4% Undervalued
On the narrative view, e.l.f. Beauty’s fair value sits at $101.75, modestly above the last close of $97.79. This puts the stock on the edge of a perceived discount while still tethered closely to current pricing.
The expansion into new international markets and rapid growth in existing ones (e.g., 30% international net sales growth, top rankings in new geographies, global Sephora rollout) provides significant runway for future revenue growth and increased diversification, which is likely under-appreciated by the market.
See why 106 investors see e.l.f. Beauty as 4% undervalued.
Result: Fair Value of $101.75 (UNDERVALUED)
Still, the e.l.f. Beauty story carries clear pressure points, including heavy reliance on Chinese manufacturing and rising competition in affordable, clean beauty, which could squeeze margins.
Find out about the key risks to this e.l.f. Beauty narrative.
Another View On e.l.f. Beauty’s Valuation
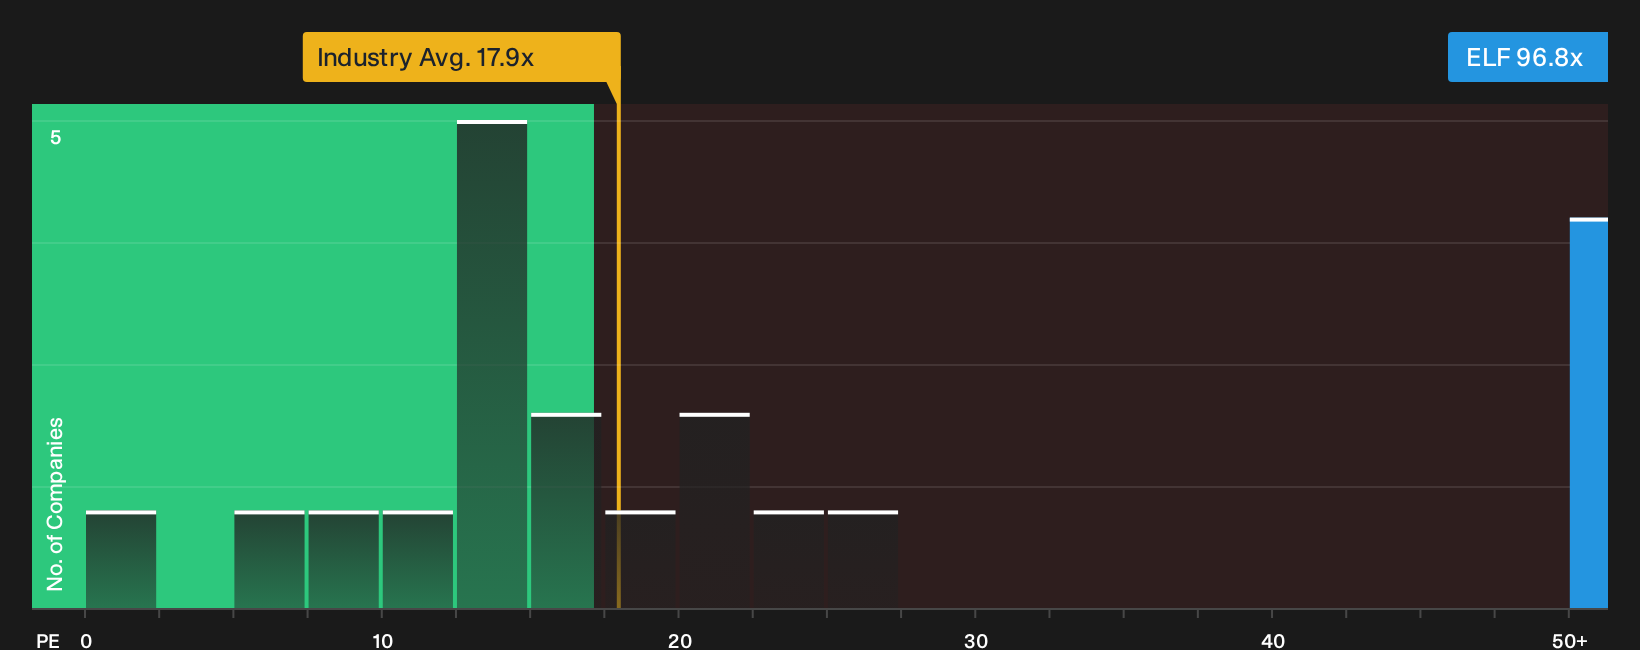
There is a different read on e.l.f. Beauty once the current P/E is put under the microscope. The stock trades on 96.8x earnings, compared with a peer average of 22.7x, an industry average of 17.9x, and a fair ratio estimate of 24.9x. This points to a rich earnings multiple that could limit upside if sentiment cools.
That sort of gap can persist, especially for a high growth story. It also raises a question for anyone following ELF: Is the current premium something you are comfortable paying, or are you relying on the market to keep rewarding the story at this level?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on e.l.f. Beauty’s valuation and momentum only matter if you act on them. Weigh the upside against the pressure points by checking the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond e.l.f. Beauty?
Do not stop with one ticker when you can scan dozens of fresh opportunities tailored to different risk levels, cash flows, and income goals in minutes.
- Target potential mispricings by running through the 30 high quality undervalued stocks to filter for companies with quality fundamentals trading at a discount.
- Lock in income-focused opportunities using the 7 dividend fortresses to highlight businesses offering higher yields with an emphasis on sustainability.
- Protect your downside by reviewing the 30 resilient stocks with low risk scores to surface resilient businesses with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com