
Compagnie de l'Odet (ENXTPA:ODET), Why Is Fresh Attention Building Now?
Compagnie de l'Odet (ENXTPA:ODET) has put two big signals in front of investors. Half year 2026 results showed higher sales but a sharply lower net profit, alongside plans for a €2.5b exceptional interim dividend linked to Bolloré SE’s earlier payout.
Recent trading suggests investors are still processing those signals. The share price is €1,292.0, with a 90 day share price return that fell 13.29% and a 1 year total shareholder return that declined 6.35%. This points to fading momentum despite the exceptional dividend announcement and profit drop.
Compare how Compagnie de l'Odet's setup stacks against other potential opportunities by scanning our curated 174 high quality undervalued stocks with solid fundamentals and room for sentiment to shift.
Compagnie de l'Odet now trades lower even as a €2.5b cash return approaches. That mix raises a simple question: Is most of the upside already in the payout, or does the current valuation still leave room ahead?
Price-to-Earnings of 52.1x: Is it justified for Compagnie de l'Odet?
On simple optics, Compagnie de l'Odet looks expensive. The shares last closed at €1,292, and the stock trades on a P/E of 52.1x compared with a peer average of 18.4x.
The P/E ratio compares the current share price to earnings per share. For a diversified group like Compagnie de l'Odet, active in oil distribution, media and industrial activities, it effectively reflects what investors are willing to pay today for each euro of reported profit across those segments.
A P/E that sits several turns above peers generally means the market is placing a richer value on the company’s earnings profile. This can be because it views those earnings as higher quality or less cyclical, or because it is comfortable with a lower current profit yield. Here, the data flags that ODET has high quality earnings and is trading just 0.8% below an internal fair value estimate. However, it also reports a low 0.9% return on equity and a sharp compression in net margin from 36.2% to 3.5%, which can make such a high multiple harder to defend for some investors.
The gap against the wider sector is even clearer. ODET’s 52.1x P/E is described as expensive relative both to direct peers on 18.4x and to the broader European logistics industry on 22.4x. The current tag implies investors are paying more than twice the peer earnings multiple for this group’s profit stream.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 52.1x (OVERVALUED)
Still, the sharply lower net margin and the modest 3-year total return decline of 8.05% could quickly pressure Compagnie de l'Odet if sentiment weakens further.
Find out about the key risks to this Compagnie de l'Odet narrative.
Another View on Compagnie de l'Odet's Value
The P/E screen paints Compagnie de l'Odet as expensive, yet the SWS DCF model points in a softer direction. At €1,292 the shares sit about 0.8% below an estimated future cash flow value of €1,302.22. That is a tiny gap. Is this really mispricing or just noise around a fair value line?
Look into how the SWS DCF model arrives at its fair value.
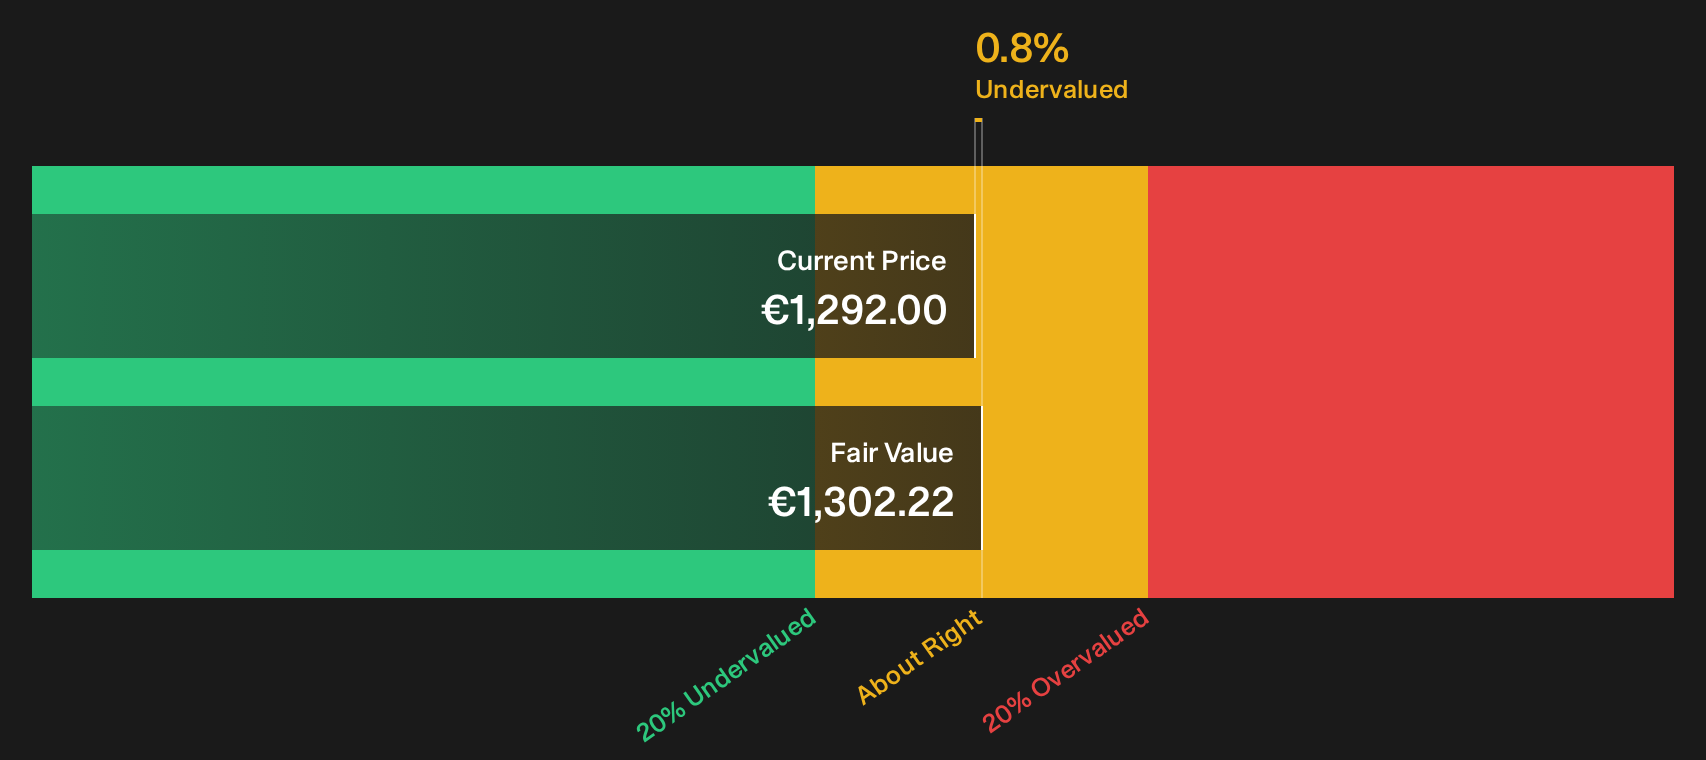
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Compagnie de l'Odet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 174 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Compagnie de l'Odet so far. If that leaves you on the fence, move quickly, pull up the facts, and weigh both sides through the 1 key reward and 1 important warning sign.
Looking for more investment ideas beyond Compagnie de l'Odet?
If Compagnie de l'Odet leaves you unsure, you could broaden your watchlist with a few focused screens that highlight different types of opportunities across the market.
- Target dependable income by scanning companies that aim for strong cash generation and resilient payouts through the 161 dividend fortresses.
- Look for potential mispricings by filtering for financially healthy businesses trading below their implied worth using the 174 high quality undervalued stocks.
- Prioritise capital preservation first and potential upside second by focusing on resilient businesses with stronger risk profiles via the 229 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com