
What Garmin's Drive Navigator Launch Means For Shareholders
- Garmin recently launched redesigned Garmin Drive GPS navigators featuring 7.1 inch and 8.8 inch ultrawide high resolution displays, an intuitive map-centric interface, and safety alerts, with prices ranging from US$299.99 to US$349.99.
- The new Drive line integrates real-time traffic, weather, EV charging availability, and TripAdvisor content into a single device, which could influence how Garmin balances hardware sales with connected software features in its auto-related segment.
- We now look at how Garmin's investment narrative intersects with this enhanced Drive feature set centered on EV charging visibility.
Scan beyond Garmin and see which other hardware focused auto-tech stocks are quietly repositioning around connected cars and EV charging in our curated 88 AI infrastructure stocks
Garmin Investment Narrative Recap
To own Garmin, you need to believe the mix is steadily tilting toward higher margin fitness devices, aviation systems and services like Garmin Connect+, while the weaker Outdoor and Auto OEM pieces remain manageable. The new Drive navigator launch sits inside that softer auto related bucket, so it helps product depth but does not obviously change the near term earnings story.
The key short term swing factor is how far Outdoor and Auto OEM softness goes and how much higher memory costs in 2026 and 2027 pressure gross margin. If consumer auto demand for stand alone GPS units disappoints, the refreshed Drive line may only partially cushion that segment level drag.
The clearest linked development is Garmin Connect+, which turns device usage into recurring software revenue. As more hardware, including Drive navigators, leans on connected features such as live traffic, weather and EV charging, the company has an opportunity to deepen paid services and keep customers inside its ecosystem.
That connection cuts both ways. Growing dependence on cloud linked functionality increases exposure to component cost inflation and data infrastructure spending at the same time Outdoor revenue has already softened and Auto OEM is expected to slip back into operating losses in the second half of 2026. Execution on subscriptions and cost control becomes central to the Garmin catalyst story around these new hardware launches.
Garmin’s current analyst script points to revenues of US$10.0b and earnings of US$2.3b by 2029, built on an assumed 9.1% yearly revenue growth rate and an earnings increase of about US$0.4b from US$1.9b today.
Uncover why Garmin's fair value indicates a 4% potential upside to its current price that may not last much longer.
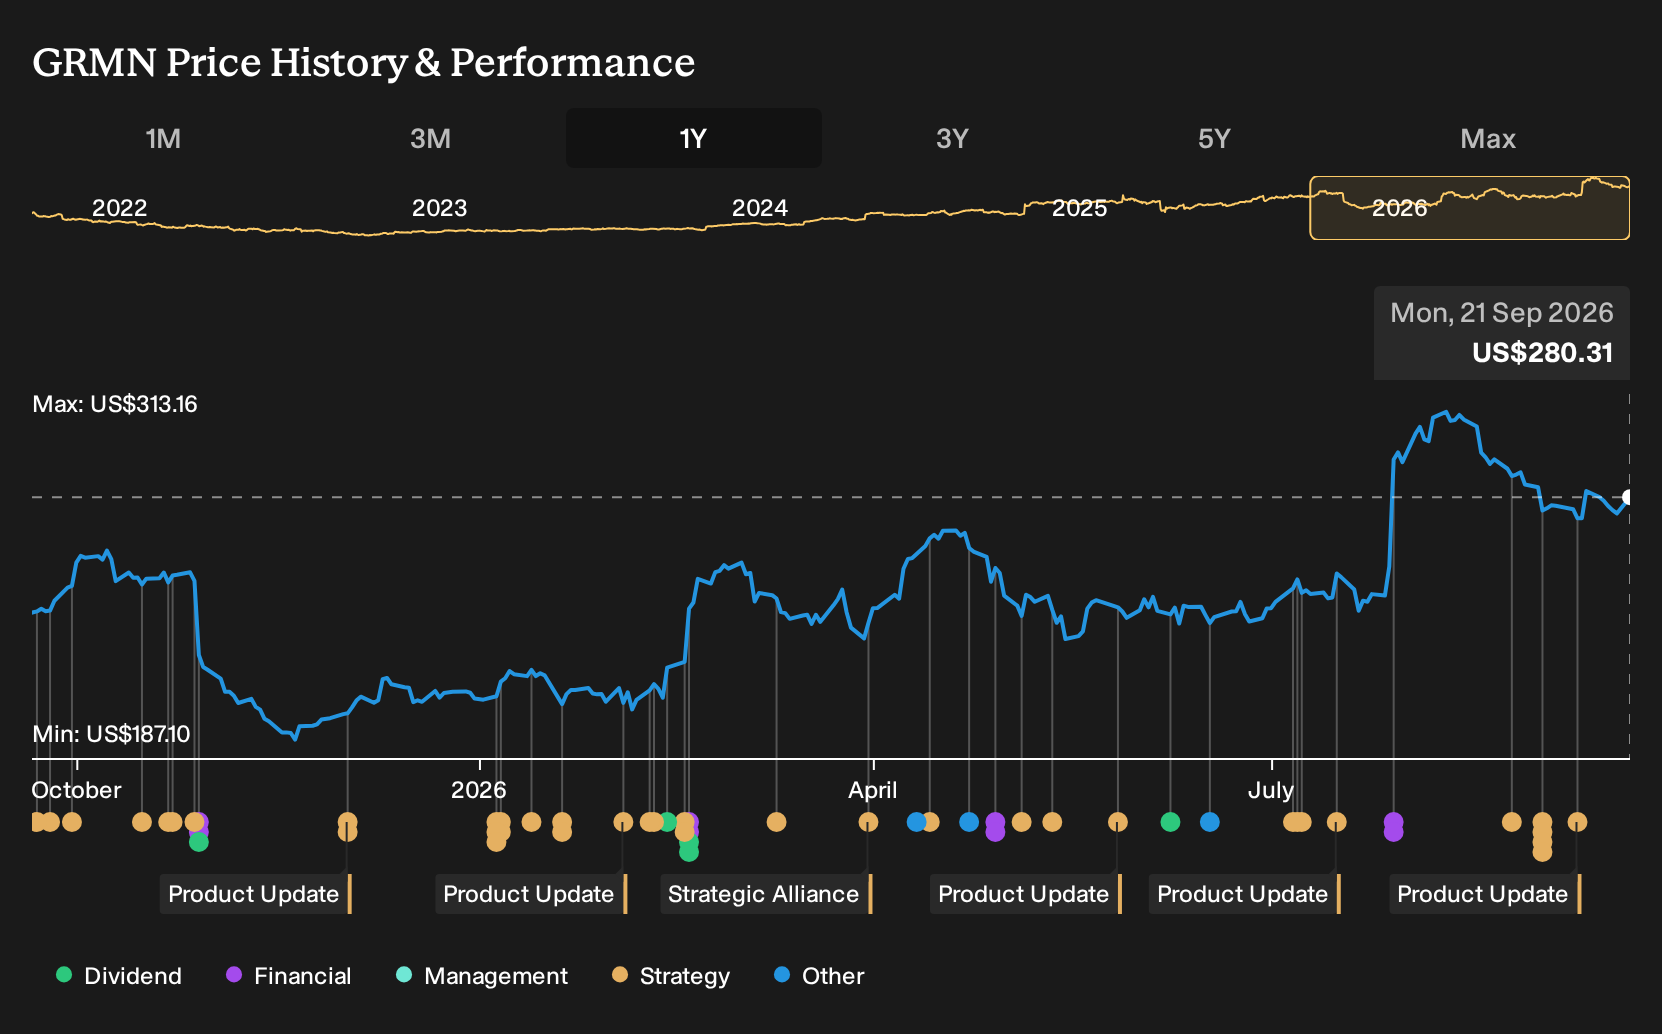
Exploring Other Perspectives
Smartphone cannibalization sits at the center of the bearish view on Garmin. The lowest analysts worry that dedicated devices like Drive will lose ground, which feeds into their lower June 2029 forecasts of US$9.4b in revenue and US$2.1b in earnings. These pre launch estimates may shift. Compare these figures with your own expectations to see how they align.
Explore 4 other Garmin fair value estimates, including one that suggests as much as 22% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Garmin research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Garmin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Garmin's overall financial health at a glance.
Looking for more Garmin sized investment ideas?
You have Garmin on your radar, so it makes sense to broaden the watchlist with other stocks that line up with the kind of balance between quality, risk and income that fits your style. The Simply Wall St Screener can help you quickly filter the market down to a manageable shortlist.
- If you are hunting for quality at a reasonable entry point, scan through 30 high quality undervalued stocks that could merit a closer look on your valuation checklist.
- If capital preservation sits higher on your priority list, filter for 30 resilient stocks with low risk scores that may suit a more cautious approach.
- If you want exposure to potentially overlooked opportunities, work through 17 high quality undiscovered gems that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com