
How Investors May Respond To RB Global (RBA) $1b Buyback Plan
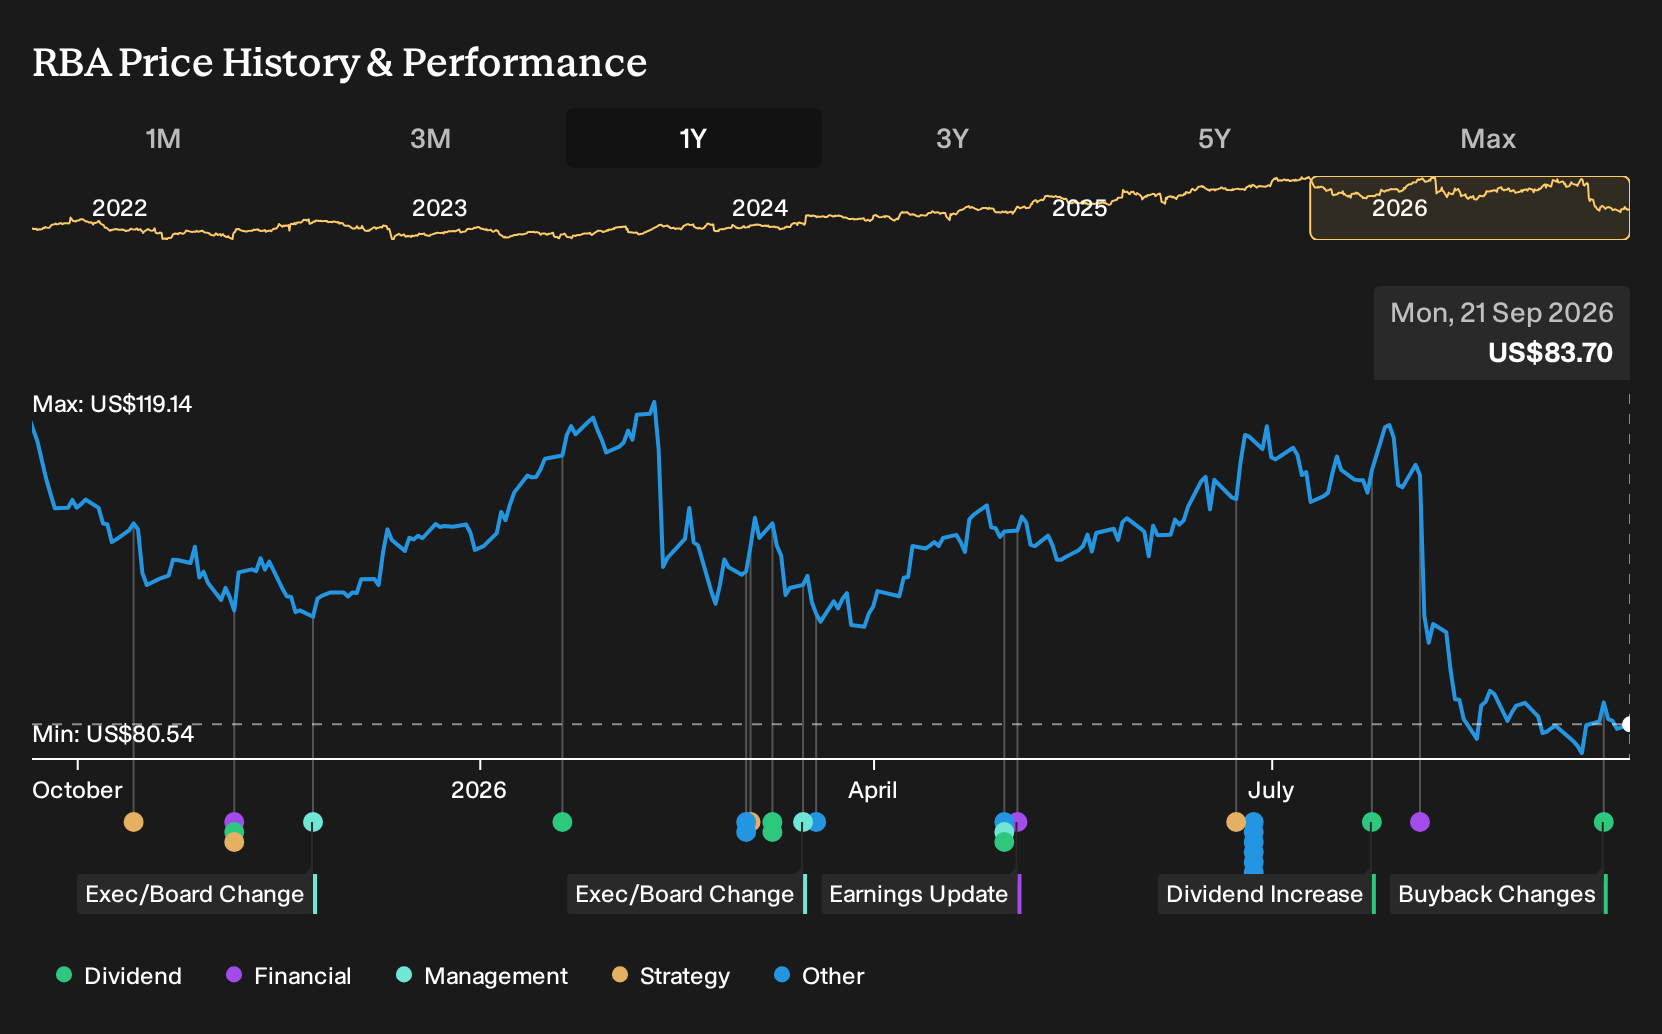
- RB Global announced that the Toronto Stock Exchange approved an amendment to its normal course issuer bid, lifting the buyback ceiling to $1 billion and allowing repurchases of up to 14,224,129 shares, or 7.6% of its issued share capital. The amended plan is effective from September 17, 2026.
- The larger buyback capacity and higher dividend together highlight RB Global's focus on returning excess cash to shareholders while maintaining flexibility to fund growth. This directly links its capital allocation choices to the underlying marketplace and services strategy that investors are watching.
- We will now examine how RB Global's investment narrative could be influenced by the expanded $1 billion share repurchase authorization.
Scan how RB Global’s larger buyback fits into a broader hunt for companies returning serious cash to investors by reviewing our curated list of 7 dividend fortresses.
RB Global Investment Narrative Recap
To own RB Global, you need to believe its global auction and digital marketplace can keep attracting more equipment and vehicle volume and deepen service use across data, financing, and logistics. The key near term swing factor is transaction activity, which is still exposed to capital spending trends, interest rates, and used equipment supply.
The increased US$1b buyback capacity does not change those operating drivers. It mainly affects capital allocation optics while the biggest operational risk stays the same. Slower volumes, rising competition from direct digital channels, or integration missteps on recent deals could pressure take rates, margins, and the growth narrative investors are tracking.
The most relevant recent development tied to this buyback is the earlier move to raise the quarterly dividend. You now have RB Global leaning on both repurchases and cash payouts. That combination signals the board sees room to return capital while still funding marketplace expansion and service investments.
For your thesis, the question is whether those cash returns are supported by durable earnings and free cash flow from auctions, IAA, and adjacent services. If macro headwinds or catastrophe volume swings hit gross transaction value, generous capital returns could meet a balance sheet that already carries a high level of debt, which keeps leverage and interest costs worth watching.
RB Global's current analyst narrative points to revenues of US$6.2b and earnings of US$934.3m by 2029, anchored on 9.3% annual revenue growth and an earnings increase of roughly US$530m from current earnings of US$403.9m.
Discover why RB Global's fair value indicates a 53% potential upside to its current price, a gap that may narrow in a relatively short period.
Exploring Other Perspectives
One alternate view on RB Global leans heavily on technology and digitization as a potential upside catalyst. The most optimistic analysts were already assuming revenue of about US$6.2b and earnings of US$958.7m by 2029, even before this larger US$1b buyback. That gap in expectations shows how widely opinions can differ. Use it as a prompt to compare multiple narratives and decide which assumptions you find more realistic if this repurchase plan reshapes future forecasts.
Explore 3 other RB Global fair value estimates, including one that suggests a potential 167% increase from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RB Global research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RB Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RB Global's overall financial health at a glance.
Looking for more RB Global style investment ideas?
If the RB Global story has you thinking about where else steady cash returns, balance sheet strength, or overlooked quality might show up, the Simply Wall St Screener can help you quickly filter the wider market to match the kind of profile you want to research next.
- For investors who like the combination of income and resilience, scan a curated set of higher yield payers through our 7 dividend fortresses.
- If capital preservation and smoother ride potential matter most to you, sort through a group of companies with stronger risk profiles using the 30 resilient stocks with low risk scores.
- When you want to get ahead of the crowd and research quality stories before they are widely followed, start with the 17 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com