
Is FTSE All World Index Addition Altering The Investment Case For Finning International Stock?
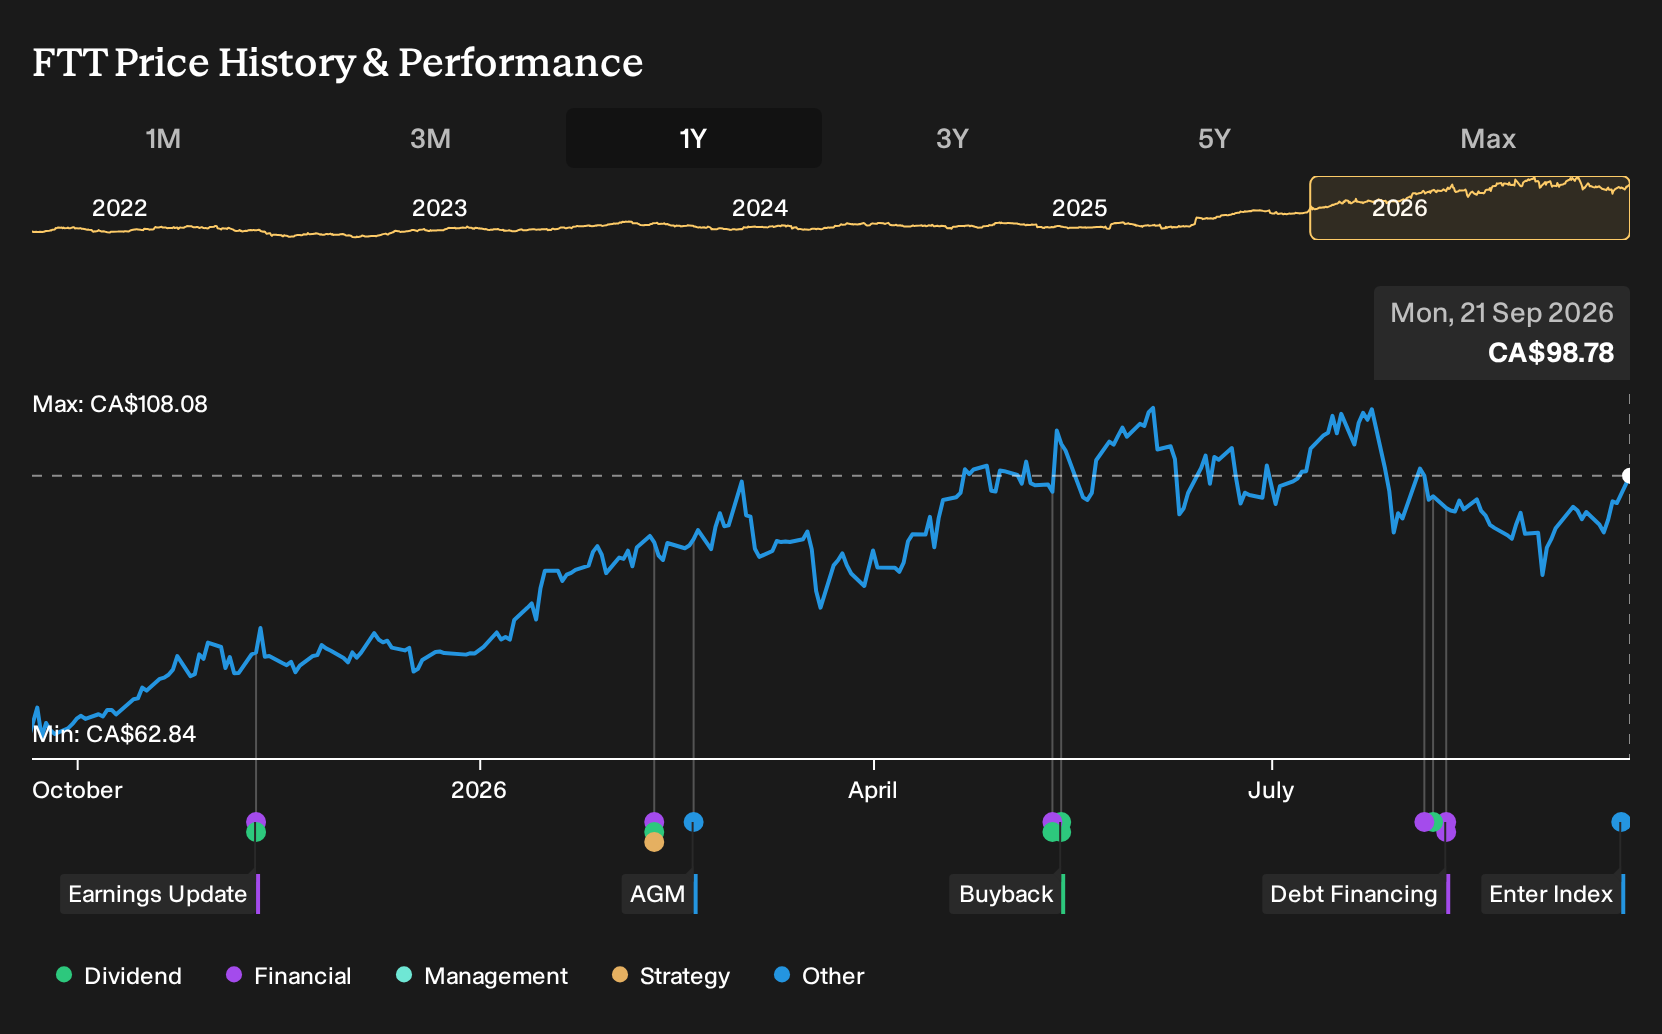
- Finning International Inc. was added to the FTSE All-World Index (USD) on 19 September 2026, marking its inclusion in a major global equity benchmark.
- This new index membership may redirect passive fund flows toward Finning International and increase institutional attention on its equipment and product support operations.
- The following section considers how Finning International's investment narrative could be influenced by its addition to the FTSE All-World Index.
Finning International Investment Narrative Recap
To own Finning International, you need to be comfortable with a heavy equipment cycle that leans on a CA$11.2b top line and a broad footprint across Canada, South America, and the UK and Ireland. The thesis rests on converting a large new equipment and Power Systems backlog into recurring product support work. The FTSE All-World Index inclusion may raise visibility, but it does not change how well the fleets in the field are being used.
The most important near term swing factor is still execution on that backlog while keeping labor and project costs under control, particularly in South America and Power Systems. The biggest risk sits in margin pressure and working capital build, where higher inventory and weaker used equipment demand could keep cash conversion tight regardless of higher institutional interest from the index news.
There is no fresh operational update tied directly to this FTSE All-World Index move. The most relevant context is the existing backlog story already in place for Finning International. New equipment orders of CA$3b and a CA$1b Power Systems book position the business with substantial future delivery commitments. The key question is how effectively these orders translate into higher margin product support and service activity over time.
That same backlog brings execution risk. Large, lumpy power projects carry higher cost intensity and require continued investment in technicians and capacity. If labor shortages, union negotiations, or used equipment volatility persist, the firm could see net margins and free cash flow pressured even as it gains index-driven attention. For you as an investor, the focus is on confidence in management’s ability to run this operationally tight, not simply on its new benchmark membership.
Finning International's current analyst story points to revenues of CA$12.3b and earnings of CA$848.2m by 2029, built on assumed yearly top line growth of 4.9% and an earnings increase of about CA$330m from CA$518.0m today.
Uncover why Finning International's fair value indicates a 21% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between CA$114.87 and CA$119.89, which signals very similar modelling of Finning International despite different individual viewpoints. Those pre index-add views sit beside real execution risks in South America, Power Systems and used equipment, giving you clear reason to compare multiple perspectives before acting.
Explore another Finning International fair value estimate, including one that suggests as much as 21% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Finning International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Finning International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Finning International's overall financial health at a glance.
Looking For More Ideas Beyond Finning International?
Once you have formed a view on Finning International, it can help to stack that thesis against other opportunities using the Simply Wall St Screener. You get a clearer sense of what else is out there, how different balance sheets and cash profiles compare, and where your next hour of research time might be better spent.
- If capital preservation comes first for you, start with resilient businesses that skew toward stability using the 8 resilient stocks with low risk scores to frame your watchlist around durability rather than excitement.
- For investors hunting for mispriced quality, line up candidates that mix solid fundamentals with appealing valuations through the 9 high quality undiscovered gems and see which ones deserve deeper work.
- If you want to pair income with balance sheet strength, focus on companies that combine healthy payout profiles with robust financial footing by scanning the 1 dividend fortresses as a filter for potential income ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com