
September 2026's European Growth Companies With High Insider Ownership
In September 2026, European markets have been navigating a complex landscape marked by volatile energy prices and inflationary pressures, with the STOXX Europe 600 Index experiencing fluctuations due to geopolitical tensions and monetary policy shifts. Amidst this backdrop, growth companies with high insider ownership can offer unique insights into potential resilience and alignment of interests between management and shareholders.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| MilDef Group (OM:MILDEF) | 10.3% | 31.1% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 58.6% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| CD Projekt Red (WSE:CDR) | 35.2% | 47.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 29.8% |
We'll examine a selection from our screener results.
TTS (Transport Trade Services) (BVB:TTS)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: TTS (Transport Trade Services) S.A. is a Romanian company that offers freight forwarding services and has a market cap of RON1.23 billion.
Operations: The company's revenue is derived from three main segments: Forwarding (RON443.34 million), Port Operations (RON136.10 million), and River Transport (RON299.61 million).
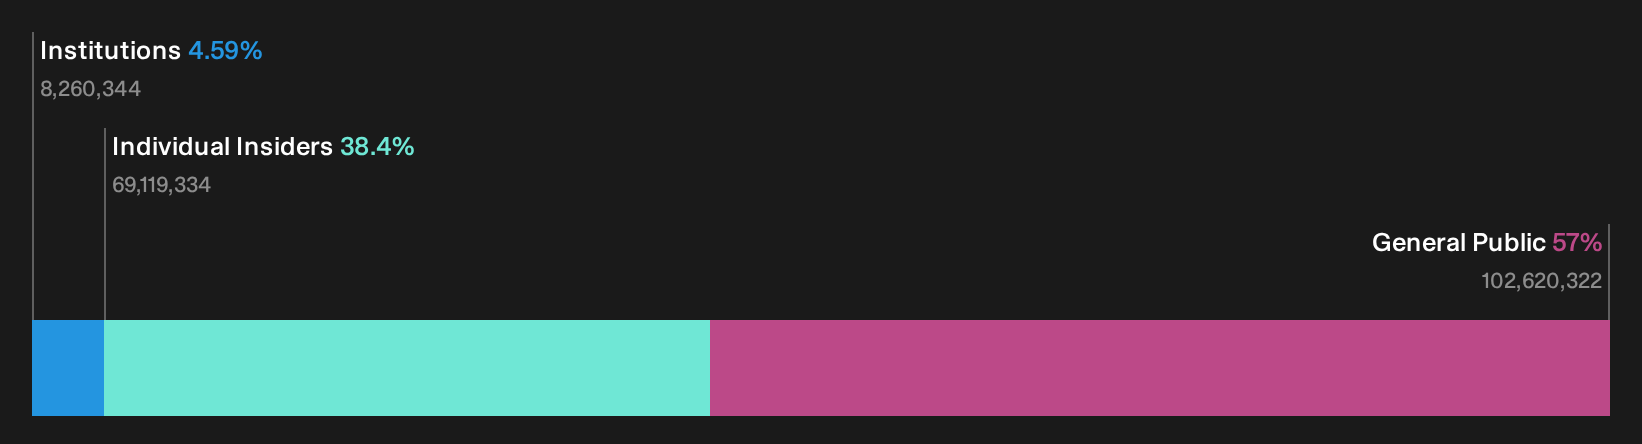
Insider Ownership: 38.4%
Earnings Growth Forecast: 57.6% p.a.
Transport Trade Services (TTS) shows promising growth potential with earnings forecasted to grow significantly at 57.6% annually, outpacing the Romanian market's expected 10.2%. Recent financial results highlight a return to profitability, reporting RON 4.36 million in net income for H1 2026 compared to a loss last year. Despite trading at a discount of 16.4% below estimated fair value, its Return on Equity is projected to remain low at 7.4%.
- Delve into the full analysis future growth report here for a deeper understanding of TTS (Transport Trade Services).
- Insights from our recent valuation report point to the potential overvaluation of TTS (Transport Trade Services) shares in the market.
BTS Group (OM:BTS B)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: BTS Group AB (publ) is a professional services firm with operations across North America, Europe, Latin America, Africa, the Middle East, and other international markets, with a market cap of approximately SEK4.01 billion.
Operations: The company's revenue segments are comprised of BTS North America at SEK1.31 billion, BTS Europe at SEK700.62 million, BTS Other Markets at SEK843.78 million, and Advantage Performance Group (APG) at SEK94.54 million.
Insider Ownership: 32.6%
Earnings Growth Forecast: 39.5% p.a.
BTS Group's earnings are expected to grow significantly at 39.5% annually, surpassing the Swedish market's 7.4%. Despite trading at a substantial discount of 54.3% below fair value, recent financials show challenges with a net loss of SEK 1.14 million in Q2 2026 compared to last year's profit. Revenue growth is forecasted at 7.8% annually, outpacing the market decline but remains impacted by large one-off items affecting earnings quality and an unstable dividend history.
- Click here and access our complete growth analysis report to understand the dynamics of BTS Group.
- Our comprehensive valuation report raises the possibility that BTS Group is priced higher than what may be justified by its financials.

Creotech Instruments (WSE:CRI)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Creotech Instruments S.A. is a Polish company specializing in the manufacture and sale of satellites, satellite systems, and subsystems, with a market capitalization of PLN2.17 billion.
Operations: The company's revenue is primarily derived from Space Projects (PLN142.46 million), Electronics Production (PLN1.72 million), and Satellite data and Unmanned Aerial Vehicle technologies (PLN2.13 million).
Insider Ownership: 31.1%
Earnings Growth Forecast: 62.4% p.a.
Creotech Instruments is poised for substantial growth, with revenue expected to rise 41.3% annually, outpacing the Polish market's 5%. Earnings are projected to grow significantly at 62.41% per year, surpassing the market's 9.6%. Despite recent shareholder dilution and high share price volatility, it trades at a notable discount of 83.8% below its estimated fair value. Recent presentations at the Pekao Annual Emerging Europe Investment Conference highlight its strategic positioning in the sector.
- Dive into the specifics of Creotech Instruments here with our thorough growth forecast report.
- The valuation report we've compiled suggests that Creotech Instruments' current price could be quite moderate.

Next Steps
- Navigate through the entire inventory of 214 Fast Growing European Companies With High Insider Ownership here.
- Looking For Alternative Opportunities? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com