
3 Indian Stocks Trading At Least 42% Below Fair Value
With India and New Zealand’s new free trade agreement set to kick in next month, investors are watching how export focused Indian businesses might convert growing cross border demand into hard cash. When the headlines feel crowded, quietly cash generative companies that trade below their estimated fair value can look compelling. This article breaks down three Indian stocks where current cash flow pricing may interest value oriented investors.
The three Indian stocks below are only a sample, with the full screen surfacing 4 more businesses where discounted cash flow pricing flags similarly interesting narratives that are not covered here. To size up the wider field and identify which ideas best fit your own checklist, head straight to the Undervalued Stocks Based On Cash Flows screener.
Flair Writing Industries (NSEI:FLAIR)
Overview: Flair Writing Industries manufactures and sells pens, creative stationery and steel bottles and houseware across Indian and export markets, generating steady operating cash flows from everyday consumer use.
Operations: The business generates about ₹12,808 million in revenue primarily from its Writing Instruments & Other Allied(s) segment, reflecting its focus on pen and stationery lines.
Market Cap: ₹24.8 billion
Flair Writing Industries matters for this cash flow driven screener because its everyday pens and stationery convert frequent small purchases into a predictable cash engine that can be weighed carefully against discounted cash flow estimates.
"Scaling of high growth, higher margin creative and steel bottle and houseware portfolios, which together already contribute about 30% of revenue versus 15% last year, is expected to structurally lift consolidated revenue growth above prior guidance and sustain EBITDA margins near or above 18%."
What happens to Flair Writing Industries’ valuation story if a single assumption about future margin resilience in those newer categories breaks?
If that margin story is what worries you most, read the full narrative for Flair Writing Industries to see how Flair Writing Industries’ cash engine could accelerate or stall.
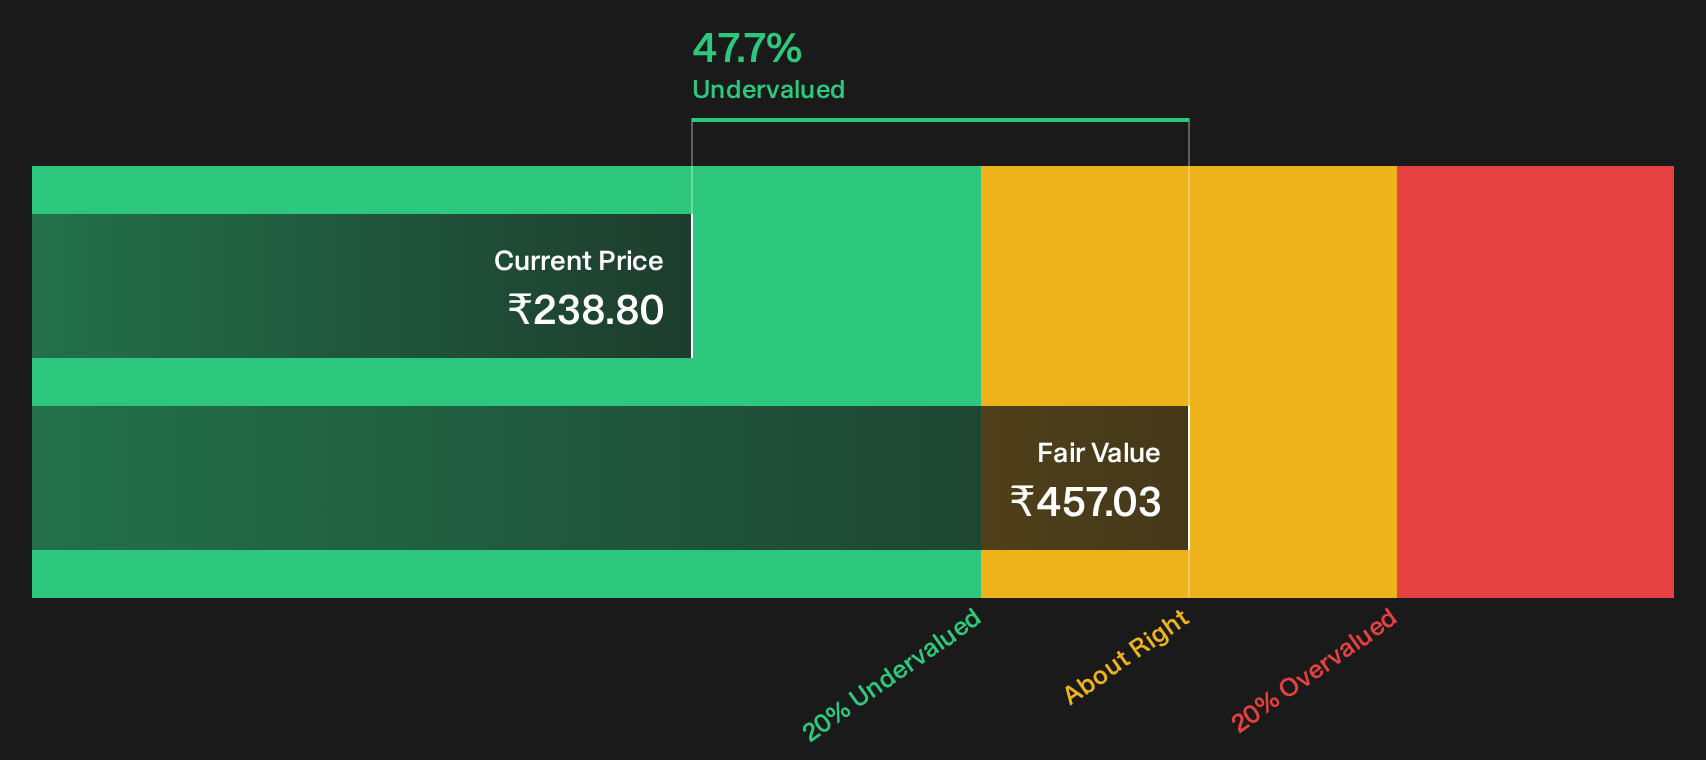
Huhtamaki India (BSE:509820)
Overview: Huhtamaki India manufactures flexible consumer packaging and labelling for food, beverages, personal care and pharmaceuticals, with recurring packaging contracts underpinning its cash flow profile.
Operations: The business generates about ₹26,104 million in revenue from consumer packaging solutions, which anchor the cash flows used in DCF valuation.
Market Cap: ₹18.5 billion
Huhtamaki India matters for this cash flow focused list because its beverage cartons and flexible food packaging lines turn repeat orders from FMCG clients into relatively steady inflows that can be weighed against discounted cash flow estimates.
"Increasing focus on sustainable and recyclable packaging solutions (such as the blueloop portfolio, already contributing 27 to 30% of revenue) positions Huhtamaki India to capture future regulatory-driven growth and shift its product mix toward higher-margin, value-added categories, potentially supporting improved net margins and long-term revenue growth."
What happens to Huhtamaki India’s valuation gap if one unseen pricing pressure in flexible packaging quietly eats into those margin expectations.
If that pressure is what you are weighing, full narrative for Huhtamaki India shows how Huhtamaki India’s blueloop push could be masking both upside and fragility in the cash story.
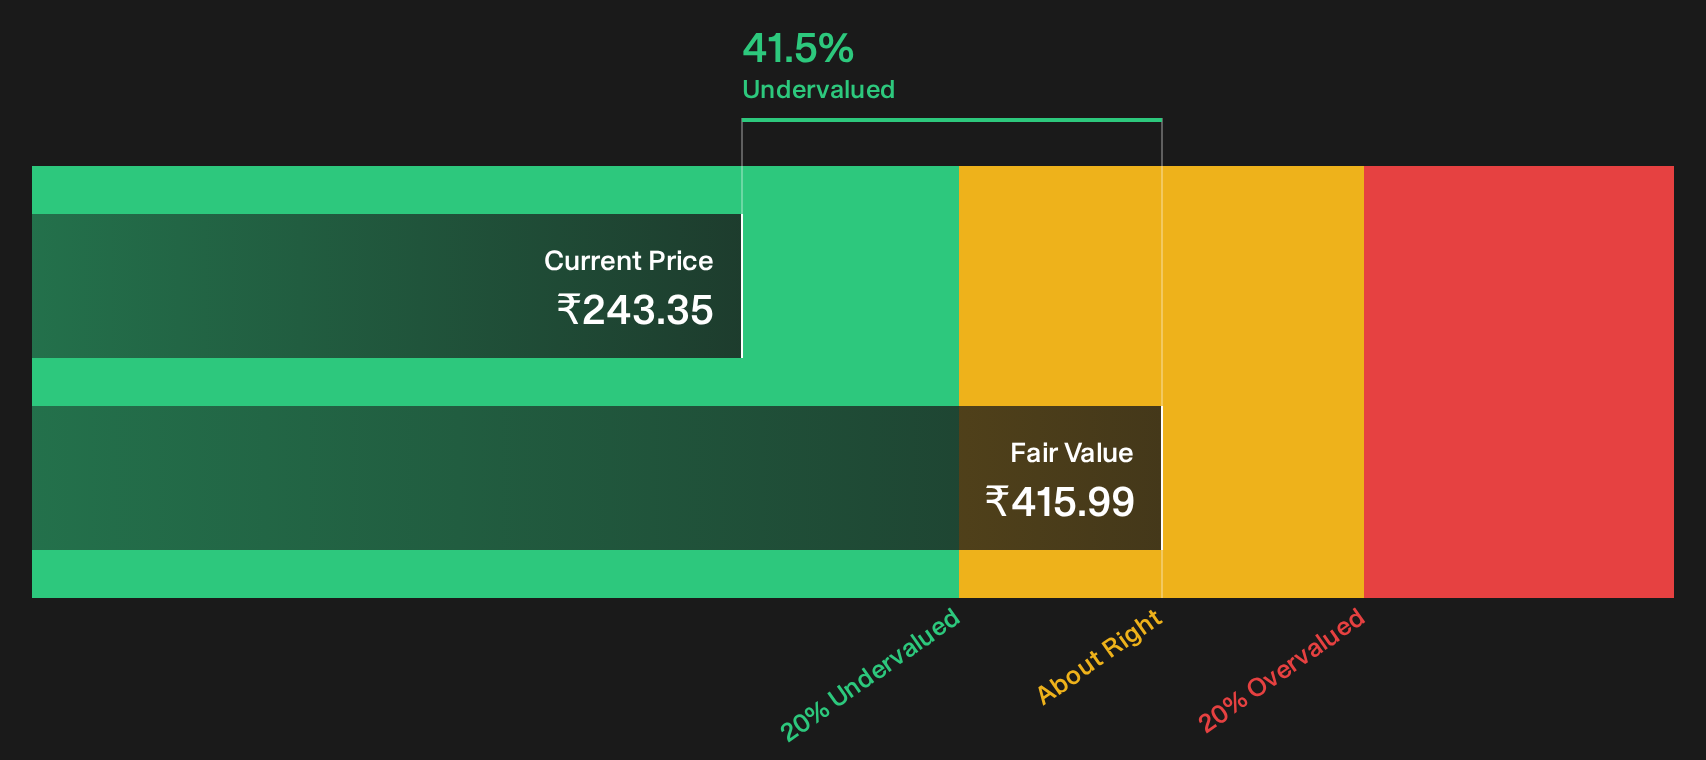
TeamLease Services (NSEI:TEAMLEASE)
Overview: TeamLease Services provides large scale staffing, payroll, HR solutions and work focused education services to employers across India and overseas.
Operations: TeamLease Services generates about ₹110.1b from General Staffing, ₹7.0b from Specialised Staffing and ₹2.5b from Other HR Services.
Market Cap: ₹20.4b
For a screener built around undervalued cash flows, TeamLease Services matters because its long running staffing contracts and payroll services translate recurring headcount into recurring cash. This is where the disconnect between price and discounted cash flow estimates starts to appear interesting.
"The rapid growth of apprenticeship adoption, accelerating government skilling initiatives, and TeamLease's unique partnerships with 22 universities position it as the clear national leader in work-integrated learning, paving the way for a new, high-growth, higher-margin revenue stream that is underappreciated in current earnings estimates."
The real test for TeamLease Services is how a shift in the mix between low margin staffing and higher margin services shapes those future cash flows.
That mix shift is exactly where the story gets interesting, and the full narrative for TeamLease Services maps how staffing cash flows and higher margin services could be quietly decoupling expectations.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first, and the strongest breakouts often fly before most investors are even watching. Scan these under the radar lists while it matters and get in early.
- Target higher yield potential with a curated pool of income payers in the 161 dividend fortresses before yields compress and prices catch up.
- Hunt for under the radar operators using the 616 high quality undiscovered gems while they are still quietly compounding away from the spotlight.
- Ride the build out of next generation infrastructure by tracking the 88 AI infrastructure stocks before capital floods into the theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com