
Is Adyen (ENXTAM:ADYEN) Cheap After Its Guidewire Partnership?
Adyen (ENXTAM:ADYEN) just secured approval as a Global Payment Partner for Guidewire Software, giving the payments platform access to Guidewire’s worldwide insurer client base through a standardized marketplace integration.
Against that backdrop, Adyen’s recent Guidewire partnership arrives after a mixed price run, with the share price gaining 6.96% over 90 days but falling 17.04% over 30 days and the 1-year total shareholder return down 35.40%. This points to fading momentum over the past year despite periods of short-term strength.
Scan beyond Adyen and identify other payment and fintech players with potential momentum, using our curated 616 high quality undiscovered gems as a starting universe.
The Guidewire deal gives Adyen fresh optionality, while the share price has already swung hard in both directions. Does that current mix of growth story and bruised returns still pay investors enough for the risk now?
Most Popular Narrative: 9% Undervalued
Based on the numbers used in the most followed thesis, Adyen’s fair value of about €974 per share sits only modestly above the latest close near €891. That leaves the Guidewire news positioned within a story that already treats the stock as slightly cheap rather than significantly mispriced.
My thesis is that Adyen’s business is stronger than the recent market mood implies, but the stock is not obviously cheap enough for that strength to create a large margin of safety. At around €886, I get to a base-case fair value of roughly €900 per share after adjusting my DCF for execution risk, FX noise, and integration risk.
See why 13 investors see Adyen as 9% undervalued.
Result: Fair Value of €974.81 (UNDERVALUED)
Still, the narrative around Adyen can change quickly if integration of Talon.One and Orb proves slower, or if the CFO transition hurts execution confidence.
Find out about the key risks to this Adyen narrative.
Another View: What Adyen’s P/E Is Telling You
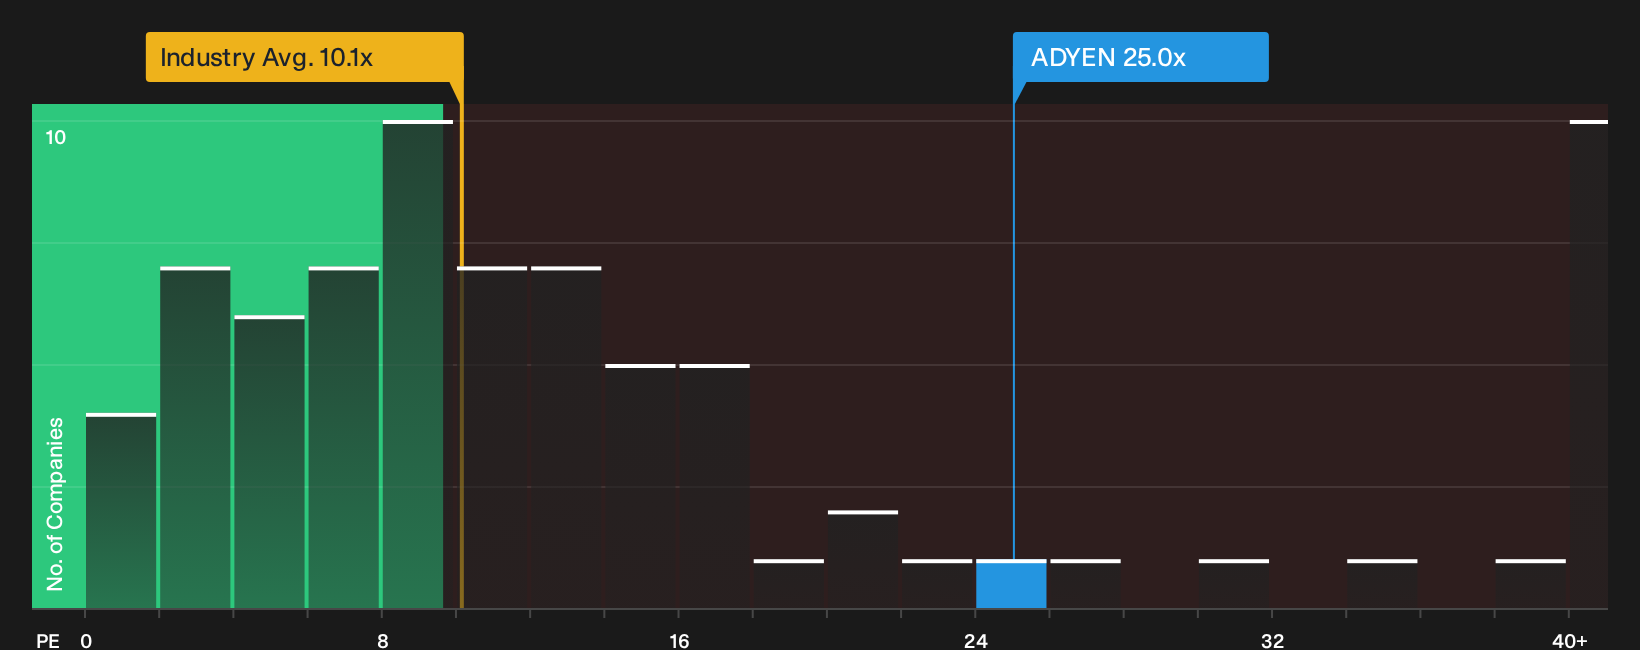
That fair value of about €975 per Adyen share leans on cash flow assumptions. The price tag looks very different when the focus shifts to earnings. At roughly 25x P/E, the stock trades far above peers on 16.7x, the wider European diversified financial group on 10.1x, and even its own fair ratio of 22.8x.
This kind of premium can signal confidence in Adyen’s quality, but it also leaves less room if execution around Talon.One, Orb, or AI monetisation disappoints. Does that gap feel like a risk you want to carry, or a pricing wrinkle you think the market will eventually close? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Adyen is split, with some focusing on execution risks and others pointing to upside potential from its current valuation. Act quickly, weigh both sides for yourself, and then review the full breakdown of risks and rewards in our 3 key rewards and 1 important warning sign
Looking for more Adyen investment ideas?
If you want to widen your opportunity set beyond Adyen, use the Simply Wall St screener to identify fresh ideas before everyone else catches on.
- Target value first and look for quality companies trading below what their fundamentals suggest through the 174 high quality undervalued stocks.
- Prioritize resilience and focus on businesses with stronger finances and reduced downside risk by scanning the 229 resilient stocks with low risk scores.
- Support portfolio stability and narrow in on companies with healthier debt profiles and reliable fundamentals via the list of solid balance sheet and fundamentals (198 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com