
Calix (CALX) Could Be 43% Undervalued After Its AI Platform Expansion
Calix (CALX) has expanded its AI-native Calix One platform by adding secure agentic workflows to Agent Workforce Cloud. These workflows support marketing, customer support, and network operations for broadband service providers.
Recent trading around Calix has been choppy. The share price is up over the past week but down about 12% over the past month and roughly 34% year to date, while the 1 year total shareholder return has fallen about 44%. This points to longer running pressure despite short term momentum around new AI product updates.
Scan how Calix's AI push compares with other potential opportunities by zeroing in on 88 AI infrastructure stocks powering the next wave of broadband and data-center spending.
Calix trades at a steep discount to both analyst targets and some intrinsic value estimates after this AI update driven bounce. Is that a margin of safety, or a warning sign that the market’s caution is warranted?
Most Popular Narrative: 43% Undervalued
Calix last closed at $35.42 while the most followed narrative pegs fair value at about $62.33. This implies a large gap that hinges on how its AI heavy platform strategy plays out over the next several years.
The upcoming rollout of Calix's third-generation platform, which integrates agentic AI capabilities, is expected to dramatically accelerate broadband providers' ability to monetize new services and experiences across residential, business, and municipal segments. This can drive higher ARPU, increased subscriber growth, reduced churn, and ultimately stronger revenue expansion beginning in the second half of 2025 and accelerating into 2026.
See why 18 investors see Calix as 43% undervalued.
Result: Fair Value of $62.33 (UNDERVALUED)
Still, the bullish Calix narrative could unravel if memory cost pressures persist longer than analysts model and if satellite competitors weaken the confidence of broadband providers in their spending.
Find out about the key risks to this Calix narrative.
Another View On Calix Valuation
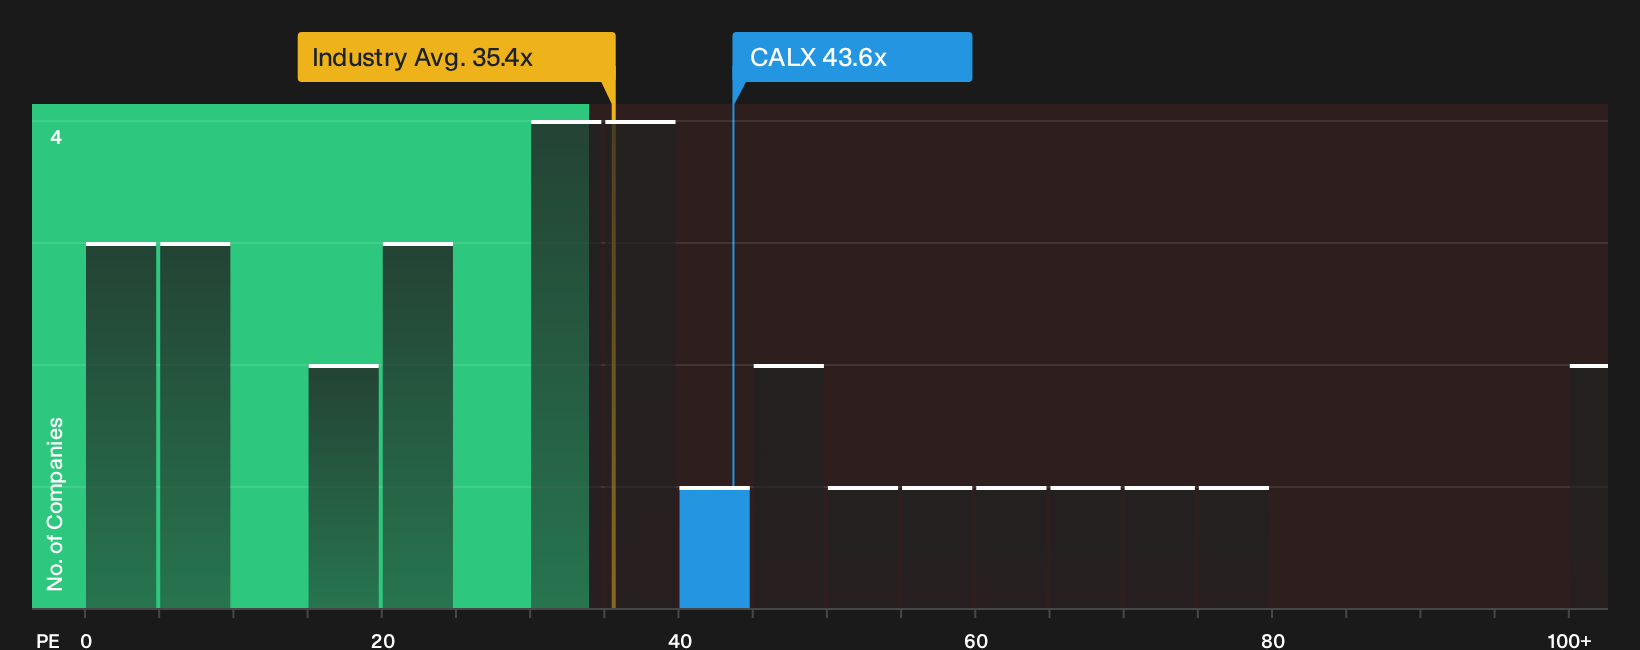
The first narrative leans on future cash flows and analyst assumptions to argue Calix is deeply undervalued. A simpler check tells a different story. On a P/E of 43.6x, the stock trades above both the US Communications industry at 34.4x and peers at 41.7x, while the fair ratio sits lower at 40.5x. That premium hints at less room for error if the AI rollout or margin recovery is slower than hoped. This raises a key question: which signal do you trust more, the discount to fair value or the rich earnings multiple?
To see how this earnings multiple compares in more detail and what it implies for valuation risk, take a closer look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Calix is split, which is exactly when fresh data matters most for you. Act quickly, review the upside case, and weigh the 3 key rewards.
Looking for more Calix investment ideas?
If Calix has your attention, broaden your watchlist with a few focused screens that surface opportunities you might otherwise miss.
- Target potential mispricings by scanning a curated pool of 30 high quality undervalued stocks that combine solid fundamentals with gaps between price and underlying business strength.
- Prioritise resilience by reviewing list of solid balance sheet and fundamentals (23 results) so you can focus on businesses that may better handle shocks without stretching their finances.
- Get ahead of the crowd by tracking 17 high quality undiscovered gems before broader attention and liquidity potentially change the risk and reward profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com