
Learn Why The Bull Case For Holmen Stock Could Change Following Index Removal
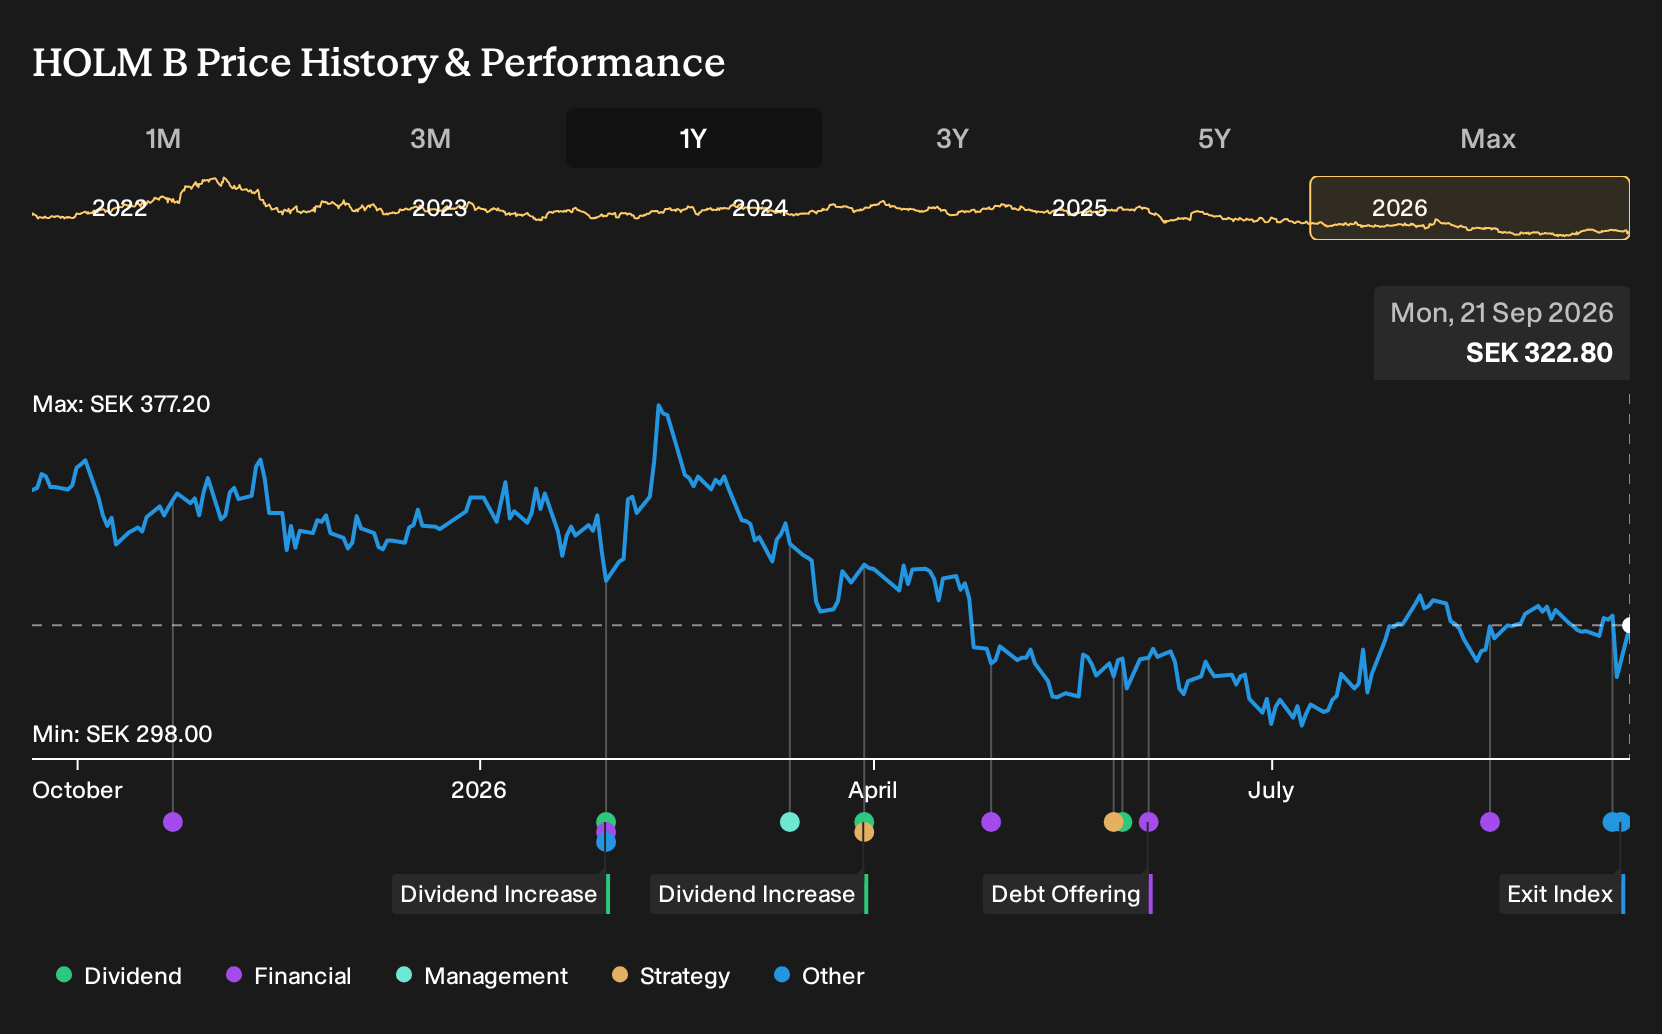
- Holmen AB was removed from the FTSE All-World Index in September 2026, following a review of index constituents that affected its inclusion in the global benchmark.
- The exit from this broad equity index may reshape who holds Holmen shares, since index-tracking funds often adjust positions around such changes.
- We will now look at how Holmen’s investment narrative could be influenced by its recent removal from the FTSE All-World Index.
Scan how Holmen's index exit compares with other quality businesses reacting to benchmark changes by reviewing the hand picked 229 resilient stocks with low risk scores that is now shaping more cautious portfolios.
Holmen Investment Narrative Recap
To own Holmen, you need to be comfortable with a cyclical materials group that leans on sustainable forestry, packaging board and wood products, while working through soft demand and pricing pressure in key export markets. The short term swing factor is how quickly volumes and pricing in board, paper and sawn wood stabilise relative to input costs, especially higher sawlog prices.
The index removal itself looks more technical than business driven and does not change the underlying operating risks. The bigger swing risk remains prolonged weak demand in Europe, the United States and Asia, combined with cost inflation in wood and energy that could keep margins under pressure and limit the benefit from efficiency gains.
The recent formation of Holmen’s Nomination Committee for the 2027 AGM matters more for governance than for immediate earnings. A shareholder based committee, including representatives of major owners alongside the chair, sets the stage for decisions on board composition and oversight of capital allocation across forests, packaging, wood products and renewable energy.
For you as a holder, the link back to catalysts is simple. Board quality and alignment influence how firmly management tackles persistent issues like overcapacity in paper, weak profitability in renewable energy and the handling of one off items. That governance setup can shape how consistently Holmen executes on efficiency projects and capacity decisions through the next cycle.
Holmen's narrative projects SEK 21.9b revenue and SEK 2.5b earnings by 2029, with analysts assuming revenue remains broadly flat over the period and earnings easing from SEK 2.7b today, which implies an earnings decline of SEK 0.2b from current levels.
Discover how Holmen's fair value indicates a 7% potential upside to its current price before momentum traders close that discount.
Exploring Other Perspectives
For a different angle on Holmen, focus on the bullish catalyst around higher earnings potential. The most optimistic analysts were pencilling in SEK 23.8b revenue and SEK 3.1b earnings by 2029, compared with the SEK 21.9b and SEK 2.5b consensus. Those upbeat views were set before the FTSE All-World exit, so you may want to compare several scenarios and decide which still feels reasonable.
Explore 2 other Holmen fair value estimates, including one that suggests as much as 12% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Holmen research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Holmen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Holmen's overall financial health at a glance.
Looking for more investment ideas beyond Holmen?
If the Holmen story has sharpened your view on quality, income and risk, it can help to widen the lens and compare it with other companies that share some of those characteristics.
- For investors hunting for resilient balance sheets and steady fundamentals, start with a curated list of solid balance sheet and fundamentals (198 results) that can help you stress test Holmen against financially robust peers.
- If long term value is your focus, line up Holmen beside a 174 high quality undervalued stocks that blends healthy cash flows with sound balance sheets.
- Income focused investors who see Holmen as one piece of a broader yield portfolio can round out their watchlist with a 161 dividend fortresses offering 5%+ payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com