
Ivanhoe Mines (TSX:IVN) Could Be 15% Undervalued After Makoko Resource Update
Ivanhoe Mines (TSX:IVN) has updated its Mineral Resource estimate for the Makoko District in the Democratic Republic of the Congo, following extensive diamond drilling and the introduction of mineable shape optimization modelling.
The refreshed Makoko resource lands while Ivanhoe Mines’ share price has had a mixed run, with CA$12.32 per share reflecting a recent 11.7% 90 day share price return but a year to date share price decline of 23.2%, and a 5 year total shareholder return of 46.1% that indicates stronger longer term momentum compared with the past year’s 5.6% total shareholder return decline.
Scan a curated set of copper focused opportunities by comparing Ivanhoe Mines with other producers and developers in the 17 top copper producer stocks that share similar sector drivers and resource themes.
Ivanhoe Mines now pairs a refreshed Makoko copper resource with a share price that has bounced in the short term but declined this year. Investors may be considering whether it makes more sense to step in at CA$12.32 or wait for a cheaper entry.
Most Popular Narrative: 15% Undervalued
Compared with the last close at CA$12.32, the most followed narrative pegs Ivanhoe Mines’ fair value higher, using a discount rate of 8.0% to bring long range cash flows back to today’s terms.
Completion and ramp-up of the Kamoa-Kakula smelter (targeted for September) and the associated drop in logistics costs are expected to meaningfully reduce unit costs, directly boosting future operating margins and cash flow. Ongoing capacity expansions at Kamoa-Kakula (Phases 1-3) and de-bottlenecking at Kipushi, alongside operational recovery from the recent seismic event, are projected to drive substantial increases in copper and zinc output, supporting strong top-line revenue growth in the next 12 to 24 months as production returns to full scale.
See why 27 investors see Ivanhoe Mines as 15% undervalued.
Result: Fair Value of CA$14.53 (UNDERVALUED)
Still, Ivanhoe Mines faces clear pressure points, including potential cost overruns on heavy capital projects and the risk that further seismic or operational issues disrupt planned output and cash generation.
Find out about the key risks to this Ivanhoe Mines narrative.
Another View: Ivanhoe Mines On Earnings Multiples
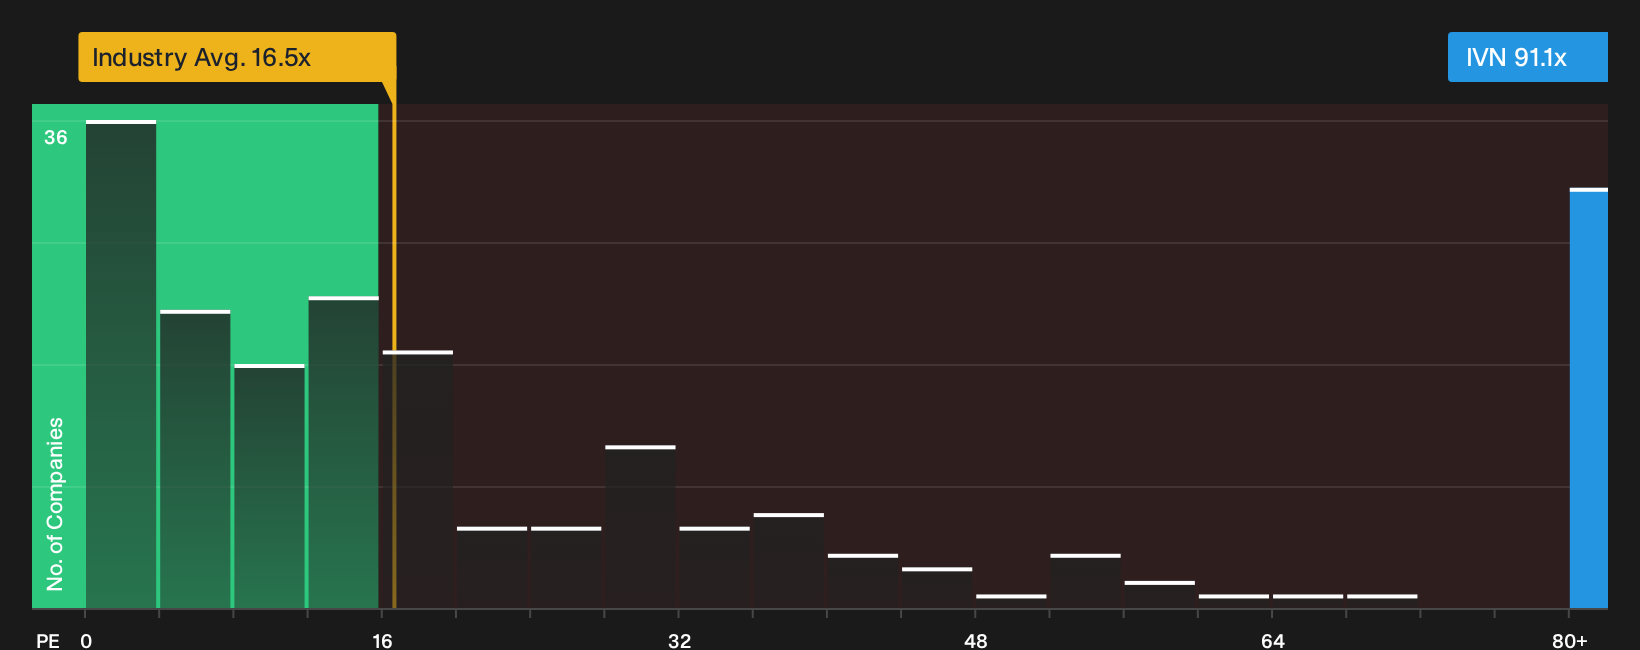
The DCF inspired fair value of CA$14.53 presents Ivanhoe Mines as underpriced, while the current P/E of 91.1x suggests a different perspective when compared with the Canadian Metals and Mining industry at 16.5x, peers at 17.6x, and a fair ratio of 28.1x that the market could move towards. That kind of gap points to meaningful valuation risk if earnings forecasts or sentiment change, so which signal appears more relevant at this time.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Ivanhoe Mines. That is exactly why you should move quickly, review the underlying data, weigh both caution and optimism, and then ground your own view in the 2 key rewards and 1 important warning sign.
Looking for more Ivanhoe Mines style investment ideas?
If Ivanhoe Mines has your attention, do not stop here. Use the Simply Wall St screener to uncover other opportunities that match your risk, income, and quality preferences.
- Target potential value opportunities by scanning the 6 high quality undervalued stocks, which combine quality fundamentals with prices that may not fully reflect them.
- Build a cash flow focused portfolio by reviewing the 1 dividend fortresses, which concentrate on higher yield payouts with supporting fundamentals.
- Dial risk down by filtering for the 8 resilient stocks with low risk scores, which emphasise resilient balance sheets and steadier return profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com