
Asian Growth Companies With High Insider Ownership September 2026
As of September 2026, Asian markets have been navigating a complex landscape influenced by global economic shifts and regional developments, with particular attention on the impact of rising energy costs and fluctuating demand in key sectors. Amidst these conditions, growth companies with high insider ownership have garnered interest for their potential resilience and alignment of interests between management and shareholders. In this context, identifying stocks that exhibit strong growth prospects while maintaining significant insider ownership can be a strategic approach for investors looking to capitalize on market opportunities.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Zhejiang Taotao Vehicles (SZSE:301345) | 27.9% | 30.6% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Meitu (SEHK:1357) | 22.9% | 30.7% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| KCTech (KOSE:A281820) | 20.6% | 31.6% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
Let's explore several standout options from the results in the screener.
Shanghai Junshi Biosciences (SEHK:1877)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Shanghai Junshi Biosciences Co., Ltd. is a biopharmaceutical company focused on the discovery, development, and commercialization of various drugs in China with a market cap of HK$36.42 billion.
Operations: Shanghai Junshi Biosciences Co., Ltd. generates revenue through the discovery, development, and commercialization of a range of pharmaceutical products within China.
Insider Ownership: 15.8%
Earnings Growth Forecast: 119.1% p.a.
Shanghai Junshi Biosciences is trading significantly below its estimated fair value, presenting a potential opportunity for growth-focused investors. The company recently reported a substantial turnaround with net income of CNY 21.66 million for H1 2026, compared to a loss last year. Revenue and earnings are expected to grow robustly, outpacing the market. However, its forecasted low return on equity and lack of recent insider trading activity may warrant caution despite promising revenue prospects and strategic developments in cancer treatment products.
- Navigate through the intricacies of Shanghai Junshi Biosciences with our comprehensive analyst estimates report here.
- In light of our recent valuation report, it seems possible that Shanghai Junshi Biosciences is trading behind its estimated value.

Shenghe Resources Holding (SHSE:600392)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Shenghe Resources Holding Co., Ltd is involved in the research, development, production, and application of rare earth products both in China and globally, with a market cap of CN¥38.91 billion.
Operations: Revenue Segments (in millions of CN¥): Rare earth products contribute CN¥18.45 billion, while mineral products account for CN¥2.67 billion.
Insider Ownership: 12.3%
Earnings Growth Forecast: 24.4% p.a.
Shenghe Resources Holding has demonstrated strong financial performance, with net income rising to CNY 886.62 million for H1 2026 from CNY 376.91 million the previous year. The company is projected to maintain robust revenue growth at 26.2% annually, outpacing the broader CN market's forecasted growth of 17.4%. Despite a lower-than-market forecasted earnings growth rate and low return on equity projections, its price-to-earnings ratio remains attractive compared to the market average.
- Click here and access our complete growth analysis report to understand the dynamics of Shenghe Resources Holding.
- Our valuation report unveils the possibility Shenghe Resources Holding's shares may be trading at a premium.

Micronics Japan (TSE:6871)
Simply Wall St Growth Rating: ★★★★★★
Overview: Micronics Japan Co., Ltd. is engaged in the development, manufacturing, and sale of body measuring equipment as well as semiconductor and liquid crystal display inspection equipment globally, with a market cap of ¥519.14 billion.
Operations: Micronics Japan's revenue is primarily derived from its Probe Card Business, which generated ¥84.87 billion, and its TE Business, which contributed ¥1.39 billion.
Insider Ownership: 15.3%
Earnings Growth Forecast: 24.9% p.a.
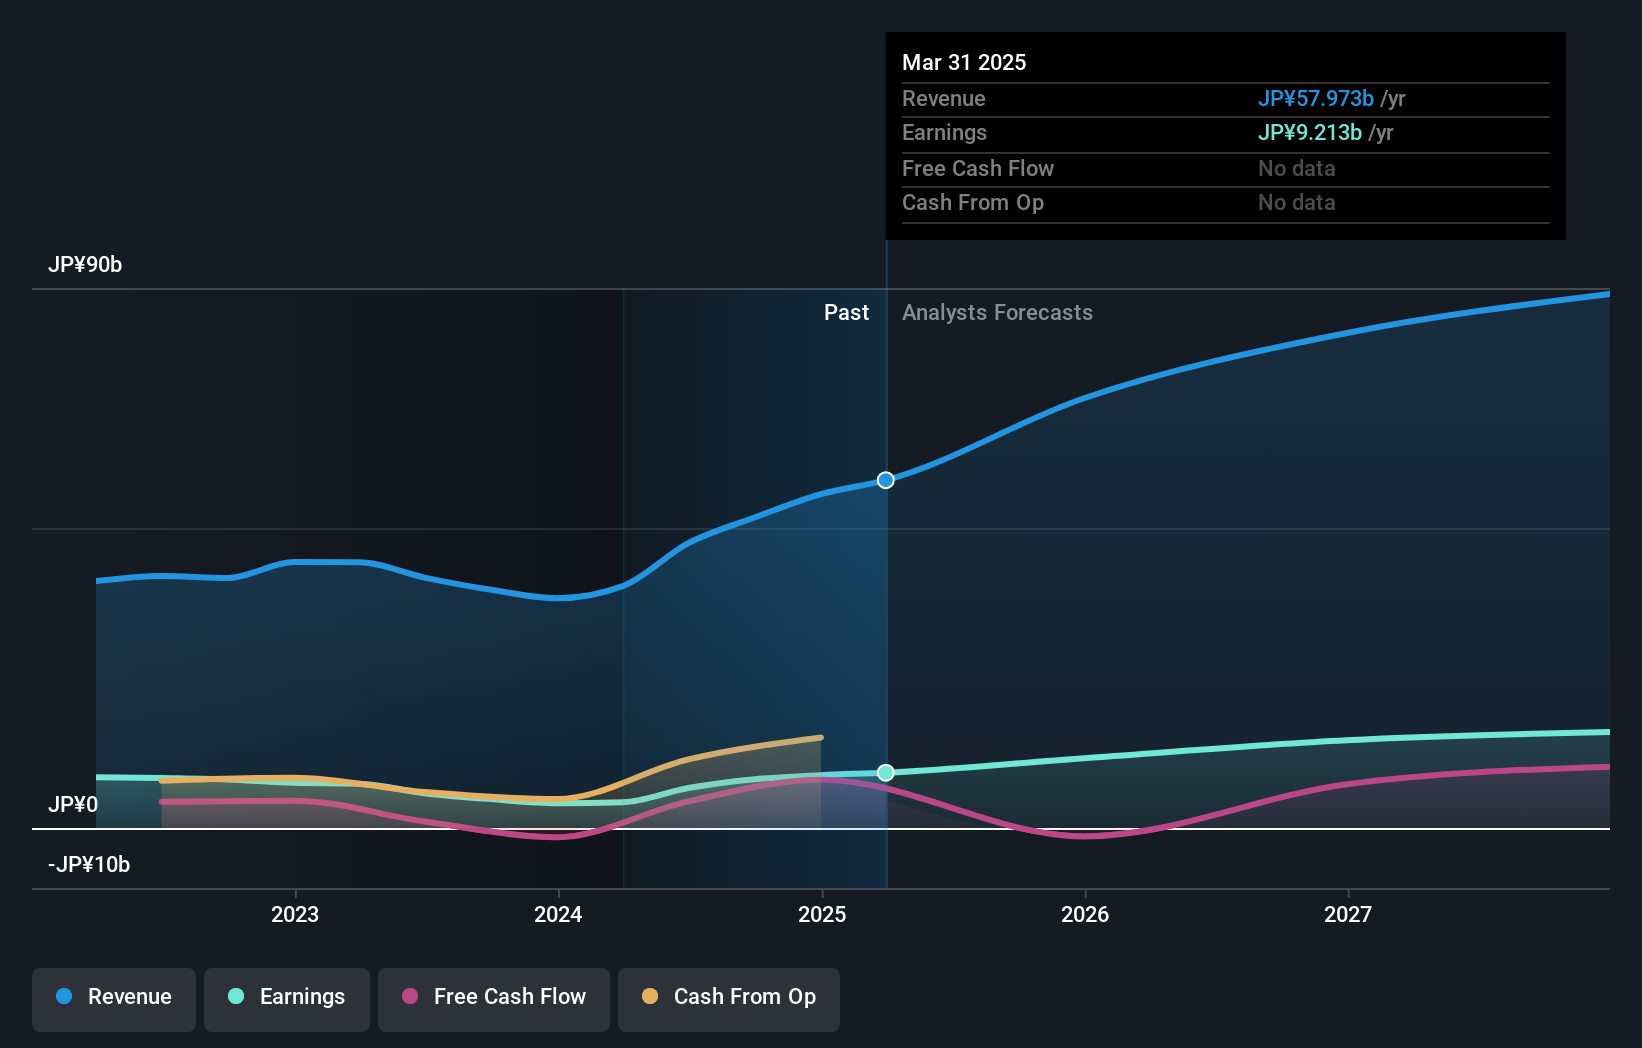
Micronics Japan is experiencing robust growth, with earnings surging 89.4% over the past year and revenue projected to grow at 23% annually, outpacing the Japanese market. Recently added to major indices like FTSE All-World and S&P Japan 500, its high insider ownership signals confidence in future prospects. Despite recent share price volatility, Micronics has raised its earnings guidance due to strong demand for memory semiconductor probe cards driven by generative AI advancements.
- Take a closer look at Micronics Japan's potential here in our earnings growth report.
- Upon reviewing our latest valuation report, Micronics Japan's share price might be too optimistic.
Next Steps
- Explore the 495 names from our Fast Growing Asian Companies With High Insider Ownership screener here.
- Ready For A Different Approach? These 25 companies survived and thrived after COVID and have the right ingredients to survive Trump's tariffs. Discover why before your portfolio feels the trade war pinch.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com