
Learn Why The Bull Case For Techtronic Industries Stock Could Change Following Earnings Upgrade
- Techtronic Industries was recently upgraded by Zacks to Rank #2, after analysts raised earnings estimates that reflect a stronger profit outlook built on its core power tools, outdoor equipment, and floorcare operations.
- The earnings estimate revisions highlight how Techtronic Industries' focus on cordless ecosystems, automation, and cost efficiency is increasingly central to how analysts view its long term cash generation potential.
- We will now explore how Techtronic Industries' upgraded earnings outlook could reshape the existing investment narrative around demand, margins, and risk.
Expand your watchlist beyond Techtronic Industries by reviewing hand-picked 174 high quality undervalued stocks that also combine solid cash generation with disciplined cost control.
Techtronic Industries Investment Narrative Recap
To hold Techtronic Industries, investors may want to consider whether its cordless ecosystems, outdoor tools, and cleaning equipment can continue to gain traction with both trades and consumers, and whether cost control can offset wage and material pressure. In the near term, execution on manufacturing efficiency and automation is a key swing factor because it feeds directly into margins and cash generation.
The biggest current risks relate to cost and demand. Supply chain shifts, tariff policy, and reliance on large retailers could all squeeze profitability if conditions change. The Zacks earnings upgrade reflects a more constructive view on the near term, but it does not remove those underlying pressures.
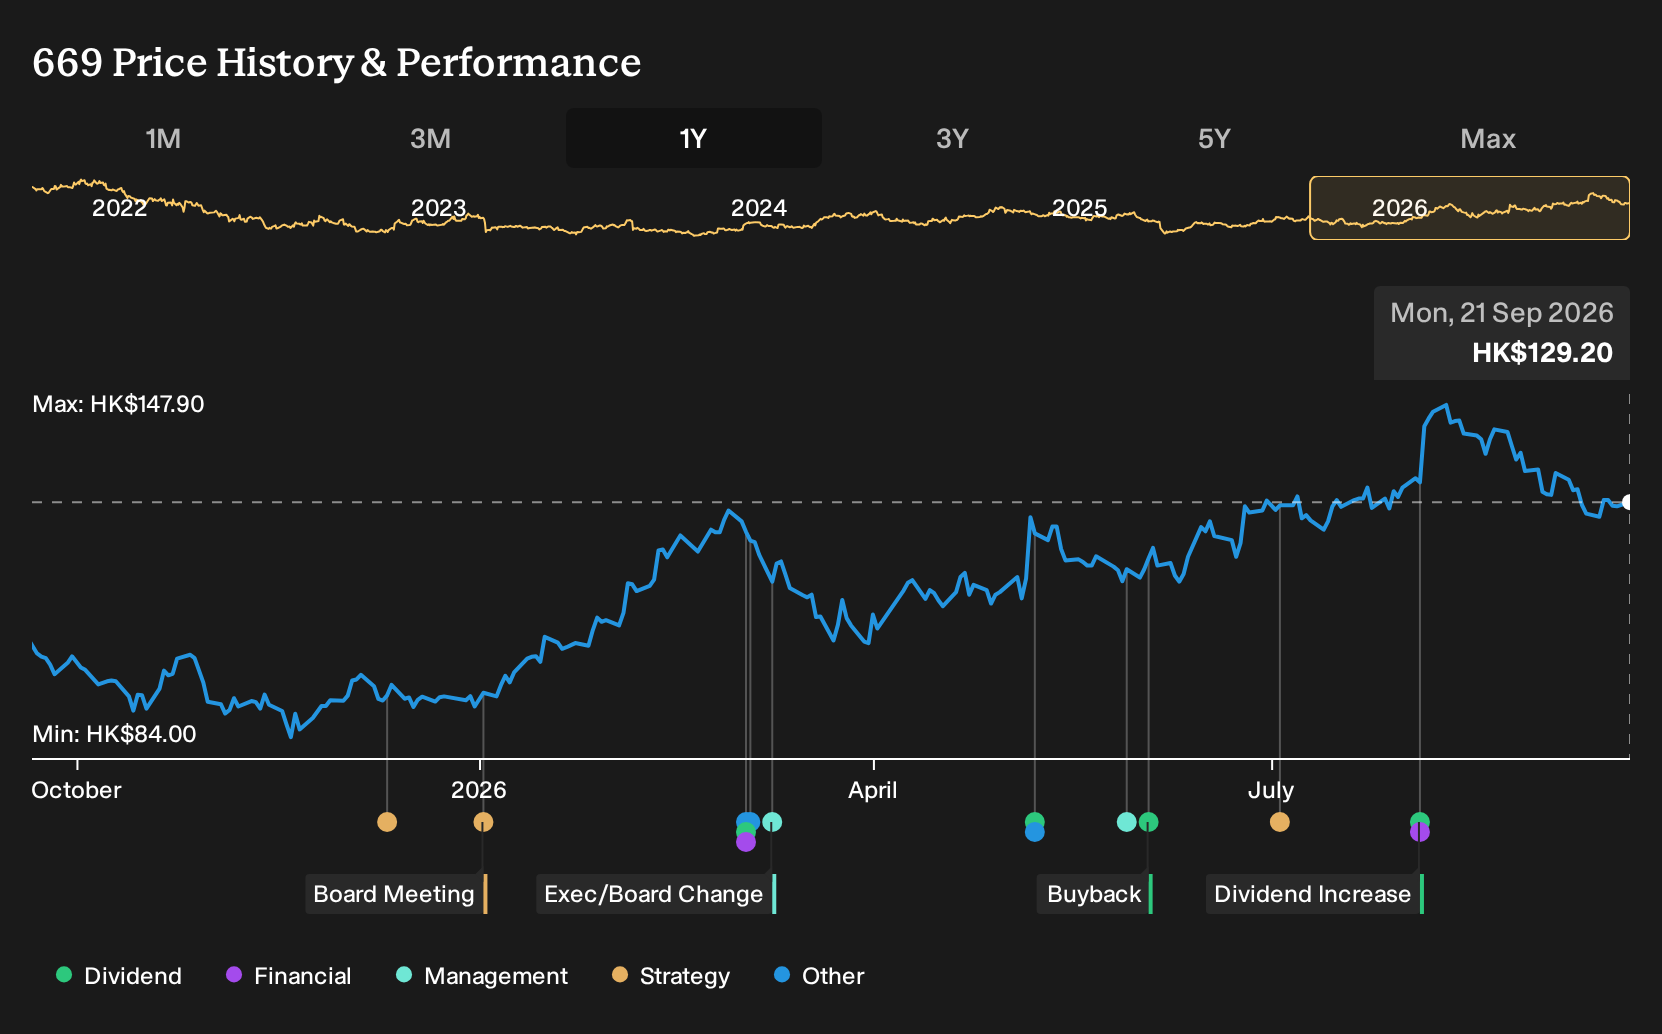
The Zacks move to Rank #2 is the announcement most closely tied to this story because it stems from higher earnings estimates rather than a one-off corporate event. That matters for shareholders because it connects directly to how the market is reading Techtronic Industries' ability to convert sales into profit.
This updated view leans on themes already visible in the business. Earnings are forecast to grow 12.6% a year, margins have improved from 7.9% to 8.3%, and revenue recently reached about US$15.7b. The upgrade aligns with that operational picture, but the same risks around tariffs, retailer concentration, and competition in cordless tools remain in play.
Techtronic Industries' current narrative assumes revenue of US$20.0b and earnings of US$2.0b by 2029, built on 8.3% yearly top line growth and an earnings increase of about US$700m from US$1.3b today.
Discover how Techtronic Industries' fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Techtronic Industries, the bearish story leans heavily on slower Milwaukee driven project demand. The lowest analysts were penciling in revenue of about US$19.0b and earnings near US$1.9b by 2029, well below consensus, which shows how far views can spread. Treat this Zacks upgrade as your cue to compare these narratives yourself.
Explore 2 other Techtronic Industries fair value estimates, including one that suggests it could be worth just HK$132.21.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Techtronic Industries research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Techtronic Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Techtronic Industries' overall financial health at a glance.
Looking for more investment ideas beyond Techtronic Industries?
If you want to stress test your view on Techtronic Industries, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors who care most about financial resilience and balance sheet quality, scan a list of solid balance sheet and fundamentals (198 results) that can help you compare debt loads and liquidity side by side.
- If capital preservation and smoother ride potential are higher on your list, check out a curated 229 resilient stocks with low risk scores that may offer steadier business profiles to contrast with Techtronic Industries.
- For those hunting for less crowded ideas with strong fundamentals, review a focused 616 high quality undiscovered gems that could broaden your watchlist beyond the usual large caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com