
O3b Satellite Launches Might Change The Case For Investing In SES (ENXTPA:SESG)
- SES S.A. has completed the launch of its eleventh, twelfth and thirteenth O3b mPOWER satellites and expanded its collaboration with Elveo Mobile to support multi orbit, high performance connectivity and direct to device services, particularly for European and government users.
- The combination of expanded O3b mPOWER capacity, Elveo's direct to device technology and S band spectrum rights points to SES leaning further into capital intensive, multi orbit network infrastructure while seeking higher value demand from enterprise, mobility, media and institutional customers.
- We will now look at how SES's expanded O3b mPOWER constellation could reshape the investment narrative around capital intensity and demand.
Scan beyond SES and find other satellite and space connectivity players that could be preparing for similar multi orbit opportunities with our curated 40 power grid technology and infrastructure stocks
SES Investment Narrative Recap
For an SES shareholder, the core belief is that heavy investment in multi orbit infrastructure eventually translates into steadier cash generation from networks, mobility and government customers, despite a media segment under structural pressure. The key short term swing factor is execution on O3b mPOWER, meoSphere and IRIS2, while managing about €700 million of 2026 CapEx without stretching an already pressured balance sheet.
The biggest risk is that front loaded spending and integration work, including the Intelsat deal, do not translate fast enough into higher value contracts, given SES remains loss making and interest costs are not well covered by earnings. The new launches and Elveo partnership strengthen the operational story but do not, on their own, change that near term financial tension.
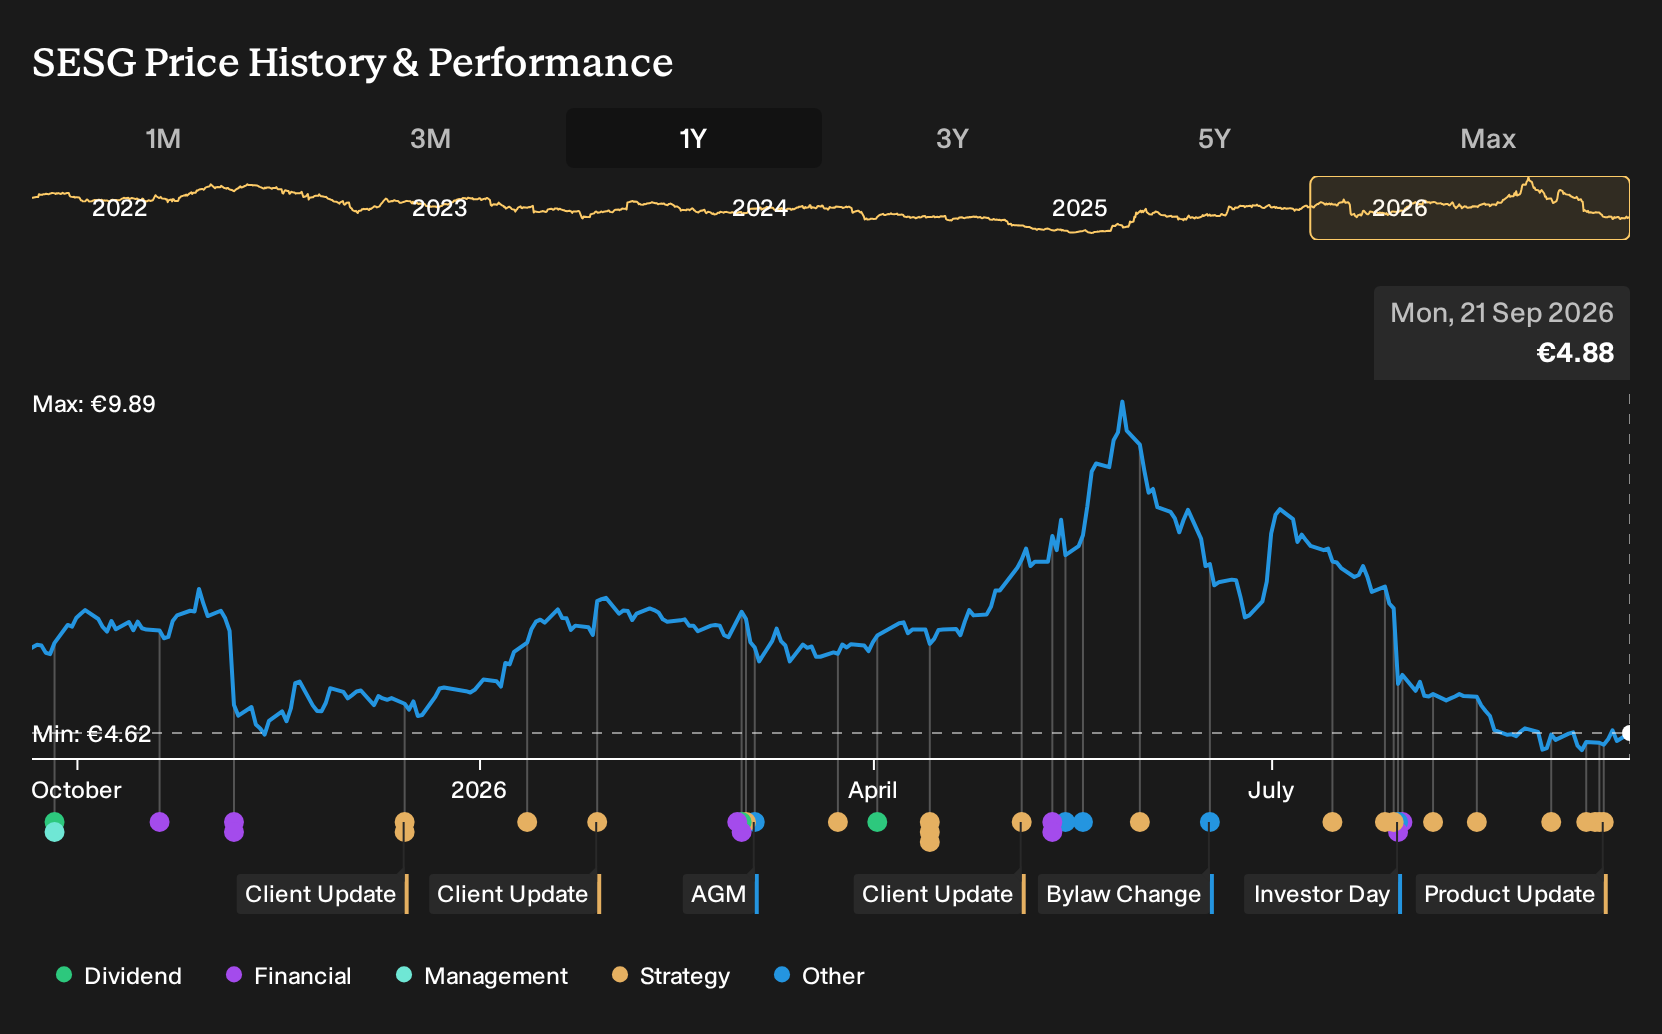
The O3b mPOWER launches announced in mid September 2026 look most relevant here. They directly connect to SES focus on software defined, multi orbit capacity that targets enterprise, mobility, telecom and government use cases. They also sit alongside government programs like IRIS2 and projects such as meoSphere within the current investment cycle.
These extra satellites increase available capacity and resiliency, which can support SES push into higher bandwidth contracts ranging from tens of Mbps to multi gigabit services per site. That said, the launches also reinforce the capital intensity investors already see as a central catalyst and risk. The payoff depends on filling that capacity while managing leverage, interest costs and an uncovered dividend.
SES' current analyst narrative points to revenues of €3.4b and earnings of €81.6 million by 2029, based on a 5.1% yearly revenue growth rate and an earnings shift of about €233 million from a loss of €151.0 million today.
Uncover why SES' fair value indicates a 69% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view on SES focuses less on O3b mPOWER launches and more on the risk that multi orbit and direct to device competition keeps squeezing returns. The most bearish analysts were assuming revenue would decline 1.3% a year and still only reach about €3.1b with €144.1 million earnings by 2029. That is far more cautious than consensus, and these satellite launches plus the Elveo deal may eventually push both narratives to adjust.
Explore 2 other SES fair value estimates, including one that suggests it could be worth just €8.06!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your SES research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SES. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SES' overall financial health at a glance.
Looking For More Investment Ideas Beyond SES?
If the SES story has you thinking about portfolio balance, it can help to line it up against other opportunities with different risk and income profiles using the Simply Wall St Screener.
- For investors hunting for potential mispricing, scan a curated set of 174 high quality undervalued stocks that combine quality fundamentals with discounted market expectations.
- If capital preservation and stability matter most to you, focus on a 229 resilient stocks with low risk scores that screens for resilient businesses with lower risk scores.
- Those chasing resilient income streams can zero in on 162 dividend fortresses that pair higher yields with more robust financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com