
CAE Stock In Focus After $300 Million Air Force Training Contract Through 2035
- CAE Inc. disclosed that it secured a US$300 million competitive recompete contract from the United States Air Force to provide C-130H aircrew training and support services across multiple U.S. bases through December 2035.
- The award locks in long-duration training work for CAE’s defense segment, reinforcing its role in mission readiness services and supporting visibility on future training device utilization and program management workloads.
- This article examines how CAE’s long-dated C-130H training contract with the U.S. Air Force shapes the broader investment narrative.
Scan beyond CAE and this C-130H contract by reviewing hand-picked defense and mission-readiness peers in the 8 resilient stocks with low risk scores that aim for resilience and lower risk scores.
CAE Investment Narrative Recap
To own CAE, you need to believe its mix of civil aviation and defense training can turn a large backlog and high fixed costs into steadier cash flows despite recent margin pressure, one off items, and a relatively high P/E. The new US$300m C 130H contract supports utilization and revenue visibility in defense but does not remove balance sheet risk.
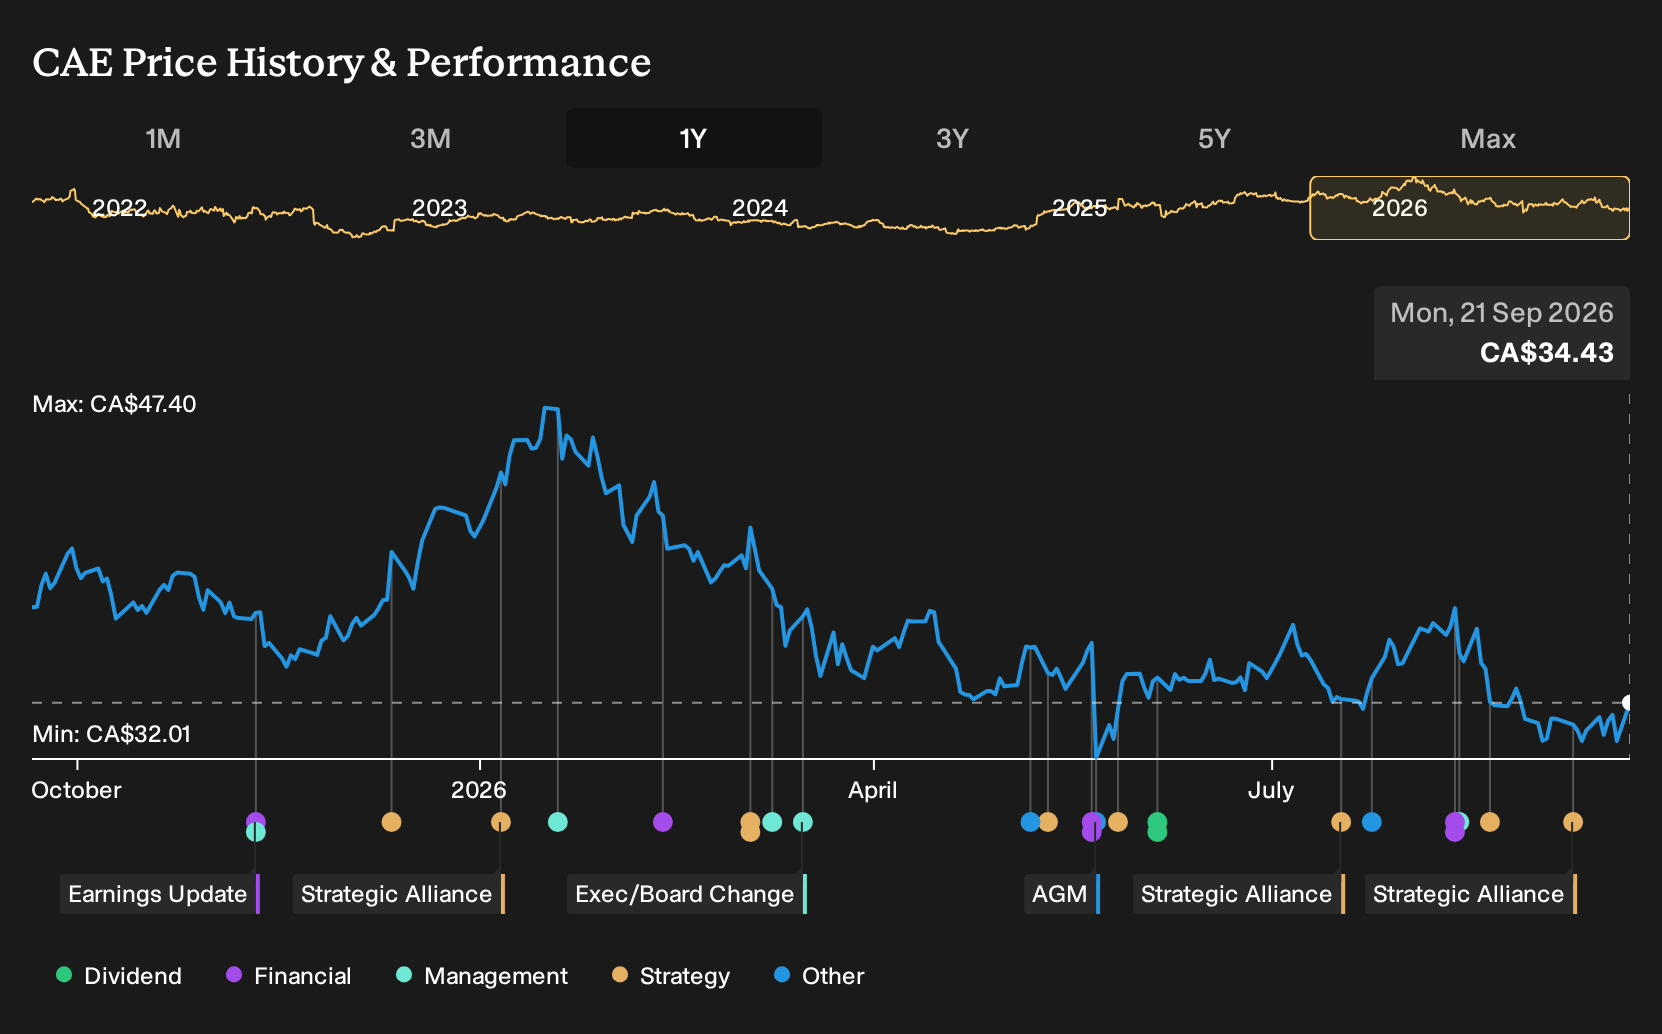
The key near term swing factor remains execution on margins and cash conversion, while net debt of about US$3.2b still constrains flexibility. The biggest risk stays the same. Slower civil training demand or weaker business aviation would make leverage and the recent underperformance versus the Canadian market more uncomfortable.
The MoU with WB Electronics on unmanned and autonomous systems ties into the same mission readiness theme as the C 130H award, but in a different corner of defense demand. Together, these moves keep CAE involved in both legacy aircrew training and emerging unmanned requirements, which matters if defense budgets later lean harder toward new platforms.
For you, the MoU is interesting because it broadens the potential pipeline that could support the earnings growth analysts are modeling, while adding execution and partnership risk on newer technologies. It reinforces that the thesis is not only about civil aviation cycles. It is about whether CAE can turn a growing spread of training programs into higher quality, less volatile earnings.
Analysts expect CAE's revenues to reach CA$5.4b and earnings to reach CA$523.0m by 2029. This implies forecast revenue growth of 2.7% a year and an earnings increase of about 82% from current earnings of CA$286.9m.
Uncover why CAE's fair value indicates a 29% potential upside to its current price that could narrow quickly if sentiment around CAE improves.
Exploring Other Perspectives
Some of the most optimistic CAE analysts focus on defense as a once in a generational catalyst. Before this C-130H training win, they were already modeling revenue of about CA$5.9b and earnings of roughly CA$685.8m by 2028. You can treat this new contract as a fresh test of those upbeat views and compare several angles.
Explore 3 other CAE fair value estimates, including one that suggests as much as 48% potential increase from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd. Consider your own research and instincts.
- A great starting point for your CAE research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CAE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CAE's overall financial health at a glance.
Looking for more investment ideas beyond CAE?
If this CAE story has sharpened your thinking on risk, cash flows, and contract visibility, you can apply the same lens to a wider watchlist using the Simply Wall St Screener.
- If capital preservation sits high on your list, focus on companies that score well on balance sheet strength through the list of solid balance sheet and fundamentals (7 results).
- If value is your priority, scan for stocks that combine quality fundamentals with appealing pricing using the 6 high quality undervalued stocks.
- If you want ideas the market may be overlooking, cast a wider net across lesser followed opportunities with the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com