
Zillow Group (ZG) Launches Preview With Realtor.com, Is It Still Below Fair Value?
Why the Zillow Group news matters for investors
Zillow Group (ZG) just rolled out Preview with Realtor.com, giving buyers shared access to pre-market listings across both sites. The collaboration creates a fresh angle on listing visibility and user engagement.
The Preview launch lands during a rough patch for Zillow Group’s shares, with the 30-day share price return down 15.36% and the year-to-date share price return down 52.55%, while the 1-year total shareholder return has declined 60.18%. This signals pressure despite recent product momentum and the stock’s removal from the FTSE All-World Index earlier in September.
Spot fresh ideas by scanning 17 high quality undiscovered gems, which, like Zillow Group, sit at the intersection of real estate, technology, and changing buyer behavior.
After a sharp slide in Zillow Group’s share price alongside the Preview launch, the key question is whether the current reset already reflects the risks or whether it makes more sense to wait for a lower entry as the numbers get unpacked next.
Most Popular Narrative: 34% Undervalued
The most followed narrative on Zillow Group pegs fair value at $47.23 per share versus the recent $31.13 close, so the market reset around Preview and listing access is being weighed against a much higher long term earnings profile.
The shift toward integrated, end-to-end digital transaction ecosystems (like Zillow 360 and Enhanced Markets) is enabling Zillow to capture more ancillary services revenue (mortgages, rentals, software). This is reducing dependence on advertising, expanding top-line growth and supporting EBITDA margin expansion through operational efficiencies.
See why 25 investors see Zillow Group as 34% undervalued.
Result: Fair Value of $47.23 (UNDERVALUED)
Still, the narrative can break if housing activity stays weak and if tighter Multiple Listing Service data access limits how effectively Zillow Group can monetize its traffic.
Find out about the key risks to this Zillow Group narrative.
Another View: Zillow Group looks expensive on earnings
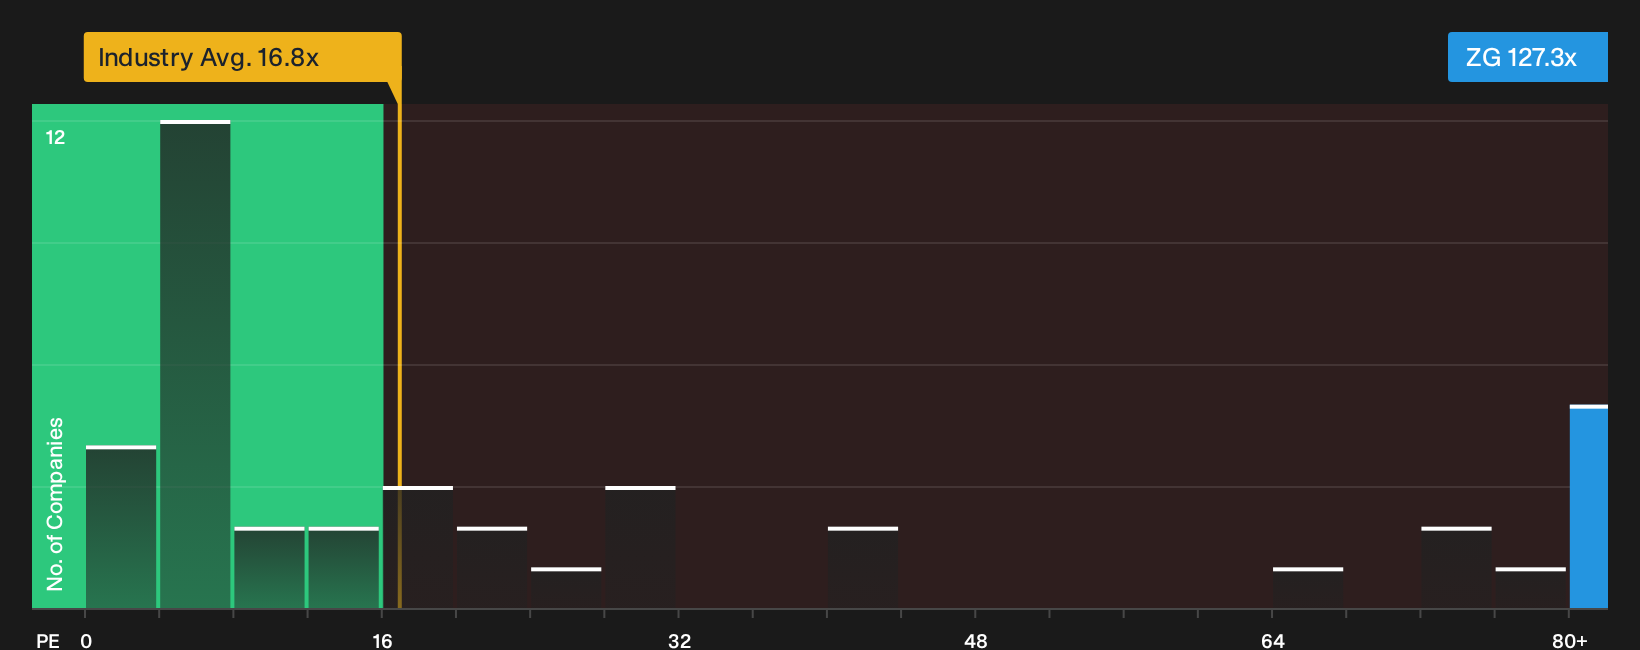
The analyst narrative and SWS DCF work both flag Zillow Group as undervalued, yet the current P/E of 127.3x tells a very different story. That multiple is far above the US real estate sector on 16.8x and the fair ratio estimate of 47.6x, which implies meaningful valuation risk if sentiment cools.
For investors, the gap between 127.3x today and a 47.6x fair ratio suggests less room for error if housing activity, listing access or rentals growth underwhelm. It raises a simple question: Is the earnings profile strong enough for that kind of premium to hold up?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of pressure and potential around Zillow Group feels finely balanced, consider acting while sentiment is still split and weigh the upside against the downside yourself. To see both sides laid out clearly, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Zillow Group?
Do not stop at one opportunity. Give yourself options by scanning other focused lists where the numbers and business quality criteria are already filtered for you.
- Target steadier compounding potential with companies that combine resilient balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Hunt for pricing gaps where quality and valuation look more aligned by reviewing the 30 high quality undervalued stocks.
- Lock in potential cash flow today while still watching total return potential using the income focused 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com