
BlackBerry (TSX:BB) Stock Looks Fairly Priced Despite Its 129% Run
BlackBerry has turned heads in 2026, with a sharp share price move that raises a simple question for investors. Do the cash flows that the business can generate over time support where the stock now trades?
- BlackBerry has delivered a 128.9% return year to date, which puts a lot of weight on whether its current cash flow outlook can support that kind of rerating.
- Fresh attention on QNX and robotics, along with a sizeable royalty backlog and higher revenue expectations, can shift how reliably and how quickly future cash flows may come through.
- If you'd rather focus on earnings, this one's for you. See why BlackBerry's 83.5x P/E tells a different valuation story.
For investors, the debate is whether the current share price lines up with the intrinsic value suggested by BlackBerry's cash flows under a Discounted Cash Flow (DCF) approach.
If you are testing whether BlackBerry's cash flow story justifies its price move, it can also help to scan a wider field of 6 high quality undervalued stocks.
Where Does BlackBerry Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here focuses on what BlackBerry can return to shareholders based on future free cash generation. Latest twelve month free cash flow sits at about $60.4 million, with the 2 Stage Free Cash Flow to Equity setup pointing to recovering and then growing cash flows, reaching an analyst forecast of $223 million by fiscal 2031.
On that cash flow path, the DCF output suggests BlackBerry's intrinsic value is broadly in line with the current CA$11.95 share price. Because QNX revenue and its nearly US$1 billion royalty backlog are central to that recovery story, the recent push into robotics and physical AI helps explain why the market is willing to pay roughly what the projected cash flows support. Find out what BlackBerry could be worth using our Discounted Cash Flow (DCF) estimate.
The BlackBerry Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for BlackBerry pick up from that valuation puzzle and describe which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price, all housed on the Community page. Each narrative links a specific fair value to a particular storyline about BlackBerry's potential catalysts and key risks, so you can see over time which version appears to be unfolding.
Community views on BlackBerry have split into two clear camps, with one group seeing more upside in the current price than the other.
Bull case: 26% undervalued
"QNX charges automakers a royalty every time a car rolls off a production line, once a design win is secured..."
Discover why this Narrative puts BlackBerry at 26% undervalued.
Bear case: 5% overvalued
"Given the current share price of CA$12.15, the analyst price target of CA$11.36 is 6.9% lower..."
Explore why this Narrative puts BlackBerry at 5% overvalued.
One more BlackBerry check before you close the tab
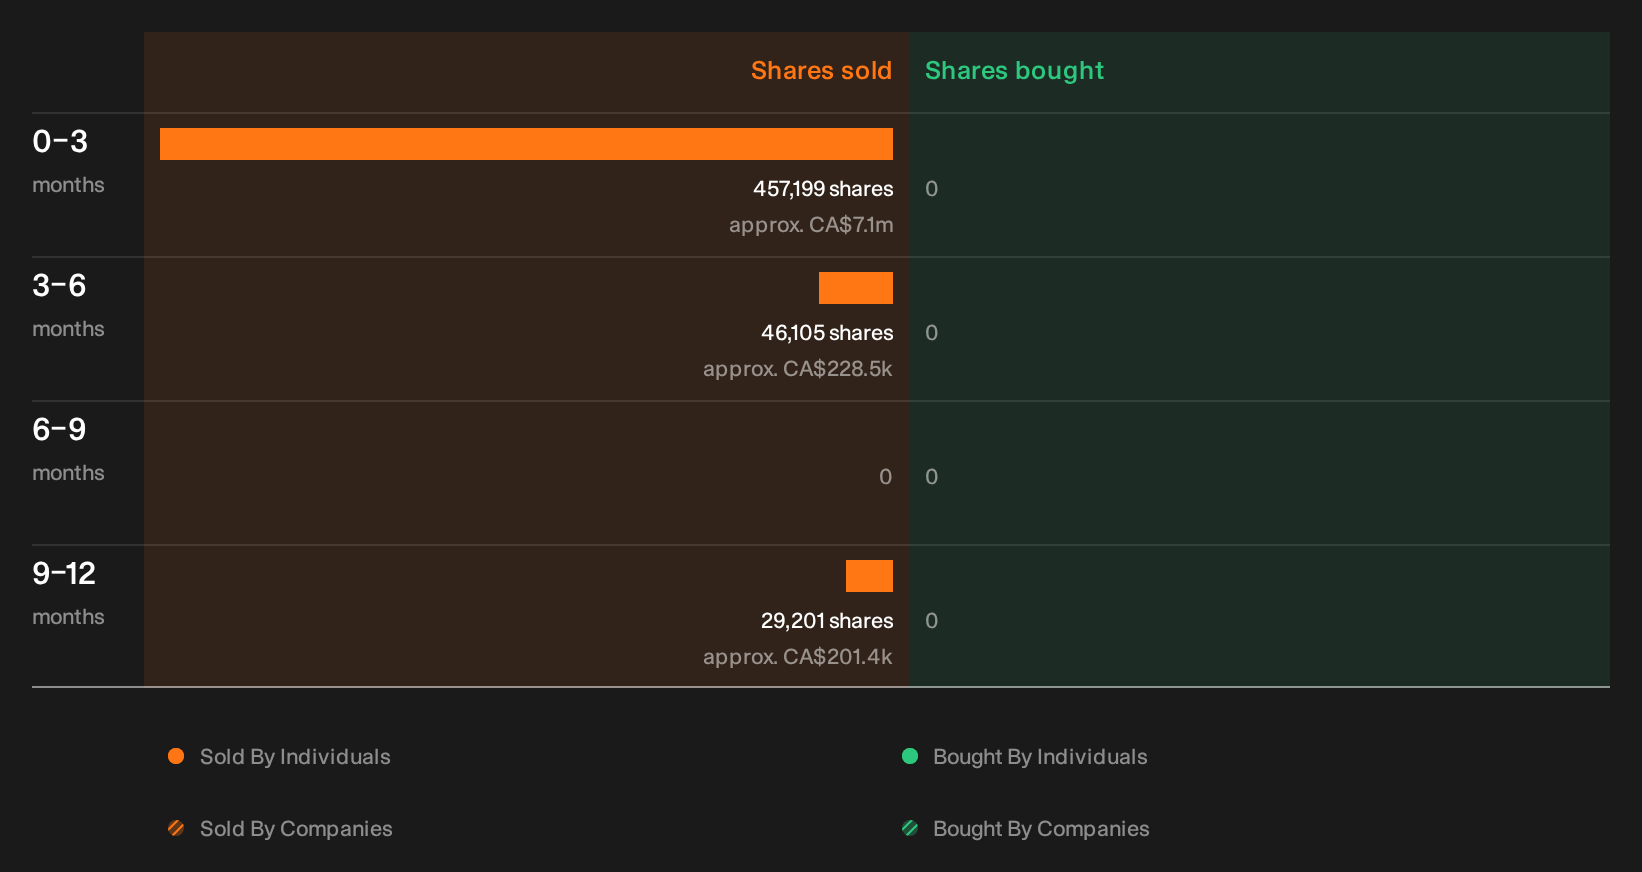
Before you move on from BlackBerry and its cash flow story, it is worth knowing that recent insider share activity has been flagged, with who sold, how much, and what it might signal all laid out for you to review. See the recent insider selling flagged for BlackBerry.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com