
Is Deutsche Lufthansa (XTRA:LHA) A Bargain Following Rising War Risk Costs?
A Ukrainian drone strike on Moscow’s energy and airport infrastructure has pushed geopolitical risk back into focus, with aviation insurance and war risk pricing becoming a fresh cost concern for Deutsche Lufthansa (XTRA:LHA).
For Deutsche Lufthansa, the recent geopolitical flare up comes on top of a share price that has already fallen about 16.7% over the past 90 days, even though the 1 year total shareholder return is still positive at 8.8% and the 5 year total shareholder return is around 33.2%.
Scan beyond Deutsche Lufthansa and stress test your thesis against other carriers and travel businesses facing similar risk premiums using our curated 229 resilient stocks with low risk scores for comparison.
Deutsche Lufthansa shares now trade at a steep discount to both analyst targets and some intrinsic value estimates after that sharp 90 day slide. Is the market prudently pricing war risk, or overdoing the caution ahead of the numbers?
Most Popular Narrative: 21% Undervalued
The most followed narrative pegs Deutsche Lufthansa’s fair value at €9.66, comfortably above the last close of €7.66. This puts extra weight on whether the current geopolitical stress is a short term scare or a longer running cost issue.
The market appears to be pricing in sustained, above-trend revenue growth for Lufthansa driven by elevated post-pandemic travel demand, continued international expansion (e.g., ITA Airways integration and additional wide-body deliveries), and successful upselling to premium and ancillary products, despite mounting evidence of softening yields and mixed forward bookings in key markets, which could undercut top-line expectations.
See why 61 investors see Deutsche Lufthansa as 21% undervalued.
Result: Fair Value of €9.66 (UNDERVALUED)
Still, two big swing factors hang over Deutsche Lufthansa: smooth ITA Airways integration and the risk that higher European labour and regulatory costs squeeze margins.
Find out about the key risks to this Deutsche Lufthansa narrative.
Another View On Deutsche Lufthansa’s Valuation
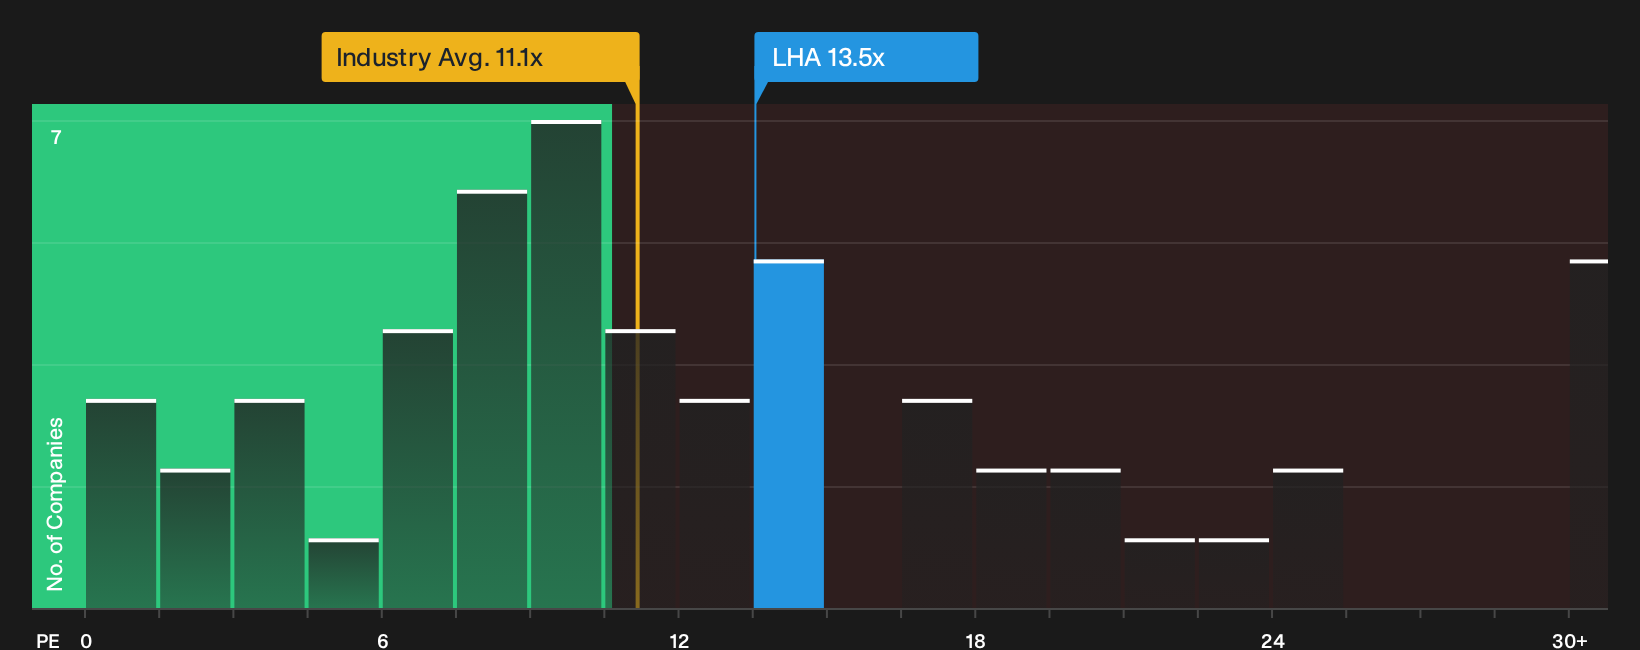
On earnings multiples, Deutsche Lufthansa looks less clear cut. The stock trades on a P/E of 13.5x, above both the peer average of 10.4x and the global airlines read of 11.1x, even though the fair ratio sits higher at 19.5x. That gap hints at upside potential, but the premium to rivals also builds in valuation risk if sentiment turns again. Which side of that trade-off do you put more weight on as war risk and cost pressure keep shifting?
To unpack what this P/E gap could mean in practice for future rerating risk or opportunity, review the full valuation breakdown in our comparative analysis, including how earnings quality, growth and capital intensity feed into that fair ratio view, via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the setup around Deutsche Lufthansa feel too skewed to risk or reward based on what you have read so far? Move quickly, review the underlying data for yourself, and pressure test the bullish and cautious angles against the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Deutsche Lufthansa?
If Deutsche Lufthansa has sharpened your focus on risk and reward, consider broadening your watchlist with other opportunities that can play different roles in your portfolio.
- Target potential mispricing by scanning a curated set of quality opportunities through the 174 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies that clear a high-yield hurdle in the 161 dividend fortresses.
- Protect your downside by focusing on financial resilience using the list of solid balance sheet and fundamentals (198 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com