
RLX Technology (RLX) Moved Today, What Is Driving Fresh Attention?
Index removal puts RLX Technology back in focus
RLX Technology (NYSE:RLX) has been removed from the FTSE All-World Index (USD), a shift that can affect benchmark-linked flows, investor attention, and how some institutions treat the stock in portfolio construction.
Recent trading reflects that shift in attention. RLX Technology has seen its share price return fall 25.86% year to date, while the 1 year total shareholder return is down 29.05%. However, the 3 year total shareholder return remains positive at 17.85%, suggesting longer term holders have had a different experience to recent buyers.
Balance the pressure around RLX Technology by assessing how other companies with a similar volatility profile stack up in our curated 30 resilient stocks with low risk scores before you decide where fresh capital should go.
After a sharp drop, RLX Technology now trades at a level where some investors see fresh upside while others think the rebound already happened. The valuation work shows which camp has stronger support in the numbers.
Most Popular Narrative: 38% Undervalued
RLX Technology last closed at $1.72, while the most followed narrative anchors fair value around $2.77. That gap reflects a view that current pricing does not fully align with the long term shift toward nicotine alternatives and the company’s broader product mix.
The ongoing global shift from traditional cigarettes to reduced-risk products, such as e-vapor and oral nicotine, is growing the overall nicotine alternatives market. RLX's leadership and early move into multi-category offerings position it to capture expanding consumer demand, supporting strong long-term revenue growth.
See why 12 investors see RLX Technology as 38% undervalued.
Result: Fair Value of $2.77 (UNDERVALUED)
Still, the bullish RLX Technology story can crack if tighter e-vapor rules or ongoing competition from illegal low cost products continue to put pressure on revenue and margins.
Find out about the key risks to this RLX Technology narrative.
Another View on RLX Technology’s valuation
While the crowd narrative points to RLX Technology trading below a $2.77 fair value based on analyst targets, the SWS DCF model presents a different picture. On that cash flow view, the shares look expensive at $1.72 compared with an estimated value of $1.02, which places more emphasis on execution risk rather than potential upside. Which lens do you trust more when real money is on the line?
Look into how the SWS DCF model arrives at its fair value.
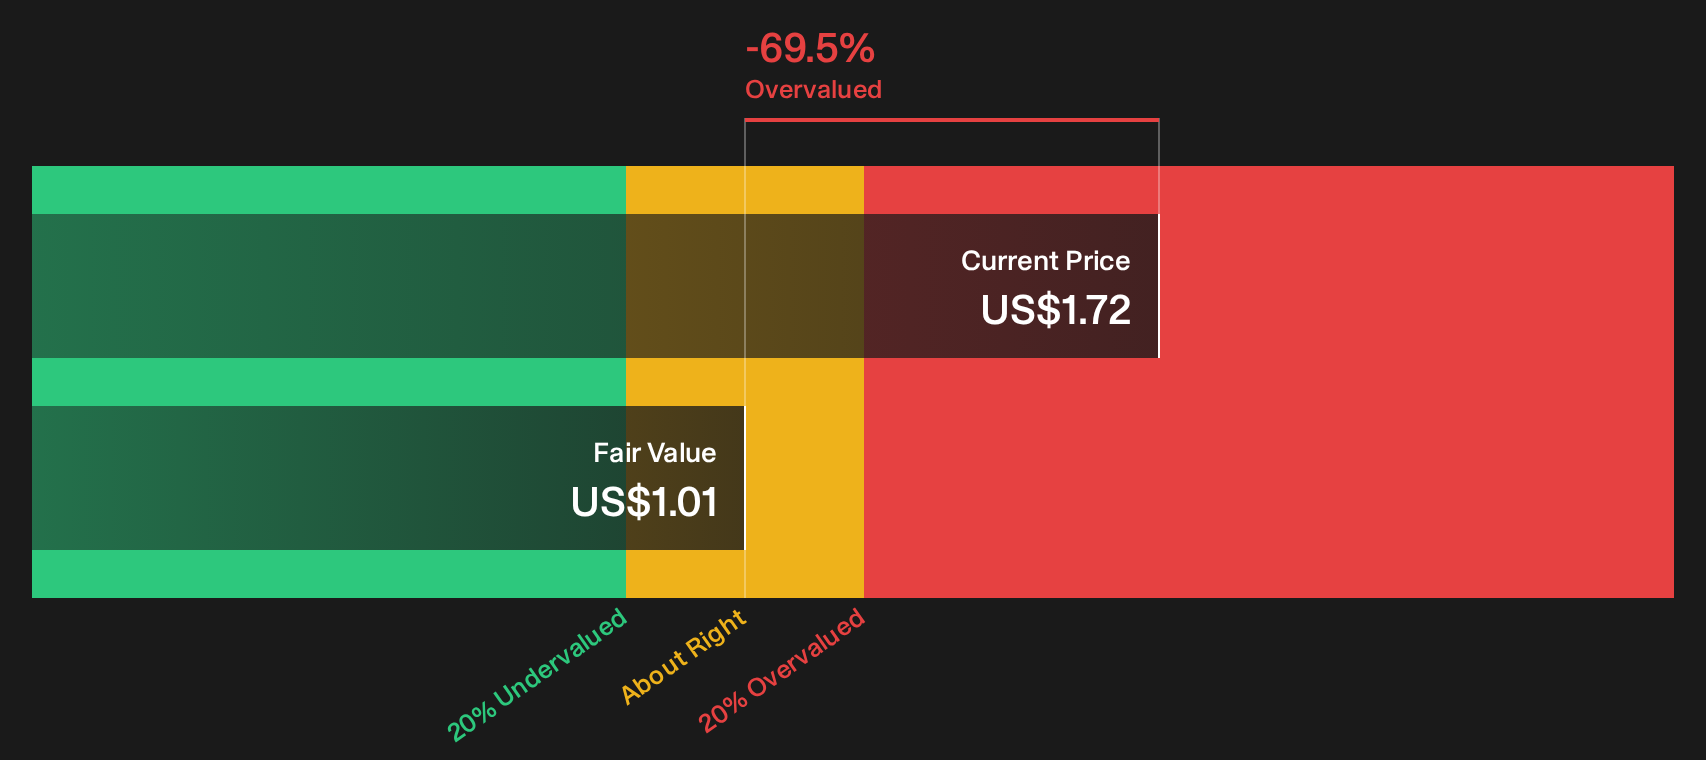
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RLX Technology for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed sentiment around RLX Technology is clear, so consider this your prompt to review the data now and decide where you stand with the 4 key rewards and 1 important warning sign.
Looking for more RLX Technology sized ideas?
Do not stop your research with RLX Technology. Use the Simply Wall Street Screener to quickly surface fresh opportunities that match how you like to invest.
- Target potential mispricings by scanning a curated 30 high quality undervalued stocks that blend solid fundamentals with compressed expectations.
- Strengthen capital protection by focusing on businesses from our list of solid balance sheet and fundamentals (23 results) that pair financial resilience with cleaner balance sheets.
- Spot early-stage opportunities by reviewing a 7 elite penny stocks with strong financials that filters for stronger financial profiles in lower priced shares.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com