
3 AI Chip Stocks Worth Watching As Data Center Spending Comes Back
AI chip headlines are back in the spotlight, with AMD brushing a $1 trillion valuation, semiconductor indices moving sharply, and fresh optimism around data center spending after the Trump-Xi state dinner plans and Meta’s new MUSE agent. That combination has pulled attention to AI semiconductor leaders again. This article unpacks how that news ties into three large chip stocks exposed to these AI themes and why they might deserve a closer look now.
The stocks covered below are just a sample, and the full screen surfaced 17 more AI semiconductor leaders with equally compelling stories that are not broken out in this article. To go straight to the source, use the AI Semiconductor Leaders screener to identify, filter, and analyze the highest conviction AI chip opportunities that fit your own rules.
Amlogic (Shanghai)Ltd (SHSE:688099)
Amlogic (Shanghai)Ltd is a fabless designer of system on a chip and peripheral semiconductors used in AIoT, smart home and multimedia devices, which ties it directly into the AI Semiconductor Leaders theme. It generated about CN¥7.9b from semiconductor integrated circuit chips and has a market value near CN¥37.6b.
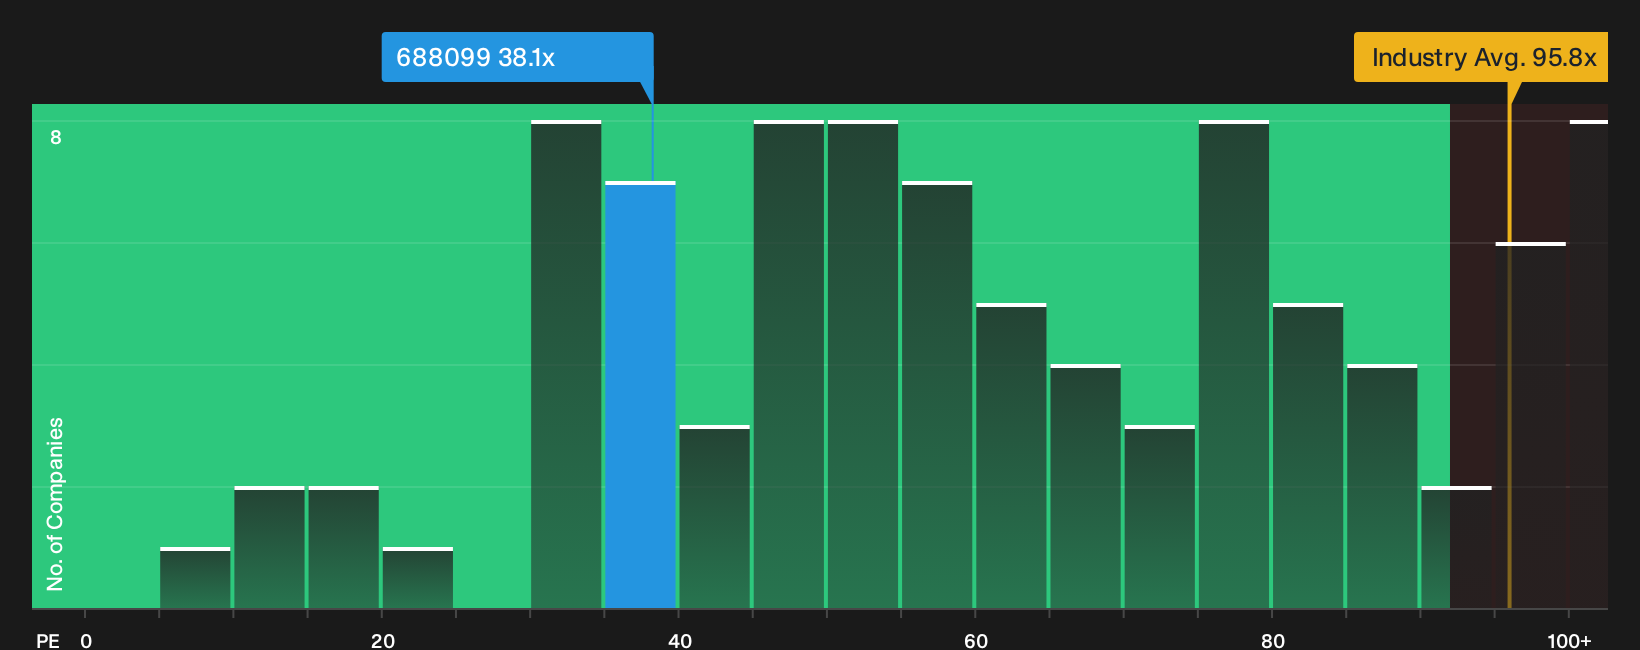
Amlogic (Shanghai)Ltd provides exposure to SoCs that sit inside AIoT gadgets, smart TVs and connected cars, positioned where AI workloads are moving closer to consumers. The stock trades on a lower P/E than many local chip peers, which keeps attention on how changes in margins may affect its valuation.
If valuation hinges on margins, the 4 key rewards and 1 important major warning sign shows what might be masking strengths or amplifying pressure beneath Amlogic (Shanghai)Ltd’s current pricing.
Rockchip Electronics (SHSE:603893)
Rockchip Electronics designs artificial intelligence focused application processors and mixed-signal chips for intelligent IoT gear, giving the stock a direct link to the AI Semiconductor Leaders theme at the edge of the network. The business generates about CN¥5.2b from large scale integrated circuits and application solutions and carries a market value near CN¥83.1b.
Rockchip Electronics ties AI inference directly into edge devices like tablets, smart audio and vision systems. This aligns with investors looking for AI semiconductor leaders beyond data centers. Earnings growth and margins set expectations for future cash generation, depending on how one unseen pressure in its model plays out.
That hinge point matters for Rockchip Electronics, so tap into the 4 key rewards and 2 important warning signs (1 is major!) to see whether that earnings engine is quietly stretching or already stalling.

Phison Electronics (TPEX:8299)
Phison Electronics plugs into the AI Semiconductor Leaders theme by supplying flash controllers and SSD solutions that help AI data centers and edge devices handle fast, heavy storage workloads, with its NT$149.8b flash memory control chip design segment driving revenue and a roughly NT$475.5b market value.
Phison Electronics gives you a way to play the AI storage buildout through controllers and SSDs. Management is leaning hard into internal tooling to try to make that opportunity more profitable and less bumpy than a typical memory cycle.
Advanced internal AI-driven process automation, including in chip design and engineering, is set to permanently lower fixed operating expenses and R&D costs, directly increasing net profit conversion and reducing earnings volatility relative to peers as industry wage inflation and design complexity rise.
What really moves the needle from here is how one key AI storage adoption curve shapes the balance between controller demand and pricing power.
If that adoption curve is the real swing factor, the full narrative for Phison Electronics shows how Phison Electronics could be decoupling earnings power from classic memory cycles.

Seeking Alternatives Before Momentum Flies
Fresh opportunities do not wait. Breakout themes build momentum, then slip once the crowd finally catches on. Scan these curated ideas while the data still matters and get in early.
- Spot potential turnarounds with clean finances before they start flying by checking the carefully filtered list of solid balance sheet and fundamentals (198 results).
- Explore structural demand in future-facing materials by reviewing the curated 36 best rare earth metal stocks.
- Look for cash generative AI exposure without focusing on short-term hype by reviewing the handpicked 38 profitable AI stocks that aren't just burning cash that already convert revenue into earnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com