
Willis Lease Finance (WLFC), What Is Behind The Fresh Attention?
Willis Lease Finance (WLFC) is drawing fresh attention after buying land in Malaysia to build a new Willis Engine Repair Center, a material expansion of its global maintenance footprint in Asia-Pacific.
For investors watching the tape, Willis Lease Finance now trades at US$54.74, with the share price up 22.44% year to date but down about 22% over the past 90 days, and a 5 year total shareholder return of 355.65% hinting at how strongly long term holders have been rewarded even as near term sentiment cools around execution and risk on newer projects such as the Malaysia repair hub.
Compare Willis Lease Finance's expansion story with other asset heavy aviation and industrial plays that have been screened for resilient balance sheets and cash flows in our curated list of solid balance sheet and fundamentals (23 results).
Willis Lease Finance is now caught between a share price that has cooled sharply in recent months and analyst and intrinsic estimates that sit much higher. Where does a fair entry or exit range actually land after the Malaysia move?
Price-to-Earnings of 13.5x: Is it justified?
Valuation for Willis Lease Finance starts with a simple comparison. The stock trades at a P/E of 13.5x, while peers and the wider US Trade Distributors industry sit much higher. Yet the share price has cooled even as this Malaysia engine center pushes the business deeper into capital intensive territory.
The P/E multiple measures what investors are paying today for each dollar of current earnings. For a leasing and servicing specialist like Willis Lease Finance, where aircraft and engine assets drive depreciation and financing costs, that earnings line reflects both operating performance and funding decisions.
Relative to its direct peer group, Willis Lease Finance screens as good value. The 13.5x P/E is far below the peer average of 61.4x and also below the US Trade Distributors industry average of 24.2x. This signals that the market is assigning a much lower price tag to each dollar of profit than it could based on those yardsticks. The estimated fair P/E of 19.3x is also well above the current multiple. This is a level the market could move toward if sentiment around earnings quality, funding risk and the Malaysia expansion improves.
Explore the SWS fair ratio for Willis Lease Finance.
Result: Price-to-Earnings of 13.5x (UNDERVALUED).
Still, the Malaysia engine project raises execution and funding risks for Willis Lease Finance, and any earnings disappointment could quickly challenge the current undervaluation story.
Find out about the key risks to this Willis Lease Finance narrative.
Another view using our DCF model
The P/E work-up presents Willis Lease Finance as cheap, yet the SWS DCF model suggests the opposite. That framework estimates future cash flow value at $9.96 per share, well below the current $54.74 price. If earnings appear inexpensive while cash flows indicate the stock is expensive, which lens should you rely on when sizing exposure?
Look into how the SWS DCF model arrives at its fair value.
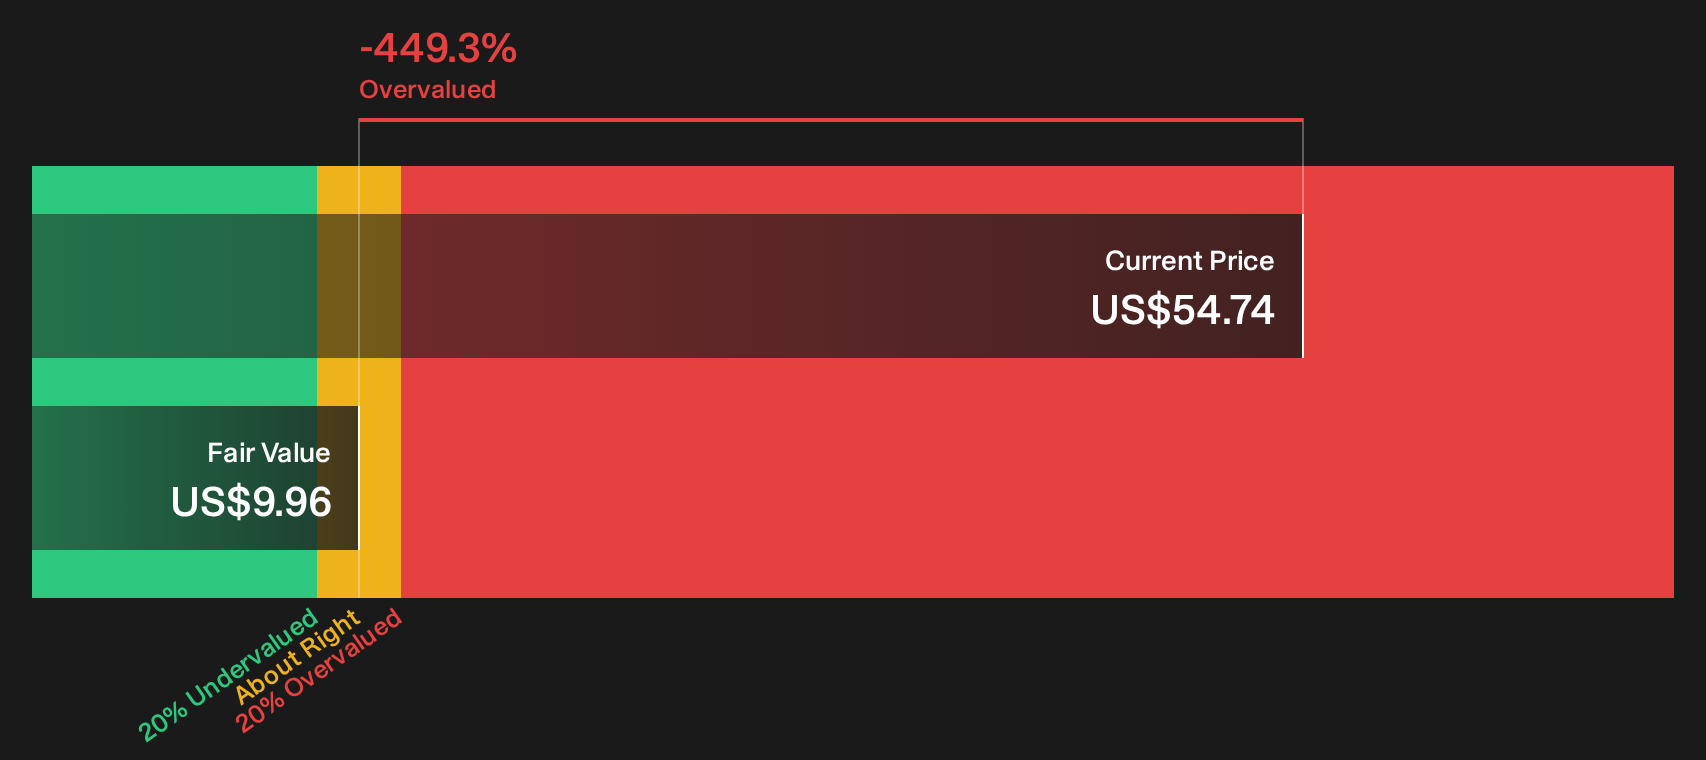
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Willis Lease Finance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Willis Lease Finance is clearly mixed, with both concern and optimism pulling at the same set of numbers. Act quickly and review the full risk and reward breakdown, starting with these 3 key rewards and 4 important warning signs.
Looking for more Willis Lease Finance style investment ideas?
If you only focus on Willis Lease Finance, you could miss other compelling setups that fit your risk profile and income goals across the wider market.
- Target reliable income streams by scanning for companies in the 7 dividend fortresses that match your need for yield with underlying financial strength.
- Hunt for quality at a sensible price by running the 30 high quality undervalued stocks and comparing those opportunities with what you see in Willis Lease Finance.
- Protect downside first and let upside surprise you by focusing on the 30 resilient stocks with low risk scores that pass your own standards for resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com